
Debt Collection Agency in Argentina: No Win, No Fee
Need a debt collection agency in Argentina? For unpaid invoices from business customers in Argentina, we match your case to a vetted partner covering Argentina under one contract, and you only pay when money is recovered.


Questions about your case?
Write to us, we reply by email.

Why choose Debitura for debt collection in Argentina
Getting started is simple
- Create your free Debitura account and submit your Argentine claim with the invoice and debtor details.
- EMS Debita Internacional takes the case and opens the amicable phase with a formal payment demand to your debtor.
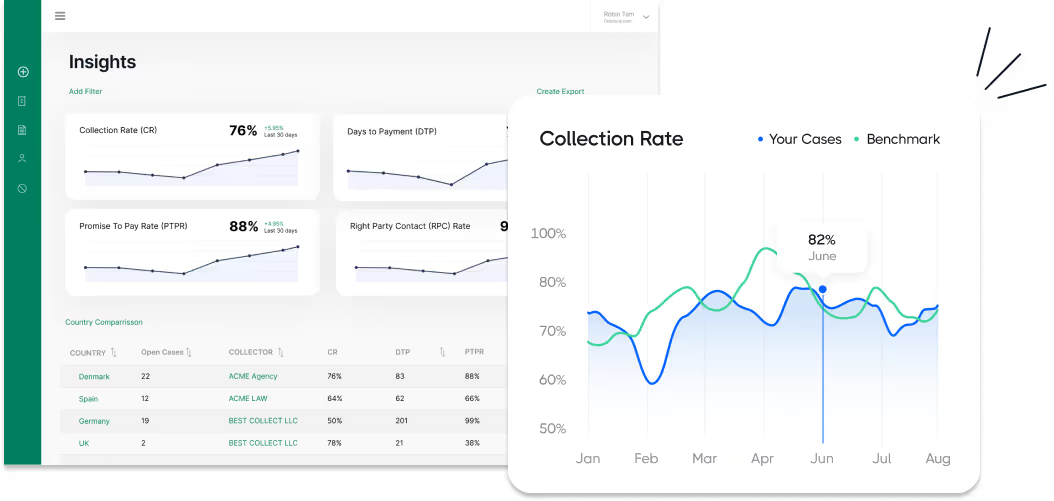
- Track progress in your dashboard and pay only when funds are recovered.
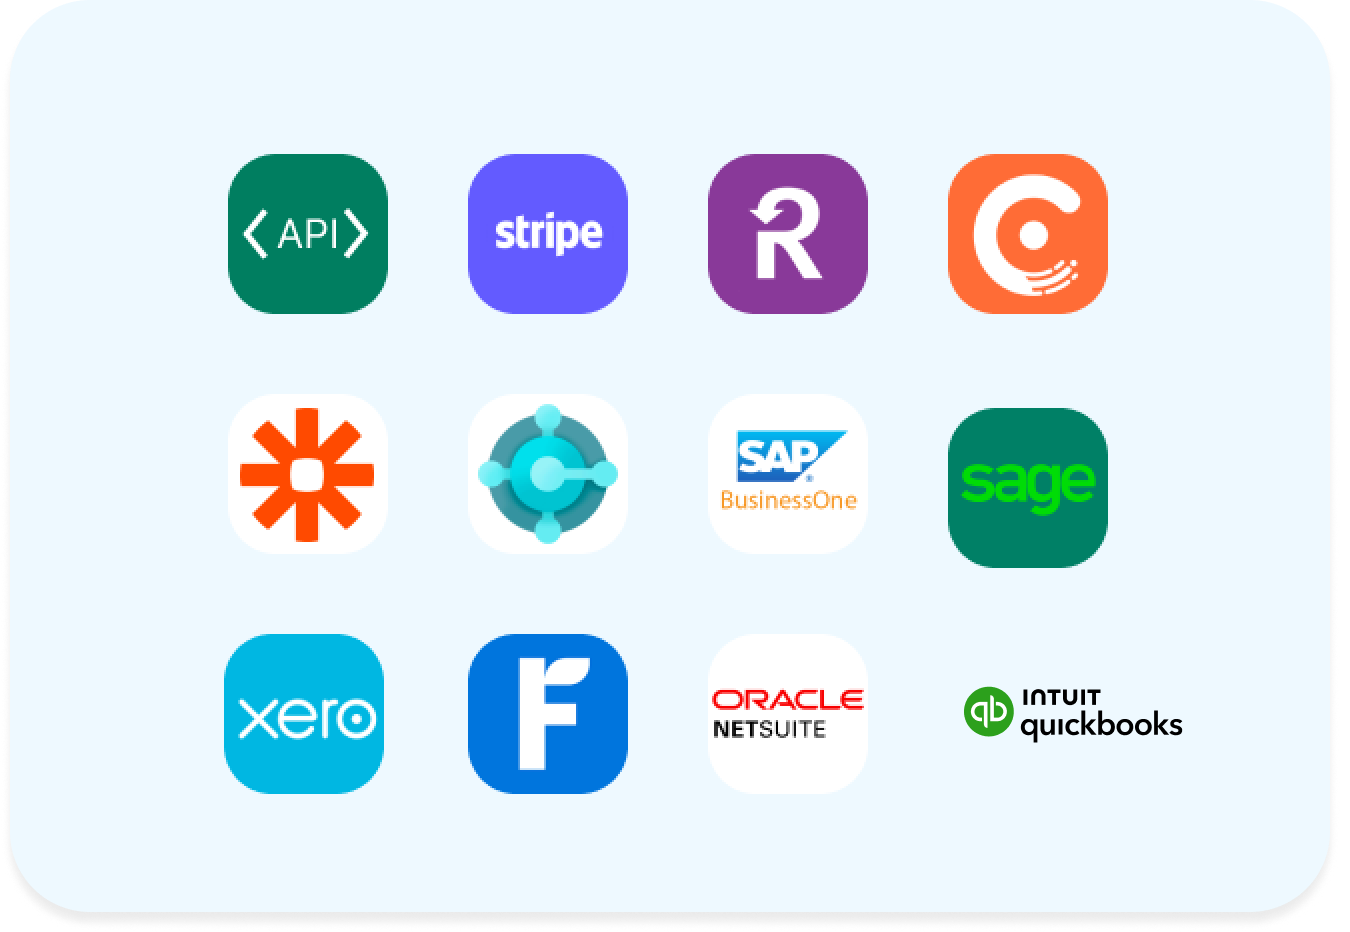
Already using accounting software or an ERP? Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
Transparent, success-based pricing
With Debitura you pay a success fee only when money is recovered. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Argentina?
Debt collection in Argentina starts with an amicable phase handled by a licensed partner: reminders and a formal payment demand, aimed at full payment or a written instalment agreement. If the debtor still does not pay, escalation to court is a separate, approved step - never automatic.
The four steps from unpaid invoice to recovered cash
- Amicable collection: reminders, a formal payment demand and negotiation, handled by a licensed partner. The aim is full payment or a written payment plan without going to court.
- Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a legal title, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Insolvency: if the debtor turns out to be insolvent, recovery depends on the local insolvency proceedings and is often uncertain. Any step in those proceedings is quoted separately and only starts if you accept.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Argentina - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in Argentina - the complete 2026 guide
This guide covers Debt Collection Argentina for creditors, in-house counsel and finance teams: the amicable phase, the routes to an enforceable title, enforcement, and insolvency, with the statutes and courts that apply. Argentina is a federation: 23 provinces plus Ciudad Autónoma de Buenos Aires (CABA) each run their own procedural code, so this guide uses the national/CABA framework as its reference point.
On this page:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).

Contributing local experts:
Last updated:

Debt collection in Argentina - quick answers
How long do I have to collect a debt in Argentina?
The general limitation period is 5 years unless a different period applies (Civil and Commercial Code, art. 2560). For actions under the Credit Card Law (Ley 25.065, art. 47), the periods are 1 year for an executive action and 3 years for an ordinary action. The general rule is that the clock starts when payment becomes legally due (art. 2554). Check the rules for the specific claim and any suspension or interruption.
| Claim type | Limitation period | Source |
|---|---|---|
| General civil/commercial debt | 5 years | CCyC art. 2560 |
| Credit Card Law, executive action | 1 year | Ley 25.065 art. 47 |
| Credit Card Law, ordinary action | 3 years | Ley 25.065 art. 47 |
What can pause or restart the limitation clock?
A payment demand from the creditor leaves time already elapsed on the limitation clock. A formal demand that can be reliably proved suspends the running period once, for six months or for the shorter limitation period that applies to the claim (Civil and Commercial Code, art. 2541). If the debtor acknowledges the debt while the limitation period is still running, the acknowledgement interrupts it under art. 2545 and a new period starts under art. 2544. Whether a part-payment amounts to an acknowledgement depends on the circumstances.
What interest can I charge on an unpaid debt in Argentina?
Article 768 of the Civil and Commercial Code gives priority to the parties’ agreed default-interest rate, then to applicable special laws. If neither supplies the rate, it refers to rates set under regulations of the Banco Central de la República Argentina (BCRA). In January 2026, the BCRA published the Tasa de Intereses Moratorios (TIM), a statistical series courts can use to determine default interest on debts in Argentine pesos under Article 768(c).
What is the first step in recovering a debt in Argentina?
Recovery starts with an amicable phase: a formal payment demand and negotiation aimed at a voluntary payment or a written instalment agreement, before any court filing. See Step 1 below. Debtors who respond promptly at this stage typically avoid the added court costs and interest described later in this guide.
Do I need a court judgment before I can enforce a debt in Argentina?
Yes. Enforcement (embargo, asset freeze or auction) requires an enforceable title, either a court judgment or another legally recognised enforceable instrument, obtained through the juicio ejecutivo (executive process) or ordinary proceedings described in Step 2 below. No enforcement authority in Argentina can seize assets without one. Which route applies depends on the evidence held: a qualifying enforceable instrument supports the faster juicio ejecutivo, while claims without one proceed as an ordinary civil or commercial action instead.
What does it cost to collect a debt in Argentina?
Argentina's national courts charge a fee set as a percentage of the claim's value, payable only if the case reaches litigation, and statutory interest applies where no contract rate has been agreed. See Fees, interest and who pays what in Argentina, below, for the exact rates. For claims that are not for a fixed sum of money, national courts apply a separate, periodically updated fixed fee instead of the percentage rate.
What documents do I need to collect a debt in Argentina?
Two documents form the baseline for any Debt Collection Argentina claim: the underlying invoice or contract, and evidence of the formal payment demand sent during the amicable phase. Reaching an enforceable title through the juicio ejecutivo (Step 2, below) requires a further, legally recognised enforceable instrument (título ejecutivo); claims without one still proceed, just through ordinary proceedings instead.
Who does what in Argentina debt collection?
Three types of actor handle a debt claim in Argentina: collection agencies for the amicable phase, lawyers for the judicial phase, and court officers for enforcement. Each operates under its own rules.
Debt collection agencies
Collection agencies run the amicable, pre-legal phase: verifying the debt, then sending reminders and a formal payment demand to reach a voluntary payment or instalment plan. They cannot enforce payment themselves; only a court can authorise enforcement. Their conduct is bound by the Ley de Defensa del Consumidor (the Consumer Protection Law, Ley 24.240), art. 8 bis, which requires dignified and equitable treatment and bans humiliating, vexatious or judicial-appearance-simulating tactics, backed by civil fines under art. 52 bis. In Ciudad Autónoma de Buenos Aires (CABA, Buenos Aires City), Ley 6.171 (2019) adds mandatory disclosure on first contact, a fixed list of permitted channels, and specific bans, including contacting the debtor's employer, exposed mail, calls between 20:00 and 8:00 on weekdays, and unauthorised publication of debtor lists, enforced under Ley 24.240's sanctions regime. Ley 6.171 does not apply to family, labour, or state tax and administrative debts, which fall outside its scope.
Lawyers
Lawyers take over once amicable collection fails. They draft and file the claim, represent the creditor before the competent court, and pursue the enforceable title needed to enforce the debt (see Step 2). Legal representation is required once a case moves to ordinary court proceedings (see Which laws and courts apply, below).
Bailiffs (Oficiales de Justicia)
Court-appointed officers, known as Oficiales de Justicia, execute enforcement once a judge issues an order: attaching assets, freezing bank funds, and carrying out judicial auctions. Argentina has no separate national enforcement or bailiff agency; every enforcement step is supervised directly by the court (see Step 3).
Insolvency trustees (síndicos)
A court-appointed síndico (trustee) takes over if a debtor becomes insolvent: verifying each creditor's claim and administering the case under the Ley de Concursos y Quiebras (see Step 4, below). No single national licensing regime governs commercial debt-collection agencies in Argentina; regulation instead comes from consumer-protection law nationally and from Ley 6.171 in CABA.
Which laws and courts apply to debt collection in Argentina?
Governing statutes
Private debt claims run on the general civil and commercial limitation period of 5 years (Código Civil y Comercial, CCyC, art. 2560), with a shorter regime for credit-card debt under Ley 25.065, art. 47 (1 year for an executive action, 3 years for an ordinary action). Civil and commercial procedure, including the route to an enforceable title, runs under the Código Procesal Civil y Comercial de la Nación (the National Civil and Commercial Procedure Code, CPCCN, Ley 17.454 as amended); its juicio ejecutivo (executive process), at Título II, arts. 520-594, applies to claims backed by a legally recognised enforceable instrument. Court costs before national courts are set by the Ley de Tasas Judiciales (the Judicial Fees Law, Ley 23.898). Collection conduct is governed by the Ley de Defensa del Consumidor (Ley 24.240) nationally, and by Ley 6.171 for extrajudicial collection agents contacting debtors in CABA. Insolvency, where relevant, falls under a separate statute covered in Step 4, below. The CPCCN has been amended several times since its enactment, most notably by Ley 25.488. Under Ley 23.898, national courts charge a percentage-based fee for pecuniary claims (art. 2) and a separate, periodically updated fixed fee for non-pecuniary proceedings (art. 6); CABA's consumer-protection authority enforces Ley 6.171 breaches under Ley 24.240's own sanctions regime, specifically at art. 13.
Court structure
National and CABA claims run through the Juzgados Nacionales de Primera Instancia (the National Courts of First Instance, Comercial or Civil y Comercial Federal), with appeals to the Cámara Nacional de Apelaciones (the National Court of Appeals) and, on federal-law questions, the Corte Suprema de Justicia de la Nación (the Supreme Court of Justice). Argentina is a federation: each of its 23 provinces plus CABA sets its own procedural code and small-claims thresholds, so the court and threshold that apply depend on where the debtor is based. In Mendoza, an individual consumer or user can use the province’s small-claims procedure for a claim arising from a consumer relationship up to 5 JUS (ARS 3,143,652.15 in 2026). For unpaid business invoices, check the ordinary or executive procedure in the relevant jurisdiction. Which court has jurisdiction over a specific claim therefore depends on both the claim's value and the debtor's registered address. Access to the Corte Suprema specifically requires a recurso extraordinario federal (federal extraordinary appeal), reserved for questions of federal law or constitutional significance.
Step 1 - How does amicable (pre-legal) debt collection work in Argentina?
Amicable collection in Argentina starts with verifying the debt, then sending the debtor a formal payment demand and negotiating a voluntary payment or instalment plan, without going to court.
Verification and first contact
Before contacting the debtor, the claim is checked against the invoice, contract or other supporting documents. First contact then sets out the amount owed, the basis for the claim, and a deadline to pay or respond. Argentina has no nationally prescribed demand-letter form for B2B claims; a clear written demand setting out the amount owed, its basis and a deadline to respond is the conventional format used in practice.
Conduct rules
Communication must stay within Ley 24.240, art. 8 bis: dignified and equitable treatment, no humiliating or vexatious tactics, and no contact that simulates a judicial appearance. In CABA, Ley 6.171 adds a fixed disclosure on first contact, permitted channels, and specific bans (contacting the employer, exposed mail, calls between 20:00 and 8:00 on weekdays, unauthorised publication of debtor lists). Breaches carry civil fines under Ley 24.240, art. 52 bis. Permitted channels under Ley 6.171 include phone, email, post, voice or text messages, and instant messaging, provided the debtor's dignity is respected throughout; first-contact disclosure must itemise the original debt, accrued interest and collection costs separately.
Pausing or restarting the limitation clock
A payment demand from the creditor leaves time already elapsed on the limitation clock. A formal demand that can be reliably proved suspends the running period once, for six months or for the shorter limitation period that applies to the claim (Civil and Commercial Code, art. 2541). If the debtor acknowledges the debt while the limitation period is still running, the acknowledgement interrupts it under art. 2545 and a new period starts under art. 2544. Whether a part-payment amounts to an acknowledgement depends on the circumstances.
Escalation to court
If the debtor still does not pay, moving to court is a separate, approved step (see Step 2), never an automatic consequence of a missed amicable deadline.
Step 2 - How do you obtain an enforceable title in Argentina?
An enforceable title in Argentina comes from a court, most commonly through the national juicio ejecutivo (executive process) when the claim rests on a legally recognised enforceable instrument, or through ordinary proceedings for claims that lack one or are contested on the merits.
Juicio ejecutivo (executive process)
Under the CPCCN, Título II, arts. 520-594, the juicio ejecutivo is a summary procedure available when the creditor holds a legally recognised enforceable instrument. It is faster than ordinary proceedings because the debtor's defences are limited by law, and it ends in a judgment that can go straight to enforcement (Step 3).
Ordinary proceedings
Claims without an enforceable instrument, or where the debtor disputes the underlying facts, go through ordinary proceedings under the CPCCN. These allow a fuller exchange of evidence and argument, but take longer, and legal representation is required throughout. For actions under the Credit Card Law (Ley 25.065, art. 47), the periods are 1 year for an executive action and 3 years for an ordinary action. A creditor who misses the executive deadline can still consider ordinary proceedings if the three-year period remains open.
Provincial small-claims routes: Mendoza as an example
In Mendoza, an individual consumer or user can use the province’s small-claims procedure for a claim arising from a consumer relationship up to 5 JUS (ARS 3,143,652.15 in 2026). For unpaid business invoices, check the ordinary or executive procedure in the relevant jurisdiction.
More on court proceedings in Argentina
Choosing the route
The route depends on what evidence the creditor holds and where the debtor is based. An instrument that qualifies under the national procedural code (arts. 520 and 523) or the applicable local procedure may support the executive route. Card issuers preparing an executive action against a cardholder must follow Article 39 of the Credit Card Law. Check the applicable local procedure for ordinary or small-claims routes.
What the judgment allows
A favourable judgment, whether from the juicio ejecutivo, ordinary proceedings, or a provincial small-claims track, becomes the enforceable title used to attach assets, freeze bank funds, or force a judicial auction (Step 3).
Step 3 - How does debt enforcement work in Argentina?
Once a court issues an enforceable title (Step 2), enforcement in Argentina proceeds through embargo (attachment), inhibición general de bienes (a general freeze on the debtor's assets), or remate (judicial auction), all carried out under the supervision of the court. In the juicio ejecutivo route specifically, this judgment takes the form of a sentencia de trance y remate (order for sale to satisfy the debt).
Enforcement measures
Embargo lets the creditor attach specific assets, such as bank funds or property, up to the value of the claim. Inhibición general de bienes freezes the debtor's ability to sell or encumber assets generally, useful when specific assets are not yet identified. Remate is a judicial auction of seized assets, with proceeds applied to the claim. A court can order more than one of these measures in the same case, depending on what assets are located.
Who carries it out
Argentina has no separate national enforcement or bailiff agency. Every measure is judge-supervised and carried out through the court's own oficial de justicia (court enforcement officer), who locates and values assets, organises the auction where needed, and oversees distribution of the proceeds. The creditor's lawyer requests each measure from the court; the oficial de justicia then executes it. For the auction itself, the court typically appoints a martillero (court-appointed auctioneer) to conduct the sale.
Sequencing and stopping enforcement
Enforcement typically starts with locating assets to attach or freeze, then moves to a judicial auction only if the debtor still does not pay. A debtor can pay off the claim, including accrued statutory interest and costs, at any point before or during enforcement to have the measures lifted.
Order of enforcement in practice
An official state debt-recovery instructional document describes courts typically targeting the debtor's bank accounts first, before moving to real estate or other registered property, then wages, or a general inhibición general de bienes when no specific asset has yet been identified. Enforcement of the judgment itself proceeds under the CPCCN's own Título I, "Ejecución de Sentencias" (Judgment Enforcement), arts. 499-519 bis.
Timelines
Argentine law does not set a fixed statutory deadline for completing enforcement once a title issues; how long it takes depends on how quickly the debtor's assets can be located and valued, and on the court's own caseload. Cases with clearly identified assets, such as a known bank account, generally move faster than cases requiring extensive asset tracing.
Costs
Enforcement adds the tasa de justicia (3% of the claim's pecuniary value under Ley 23.898, art. 2) and any further court and legal-representation costs to the case; see Fees, interest and who pays what, above, for how these costs and any recovered interest are allocated.
Step 4 - How do insolvency procedures affect debt recovery in Argentina?
Insolvency in Argentina is governed by the Ley de Concursos y Quiebras (the Bankruptcy and Insolvency Law, Ley 24.522, "LCQ"). It applies to individuals and private legal entities alike and offers two paths: concurso preventivo (a court-supervised reorganisation) or quiebra (full bankruptcy and liquidation). Insolvency changes how a creditor recovers a debt: instead of individual enforcement against one debtor's assets, all creditors' claims are handled together, in one court-supervised process.
What triggers insolvency proceedings
The trigger is cesación de pagos, a general inability to regularly meet obligations as they fall due (LCQ arts. 1, 78), rather than a single missed payment. Any individual or private legal entity may petition for concurso preventivo, provided no bankruptcy has already been declared (LCQ arts. 2, 5, 10). Once proceedings open, a creditor's individual enforcement action against that debtor is generally superseded by the collective insolvency process. Eligible petitioners include not only individuals and private legal entities but, in some cases, state-owned entities as well (LCQ arts. 2, 5, 10).
Concurso preventivo (reorganisation)
In a concurso preventivo, the debtor proposes a repayment or restructuring plan to creditors under court supervision, aiming to avoid liquidation, while a court-appointed trustee (síndico) reviews and verifies creditor claims. If the court declares the reorganisation agreement fulfilled, the debtor cannot file for a new concurso preventivo for one year (LCQ art. 59).
Quiebra (full bankruptcy)
Where reorganisation is not attempted or does not succeed, the LCQ's bankruptcy path applies instead: the debtor's assets are liquidated under trustee supervision and the proceeds distributed among creditors according to the priority rules below. This path is the more disruptive of the two for an ongoing business, since it generally ends the debtor's control over its own assets.
How claims are prioritised
Under Insolvency Law 24.522, Article 240 generally gives qualifying estate and proceeding expenses priority over claims against the debtor, subject to claims with special privilege. Article 241 identifies claims with special privilege over the proceeds of specified assets, including claims secured by mortgages or pledges. Article 16 provides a separate early-payment procedure for qualifying employee claims. In a preventive reorganisation, creditors with pre-filing claims generally submit them for verification to the insolvency trustee by the date set by the court (Articles 14 and 32).
After the proceedings close
A bankruptcy declaration carries an inhabilitación (a disqualification) for the debtor, which ceases automatically one year after the bankruptcy decree unless extended (LCQ art. 236). Recovery through insolvency proceedings can take time; creditors should expect a court-supervised, multi-step process, with recovery depending on what other creditors also claim and what assets the estate holds, rather than a quick payout. As Mendoza's own Poder Judicial has confirmed, quoting LCQ art. 236 directly, "the disqualification of the bankrupt ceases automatically after one year from the bankruptcy decree."
Fees, interest and who pays what in Argentina
- Our fee: success-based - No Cure, No Pay (see pricing).
- Court & enforcement fees: state fees apply only if the case escalates to legal action.
- Statutory debtor items: late-payment interest and recoverable collection costs are added to the debt where the law allows.
- Who keeps what: recovered principal is yours; statutory costs and interest follow local rules.
Argentina's statutory court fee and interest rate
Before national courts, the tasa de justicia (court fee) is 3% of the claim's pecuniary value (Ley de Tasas Judiciales, Ley 23.898, art. 2). For default interest, Article 768 of the Civil and Commercial Code looks first to the parties’ agreement, then to applicable special laws, and otherwise to rates set under central-bank regulations. The BCRA’s Tasa de Intereses Moratorios (TIM) is a tool courts can use to determine default interest on peso debts. The court-fee statute sets the court fee at "TRES POR CIENTO (3%)" for "todas las actuaciones... susceptibles de apreciación pecuniaria" (three percent, for all proceedings susceptible of pecuniary appraisal); claims that are not for a fixed sum instead pay a separate, periodically updated fixed fee (Ley 23.898, art. 6).
Interest keeps accruing during enforcement
Statutory interest under CCyC art. 768 continues to accrue on the outstanding balance through the amicable phase, litigation and enforcement, until the debt is paid in full; settling early avoids further interest and the court fees described above.
Partners in our network
These firms are partners in our network for this country. Open a profile to learn more about each one. If court action is needed on your case, your partner sends a quote on the platform; nothing starts until you accept it.
- Verified specialists
- Nothing starts until you accept the quote
- Fair, pre-negotiated rates

Garcia Menendez is a premier law firm in Buenos Aires offering effective Debt Collection services in Argentina, recognized by Euromoney Expert Guides and Global Competition Review, with competitive fees and membership in MSI Global Alliance, ensuring top-tier legal expertise.


Riskma Solutions is a premier debt recovery agency in Buenos Aires offering effective debt collection services in Argentina, recognized for its strategic expertise since 2014, operating on a contingency fee model and serving clients in Argentina and Uruguay.
Valle&Gallo is a premier law firm in offering effective Debt Collection services in AR, recognized for its expertise since 2019 and distinguished by industry accolades and memberships, positioning the firm as the go-to partner for debt recovery.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.






