Debt Collection Agency in the Netherlands: No Win, No Fee
Need a debt collection agency in the Netherlands? Your claims are handled by Bureau Mercuur, our Dutch debt collection partner (incassobureau), founded in 1908 and registered in the Justis incassoregister.


Questions about your case?
Write to us, we reply by email.

Why choose Debitura for debt collection in the Netherlands
Getting started with Dutch debt collection
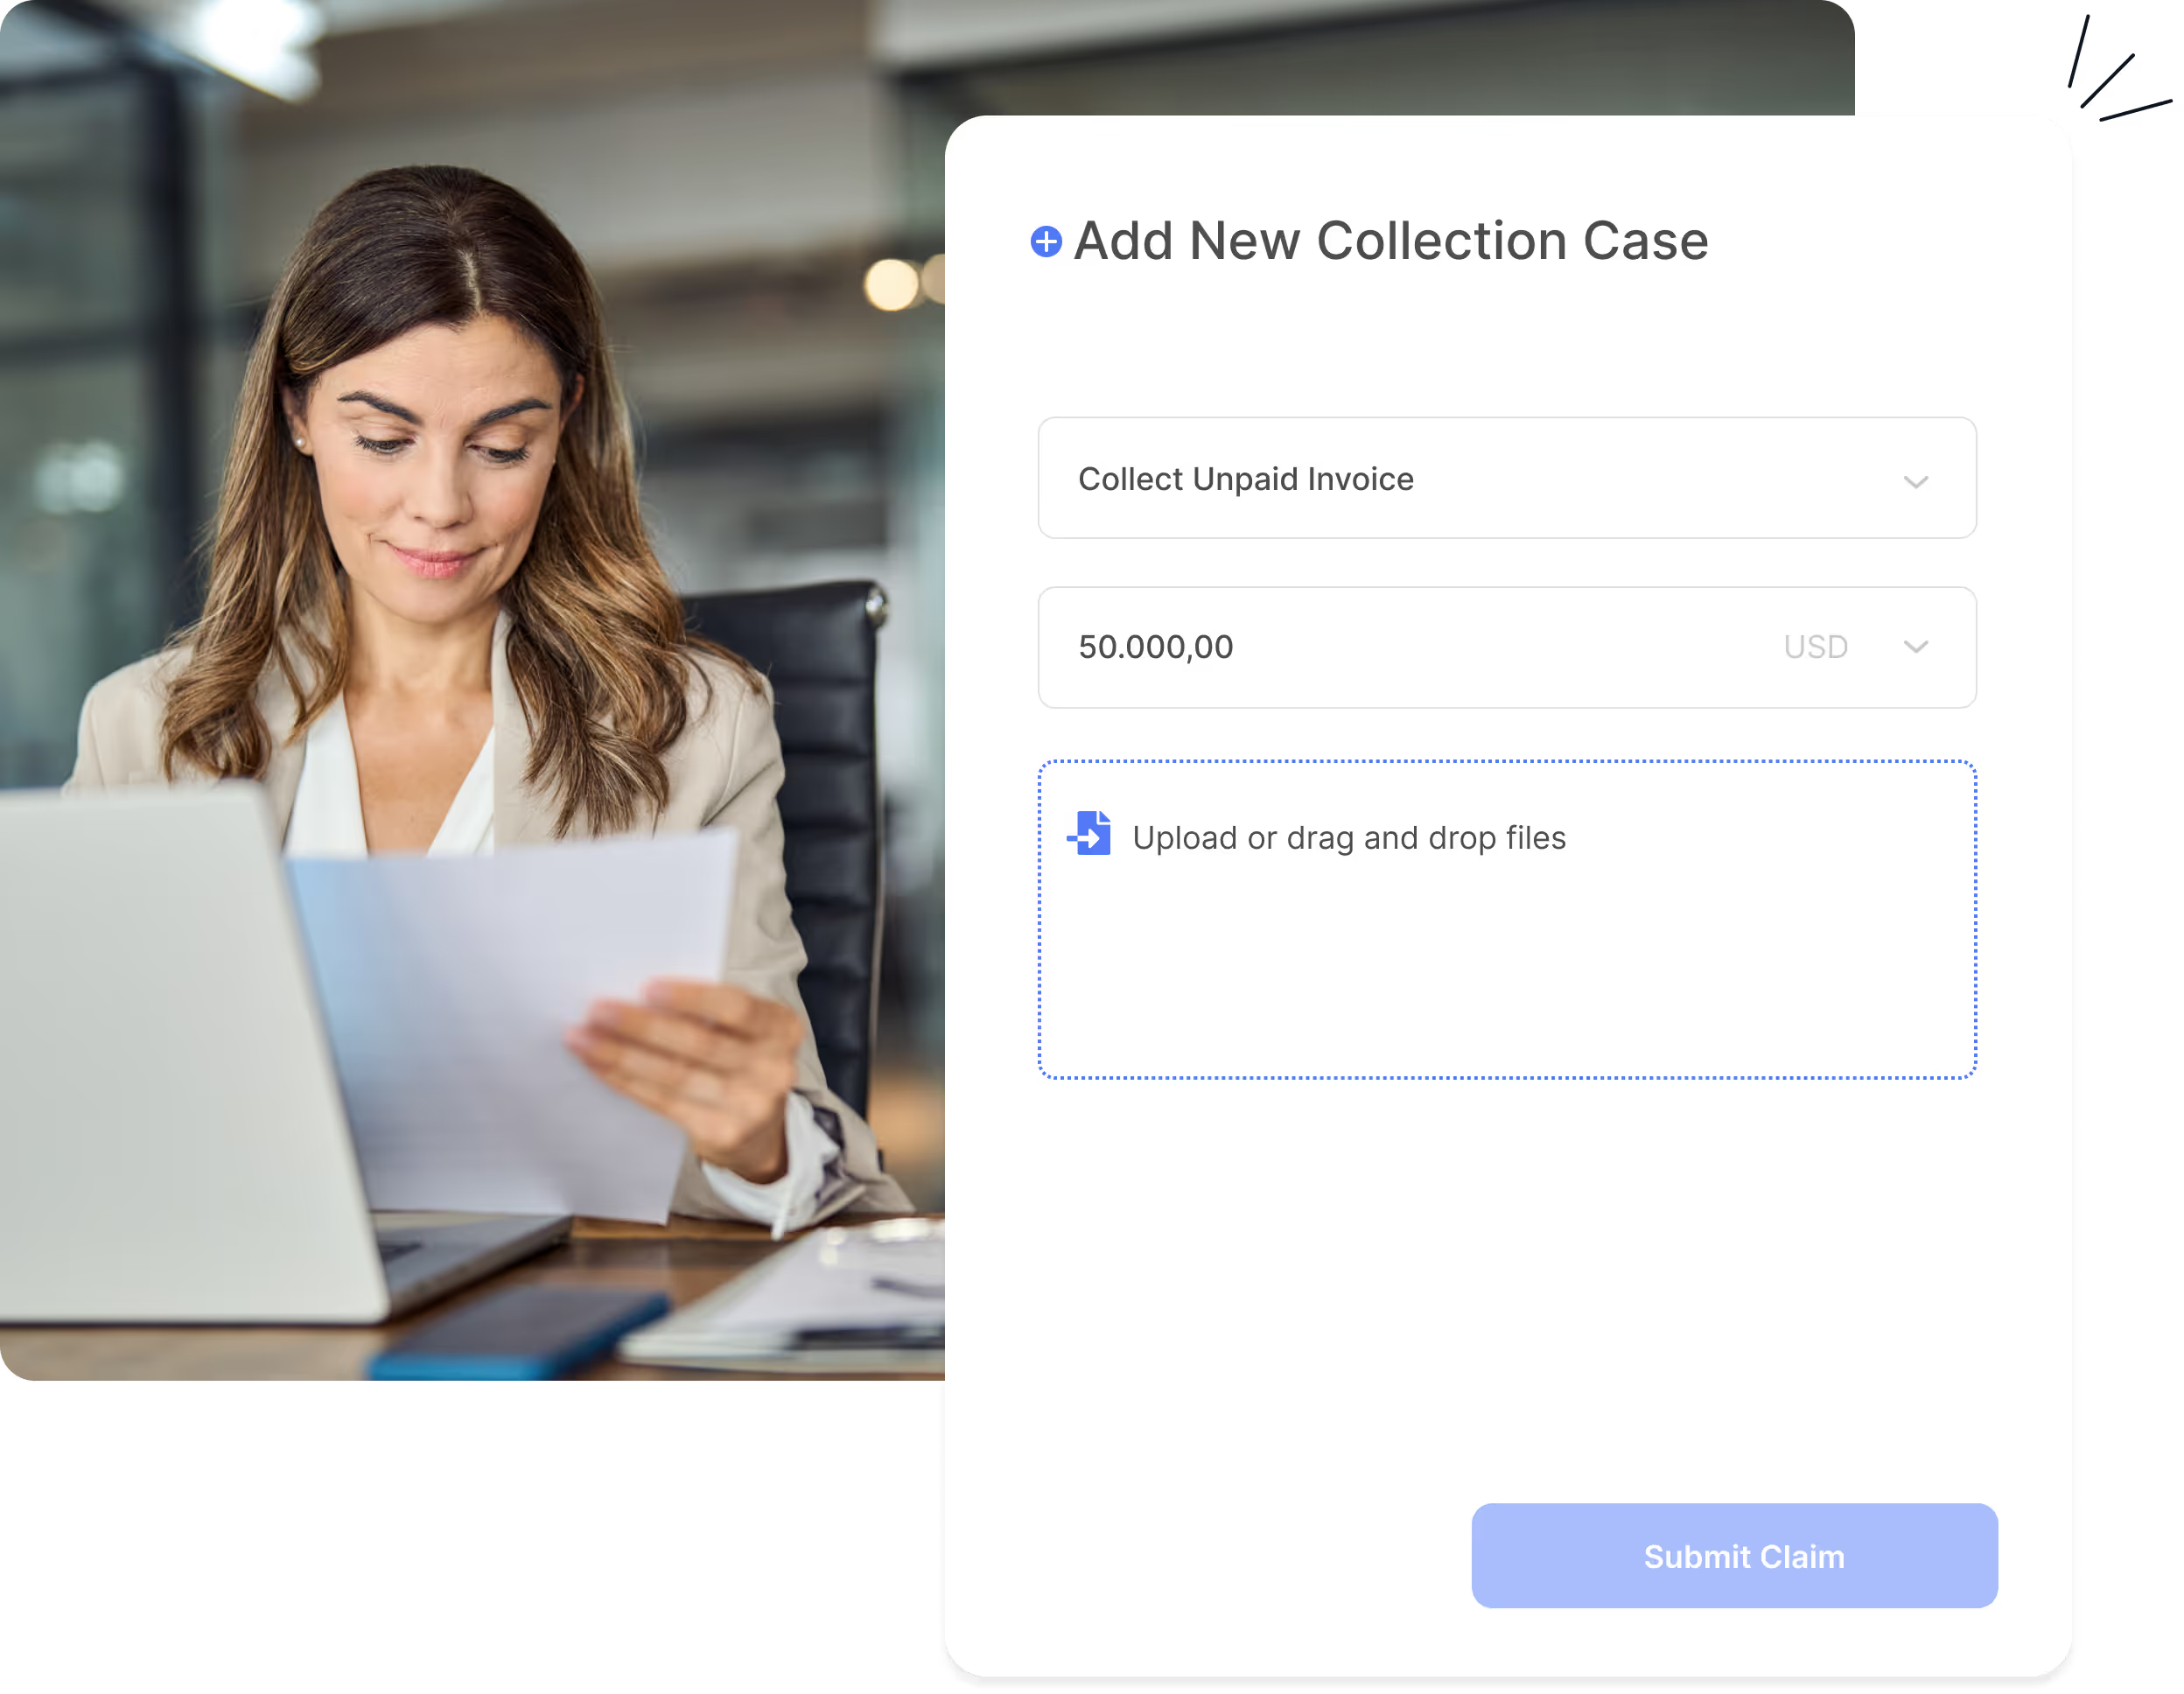
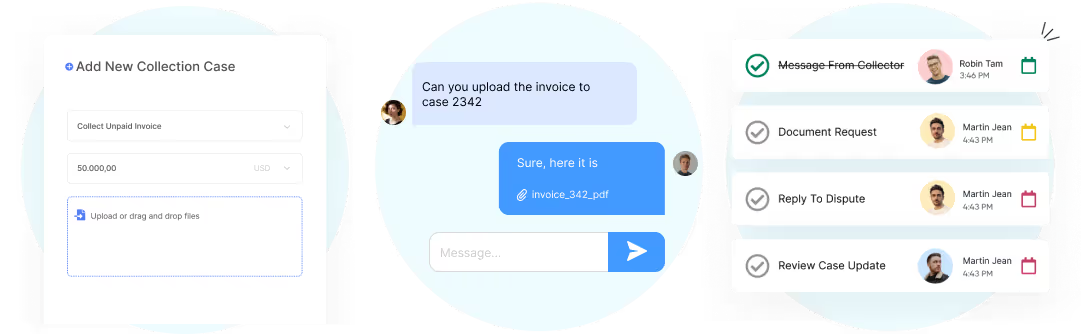
- Upload your claim: Submit your unpaid invoice through Debitura's dashboard in under 2 minutes. Include debtor details and supporting documents.
- Bureau Mercuur takes action: after checking your claim and the debtor's details, our Dutch partner sends the first collection letter in Dutch, by post and by email. A reminder follows after a week, and phone calls and text messages start if the debtor still has not paid.
- Track and recover: Monitor progress in real time. Pay only when your money is recovered.
Already using accounting software or an ERP? Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12–24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
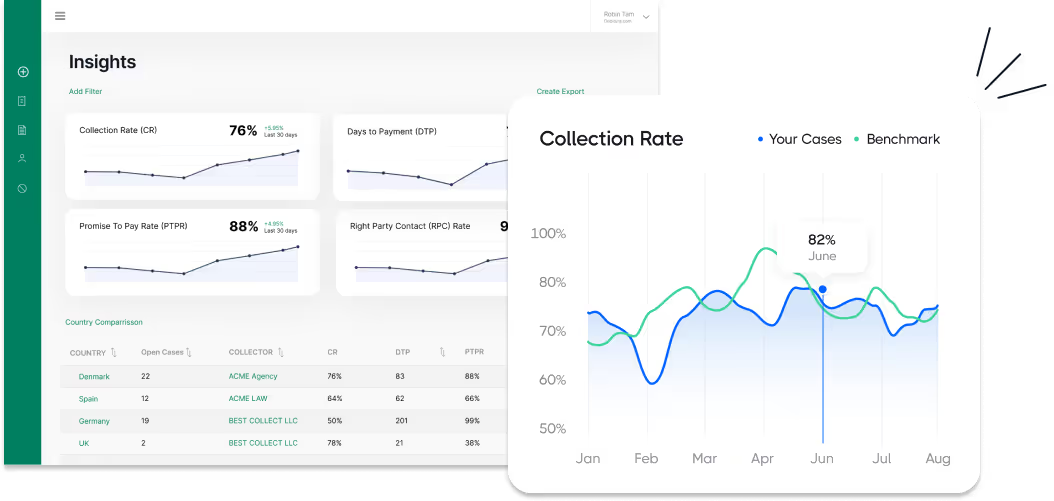
How does debt collection work in the Netherlands?
Debt collection in the Netherlands starts with an amicable phase handled locally by Bureau Mercuur: reminders and a formal payment demand, aimed at full payment or a written instalment agreement. Most straightforward claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic - your partner assesses the legal route and you approve a quote before any court step.
In the video below, the CEO of Bureau Mercuur, our partner in Groningen, explains how debt collection in the Netherlands works in practice, from the first letter to enforcement.
The four steps from unpaid invoice to recovered cash
- Amicable collection: reminders, a formal payment demand and negotiation, handled locally by Bureau Mercuur. Most undisputed claims are resolved in this phase, without going to court.
- Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a legal title, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Insolvency: if the debtor turns out to be insolvent, your proof of claim is filed and any distributions are monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for the Netherlands - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in the Netherlands - the complete 2026 guide
Struggling with unpaid invoices in the Netherlands? Debitura streamlines your debt recovery process, offering a convenient and easy solution with no upfront cost. Our guide provides step-by-step instructions, sample contracts, free templates, and best practices for debt collection under Dutch law.
On this page:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).
Contributing local experts:
Last updated:

Quick answers: debt collection in the Netherlands
How much does debt collection cost in the Netherlands?
Only the claimant pays griffierecht (court registration fee) in a kantonzaak (subdistrict case); the defendant pays nothing. The 2026 scale for claims up to €500 or of undetermined value is €93 for a natural person or €139 for a legal entity, rising through the bands to €753 or €1,504 for claims above €12,500. A flat €93 low-income rate applies at any claim value if the claimant submits a legal-aid income statement. The court can order the losing party to pay a contribution toward the winning party's procedural costs (a kostenveroordeling), calculated on a flat-rate tariff basis rather than actual costs incurred. Extrajudicial collection costs a creditor may add before going to court are separately capped under the Wet Incassokosten (WIK) scale.
How long does debt collection take in the Netherlands?
A dagvaarding (summons) must generally be served on the defendant at least one week before the cause-list hearing, extended to at least four weeks if the defendant is domiciled or resident outside the Netherlands. If the defendant does not respond, the kantonrechter (subdistrict court judge) pronounces a default judgment (verstekvonnis) usually within two weeks of the hearing; the defendant can still object within four weeks of being notified. If the defendant does respond, the claimant's written reply is due within four weeks, and judgment typically follows around four weeks after the hearing. Appeal must be lodged within three months of judgment.
What is the statute of limitations on debt in the Netherlands?
The general limitation period for a civil claim is 20 years, but a shorter 5-year period applies to many claims, including a claim for performance of a contractual obligation, running from the day after the claim became due. The price of goods sold to a consumer, including gas and electricity, prescribes after 2 years (art. 7:28 BW); consumer services follow the 5-year rule. A running period is interrupted only by a written reminder or a written notice that clearly reserves the right to payment (art. 3:317 BW), or by the debtor acknowledging the debt, for example with a part payment or a payment plan (art. 3:318 BW); a phone call is not enough. A new period of the same length, up to 5 years, then begins. Statutory interest (wettelijke rente) for consumer and non-commercial debts is 4% since 1 January 2026; statutory commercial interest (wettelijke handelsrente) for B2B and business-government contracts is 10.4% since 1 July 2026. Extrajudicial collection costs are capped under the WIK scale at 15% on the first €2,500 of the outstanding amount, 10% on the next €2,500, 5% on the next €5,000, with a statutory minimum of €40 and a maximum of €6,775.
What documents do I need to collect a debt in the Netherlands?
For obligations without an agreed fixed deadline, the debtor is only legally in default (verzuim) after receiving a formal written notice of default (ingebrekestelling) that gives a reasonable further period to perform. A dagvaarding must state the date of service, the parties' identifying details, the bailiff's details, the claim and its grounds, and the supporting evidence relied on, such as the contract, invoices and correspondence. A gerechtsdeurwaarder (bailiff) must formally serve the dagvaarding on the defendant before it can be filed with the court.
Which legal route should I use to collect a debt in the Netherlands?
The kantonrechter (subdistrict court) handles money claims up to and including €25,000, plus all employment, lease, consumer-sale and consumer-credit disputes regardless of value; legal representation is optional and a non-lawyer authorised representative is permitted. The rechtbank (district court) handles civil claims above €25,000, where legal representation by an advocaat is mandatory. Both use the dagvaardingsprocedure (summons procedure). For cross-border claims, the European Small Claims Procedure is available up to €5,000, and the European Order for Payment is available for uncontested cross-border claims above €2,000 through the District Court of The Hague.
| Claim value (kanton) | Griffierecht, natural person / legal entity |
|---|---|
| Up to €500 | €93 / €139 |
| €500 to €1,500 | €233 / €350 |
| €2,500 to €5,000 | €265 / €529 |
| Above €12,500 | €753 / €1,504 |
Who does what in the Netherlands debt collection?
Dutch debt recovery separates three roles: the collection agency handles the amicable phase, the gerechtsdeurwaarder (bailiff) enforces court judgments, and an advocaat (lawyer) is required only for claims above €25,000.
Collection agencies
Collection agencies handle extrajudicial (amicable) recovery: reminders, negotiation and payment plans. Since 1 April 2024, the Wet kwaliteit incassodienstverlening (Wki, the Debt Collection Services Quality Act) requires every consumer-debt collector to register in the Justis incassoregister and meet quality and conduct standards, enforced by the Inspectie Justitie en Veiligheid. Agencies cannot themselves obtain a court judgment or seize assets; that requires a bailiff or, above €25,000, an advocaat.
Gerechtsdeurwaarder (bailiff)
A KBvG-registered gerechtsdeurwaarder serves the dagvaarding (summons), and once a court judgment (executoriale titel) exists, enforces it nationwide through loonbeslag (wage garnishment), bankbeslag (bank-account seizure) or seizure of movable and real property. Affiliation with the Koninklijke Beroepsorganisatie van Gerechtsdeurwaarders (KBvG, the Royal Professional Organisation of Judicial Officers) is mandatory for all Dutch bailiffs.
Collection lawyers (advocaten)
For claims above €25,000, which go to the rechtbank (district court), legal representation by an advocaat is mandatory; a disputed claim of €25,000 or less stays with the kantonrechter, where no lawyer is required. Lawyers prepare the dagvaarding, represent the creditor at the hearing and can file a bankruptcy petition (faillissementsaanvraag) against a non-paying debtor.
Which laws and courts apply to debt collection in the Netherlands?
The Netherlands has a unified national civil-law system: the same courts and statutes apply across the country, with no regional or federal variation.
The civil court system
- Kantonrechter (subdistrict court, a division of the rechtbank): handles money claims up to and including €25,000, plus all employment, lease and consumer disputes regardless of value; legal representation is optional.
- Rechtbank (district court): handles civil claims above €25,000, where legal representation by an advocaat is mandatory.
- Gerechtshof (Court of Appeal) and Hoge Raad (Supreme Court): hear appeals and points of law.
Key legislation
- Burgerlijk Wetboek (the Dutch Civil Code): sets out contractual obligations, default (verzuim), statutory interest and limitation periods.
- Wetboek van Burgerlijke Rechtsvordering (the Code of Civil Procedure): governs the dagvaardingsprocedure (summons procedure) and enforcement.
- Wet kwaliteit incassodienstverlening (Wki, the Debt Collection Services Quality Act), in force since 1 April 2024: requires extrajudicial consumer-debt collectors to register in the Justis incassoregister and meet quality and conduct standards, enforced by the Inspectie Justitie en Veiligheid.
- Faillissementswet (the Bankruptcy Act): governs faillissement (bankruptcy), the WHOA scheme-of-arrangement and the WSNP personal debt-restructuring scheme.
- Algemene Verordening Gegevensbescherming (AVG, the Dutch name for the GDPR): governs handling of debtor personal data, enforced by the Autoriteit Persoonsgegevens (the Dutch Data Protection Authority).
- Nederlandse Vereniging van Incasso-ondernemingen (NVI, the Dutch Association of Debt Collection Companies): a voluntary industry body whose code of conduct sets communication and debtor-privacy standards for member agencies.
Consumer protection
Consumer debtors are protected by the 14-day reminder letter (veertiendagenbrief) requirement before extrajudicial collection costs become due, the WIK collection-cost cap (see fees below), and a lower statutory interest rate (4% versus the 10.4% commercial rate). Consumers can also raise unfair-terms or disclosure complaints with the ACM (Autoriteit Consument en Markt, the Dutch Consumer and Markets Authority).
Step 1 - How does amicable (pre-legal) debt collection work in the Netherlands?
Amicable collection starts as soon as a debtor is in default (verzuim). For claims with no agreed due date, the debtor is only in default after receiving a formal written notice of default (ingebrekestelling) giving a reasonable further period to pay. Bureau Mercuur handles this phase directly in Dutch: letters, reminders, phone calls, negotiation and, where needed, a payment plan.
What happens and when
Bureau Mercuur's standard procedure, adjusted in consultation with each client:
| When | Action |
|---|---|
| Day 0 | Claim submitted; Bureau Mercuur checks you as the client and the claim, and verifies the debtor's address and registration (land register, Chamber of Commerce, credit reports). |
| Day 1 | First collection letter by post and by email. For a consumer debtor this is the mandatory veertiendagenbrief (14-day letter), which states the exact collection costs that will be added if the debtor does not pay within 14 days. |
| Week 1-2 | A reminder after a week, followed by phone calls and text messages; a week later, a final notice warns that a bailiff will serve a summons. |
| Week 3-4 | If the debtor still does not pay or respond, Bureau Mercuur assesses the legal route and you approve a legal quote before anything escalates. |
Contact rules, letters and payment plans
A collection agency may not contact a consumer debtor by phone, electronically or in person between 20:00 and 07:00, or on Sundays and public holidays (Besluit kwaliteit incassodienstverlening, art. 4.2). Bureau Mercuur finds that a letter on the doormat gets more attention in the Netherlands than an email, so the first letter always goes by post as well.
When a debtor asks for a payment plan, Bureau Mercuur asks for half the amount upfront and the rest in instalments, and always checks the plan with you; in its experience, plans of three to six months are usually accepted. A debtor who agrees a payment plan acknowledges the debt, which makes a later dispute in court hard to sustain and restarts the limitation period (art. 3:318 BW).
Collection costs and quality standards
Every Dutch collection agency handling consumer debt must be registered in the Justis incassoregister under the Wki (see laws above). Since 1 October 2026, a debtor owes no collection costs or statutory interest on a demand from an unregistered agency. Extrajudicial collection costs are capped under the WIK scale (see fees below); the debtor must first receive the required reminder before these costs can be charged.
When to escalate
Escalation to court is never automatic. It becomes the sensible option once the debtor stops responding, repeatedly breaks a payment plan, or actively disputes the claim without basis. Before the summons, Bureau Mercuur checks the Centraal Insolventieregister (the public insolvency register), and the bailiff checks the Digitaal Beslagregister for other seizures against the debtor; if the debtor has many other debts, you decide whether a judgment is worth pursuing now. Because Bureau Mercuur is itself Justis-registered under the Wki, the same file can move from negotiation to a court-ready dossier without switching providers. Debitura sources a legal quote before any court step, so costs are known upfront.
Step 2 - How do you obtain an enforceable title in the Netherlands?
For undisputed claims up to and including €25,000, the kantonrechter (subdistrict court) handles the case through a streamlined dagvaardingsprocedure (summons procedure); legal representation is optional. A gerechtsdeurwaarder (bailiff) serves the dagvaarding on the debtor before it is filed with the court, with a minimum 7-day notice period (extended to 4 weeks if the debtor lives abroad). If the debtor does not respond, the kantonrechter typically grants a default judgment (verstekvonnis) within two weeks of the hearing.
Disputed claims and claims above €25,000
A dispute does not change the court. A claim of €25,000 or less stays with the kantonrechter whether or not the debtor disputes it (art. 93 Wetboek van Burgerlijke Rechtsvordering); a disputed claim gets a hearing or a written round, which takes longer and costs more in legal fees than an undisputed one. Claims above €25,000 go to the rechtbank (district court), where representation by an advocaat is mandatory, and the rechtbank also takes a disputed claim when the underlying contract itself is worth more than €25,000. Employment, lease, consumer-sale and consumer-credit claims stay with the kantonrechter regardless of value.
Consumer claims: what the court checks
In a claim against a consumer, the court checks of its own motion whether the contract contains unfair terms and whether the consumer received the required pre-contractual information, such as the right of withdrawal in an online or distance sale, even when the consumer does not appear (Hoge Raad, 12 November 2021). If information was missing, the court can reduce or reject the claim, so keep your terms and conditions, the order confirmation and proof that the terms were accepted in the file.
More on court proceedings in the Netherlands
The Dutch court hierarchy
- Kantonrechter (subdistrict court): a chamber of the rechtbank handling smaller claims and specific case types.
- Rechtbank (district court): the general first-instance civil court.
- Gerechtshof (Court of Appeal): hears appeals against rechtbank decisions.
- Hoge Raad (Supreme Court): the highest court, ruling on points of law only.
After judgment
A defendant can still object (verzet) to a default judgment within four weeks of being notified. Where the defendant does respond, the claimant’s written reply is due within four weeks and judgment typically follows around four weeks after the hearing. Appeal must be lodged within three months of judgment. Once final, the judgment (executoriale titel) can be handed to a gerechtsdeurwaarder for enforcement (see Step 3). Griffierecht (the court registration fee) is payable within 4 weeks of the summons being filed; for urgent matters that cannot wait for a full hearing, a kort geding (summary proceedings) can provide faster, preliminary relief.
Step 3 - How does debt enforcement work in the Netherlands?
Once a judgment is final, only a KBvG-registered gerechtsdeurwaarder (bailiff) may enforce it under the Gerechtsdeurwaarderswet (the Bailiffs Act) and the Wetboek van Burgerlijke Rechtsvordering (Code of Civil Procedure). The bailiff serves the judgment on the debtor and, if payment still does not follow, proceeds to seize assets.
Enforcement methods
| Method | What it does |
|---|---|
| Loonbeslag | Wage garnishment; a beslagvrije voet (a legally protected minimum-income floor) is always left to the debtor. |
| Bankbeslag | Seizure of funds in Dutch bank accounts; the bank notifies the debtor within 8 days of the seizure. |
| Beslag on movable or real property | Seizure of goods, vehicles or real estate, sold at a public executieverkoop (executorial sale) with proceeds going to the creditor. |
Third-party garnishment (derdenbeslag)
Loonbeslag and bankbeslag are both forms of derdenbeslag (garnishment served on a third party, such as an employer or a bank, holding money owed to the debtor); the same mechanism can reach other receivables the debtor is owed by a third party.
Costs and oversight
Bailiff fees are regulated under the Besluit tarieven ambtshandelingen gerechtsdeurwaarders (Btag) rather than freely set. The gerechtsdeurwaarder must formally serve the judgment and any seizure documents on the debtor before enforcement proceeds, and remains bound by both creditor-enforcement duties and the debtor’s statutory protections (such as the beslagvrije voet).
When enforcement finds no assets
If the gerechtsdeurwaarder cannot locate seizable assets, the case does not end automatically. The bailiff’s findings can support a decision to escalate to insolvency proceedings instead, particularly where the debtor also owes other creditors (see Step 4).
Enforcing an EU judgment, or a Dutch judgment abroad
Enforcement of foreign EU judgments in the Netherlands, and Dutch judgments elsewhere in the EU, follows Brussels I Recast (see cross-border below); no separate exequatur is required between EU member states.
Step 4 - How do insolvency procedures affect debt recovery in the Netherlands?
A Dutch debtor can be declared insolvent (failliet) once it has "ceased paying" its debts, under Article 1 of the Faillissementswet (the Bankruptcy Act); in practice, courts require the petitioner to show at least two creditors are owed money. Bankruptcy triggers a general seizure of the debtor’s assets, administered by a court-appointed curator (trustee) for the benefit of all creditors.
Order of priority
Faillissementswet distributions follow a fixed order: boedelvorderingen (estate debts, such as the curator’s own costs) are paid first, then separatisten (secured creditors, e.g. mortgage or pledge holders), then preferente (preferential claims, including the tax authority), then concurrente (ordinary unsecured creditors), and finally postconcurrente claims. An unsecured creditor’s realistic recovery depends on how much remains after the classes above it are paid.
Filing a proof of claim
Once bankruptcy is declared, creditors submit a proof of claim (vordering) to the curator with supporting documents (invoices, contracts, correspondence). The curator verifies claims and reports to a creditors’ meeting; missing the curator’s deadline risks a claim being excluded from that round of distribution. The curator convenes a verificatievergadering (claims-verification meeting) where submitted claims are checked against the debtor’s own records; a creditor whose claim the curator disputes can ask the court to rule on it. A bankruptcy can also end in a court-approved WHOA or WSNP arrangement instead of full liquidation, if the debtor qualifies.
Restructuring alternatives to liquidation
Bankruptcy is not always the end point. The WHOA (Wet Homologatie Onderhands Akkoord), in force since 1 January 2021, lets a court confirm an out-of-court restructuring plan that binds even dissenting creditors, avoiding full liquidation. For individual debtors, the WSNP (Wet Schuldsanering Natuurlijke Personen) is the personal debt-restructuring scheme: admissions from 1 July 2023 run for an 18-month term and end in a "schone lei" (clean-slate) discharge of remaining debt.
What this means for creditors
An unsecured creditor behind a Dutch insolvency should expect partial recovery at best once secured and preferential claims are paid, and none at all where the estate has no free assets. Filing the proof of claim promptly and staying engaged with the curator’s process are the only ways to influence the outcome as an unsecured creditor.
Fees, interest and who pays what in the Netherlands
- Our fee: success-based - No Cure, No Pay (see pricing).
- Court & enforcement fees: state fees apply only if the case escalates to legal action.
- Statutory debtor items: late-payment interest and recoverable collection costs are added to the debt where the law allows.
- Who keeps what: recovered principal is yours; statutory costs and interest follow local rules.
- Griffierecht (court registration fee): paid only by the party bringing the claim; see the 2026 kanton scale in the quick-answers section above.
Dutch statutory interest and collection-cost caps
- Statutory interest: 4% per annum for consumer and non-commercial debts (wettelijke rente, since 1 January 2026); 10.4% per annum for B2B and business-government contracts (wettelijke handelsrente, since 1 July 2026, reset every 1 January and 1 July).
- Extrajudicial collection costs (WIK scale): capped at 15% of the first €2,500 owed, 10% of the next €2,500, 5% of the next €5,000, 1% of the next €190,000 and 0.5% above that, with a €40 minimum and a €6,775 maximum; since 1 October 2024, small recurring consumer claims are additionally capped at €140 per 6 months.
Cross-border debt collection in the Netherlands
For creditors elsewhere in the EU pursuing a Dutch debtor, two EU cross-border procedures avoid a full Dutch court case: the European Small Claims Procedure (Regulation (EC) No 861/2007), available for claims up to €5,000, and the European Order for Payment (Regulation (EC) No 1896/2006), available for uncontested claims above €2,000, for which the District Court of The Hague is the sole competent Dutch court.
Once a Dutch judgment exists, Brussels I Recast (Regulation (EU) No 1215/2012) lets it be enforced directly in any other EU member state without an exequatur (a separate declaration of enforceability), and the same applies in reverse for a foreign EU judgment being enforced against a Dutch debtor.
Judgments from outside the EU
A judgment from a country outside the EU cannot be enforced directly in the Netherlands unless a treaty provides for it. Without a treaty, the creditor starts new proceedings before a Dutch court, which can adopt the foreign ruling if the conditions for recognition are met (art. 431 Wetboek van Burgerlijke Rechtsvordering). As of October 2026, the 2019 Hague Judgments Convention applies between the Netherlands and the United Kingdom, Ukraine, Uruguay, Albania, Montenegro and Andorra, and a judgment from Switzerland, Norway or Iceland first needs a declaration of enforceability under the Lugano Convention.
Partners in our network
These firms are partners in our network for this country. Open a profile to learn more about each one. If court action is needed on your case, your partner sends a quote on the platform; nothing starts until you accept it.
- Verified specialists
- Nothing starts until you accept the quote
- Fair, pre-negotiated rates
Russell Advocaten B.V. is a premier law firm in Amsterdam offering effective Debt Collection services in the Netherlands, established in 1943 and renowned for its Legal 500 recommendations, Primerus membership, and global reach through partner firms in over 40 countries.


Ansbertus Law Firm is a premier law firm in Amsterdam offering effective Debt Collection services in the Netherlands, established in 2005, and recognized for its membership in the Mediators Federatie Nederland and the Nederlandse Beroepsorganisatie van Accountants.
Mr. Berendsen Advocaten is a premier law firm in Amsterdam-Duivendrecht offering effective Debt Collection services in The Netherlands, established in 2006, known for its client-oriented approach and recognized by multiple awards, with memberships in prominent legal associations.
Bureau Mercuur is a debt collection agency in Groningen, founded in 1908, registered in the Justis incassoregister (no. 00027) and holding the NVI Incasso Keurmerk. As a Debitura partner in the Netherlands, it works under Debitura's standard terms and No Cure, No Pay pricing.
ACCS International is a premier international debt recovery agency offering effective Debt Collection services. Established in 2000, with ISO certifications and global memberships, as a Debitura partner offering No Cure No Pay collection based on Debitura’s No Cure, No Pay standard terms and pricing
CW & Partners Cash-Flow Management BV is a premier debt recovery agency in Loosdrecht offering effective Debt Collection services in the Netherlands, founded in 2011, operating on a no-cure, no-pay basis, and serving international markets with esteemed memberships.
Montclare Capital Partners is an international business consulting and legal–fiscal advisory firm headquartered in Amsterdam. We are not solely a law firm. Our work spans the Benelux region, Central Europe, East Europe, Switzerland, and Spain, supporting clients with cross-border debt recovery, commercial disputes, international tax structuring, and strategic business advisory. Montclare’s strength lies in combining legal clarity with multi-jurisdiction coordination, offering efficient and fully compliant solutions for companies operating across interconnected European markets.

Totaal Incasso B.V. is a premier debt recovery agency in Haarlem offering effective Debt Collection services in the Netherlands, positioning itself as the go-to partner for debt recovery with Kifid membership, a foundation in 2023, and worldwide service capabilities.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.