Debt Collection Agency in France: No Win, No Fee
Need a debt collection agency in France? Your claim goes to Cabinet d’Ormane, France’s licensed collection specialist (cabinet de recouvrement de créances), on a No Cure, No Pay basis with zero upfront cost. Submit your claim in minutes and track progress in real time through Debitura’s platform.


Questions about your case?
Write to us, we reply by email.

Why Debitura in France
Start recovering your France claims in 2 minutes
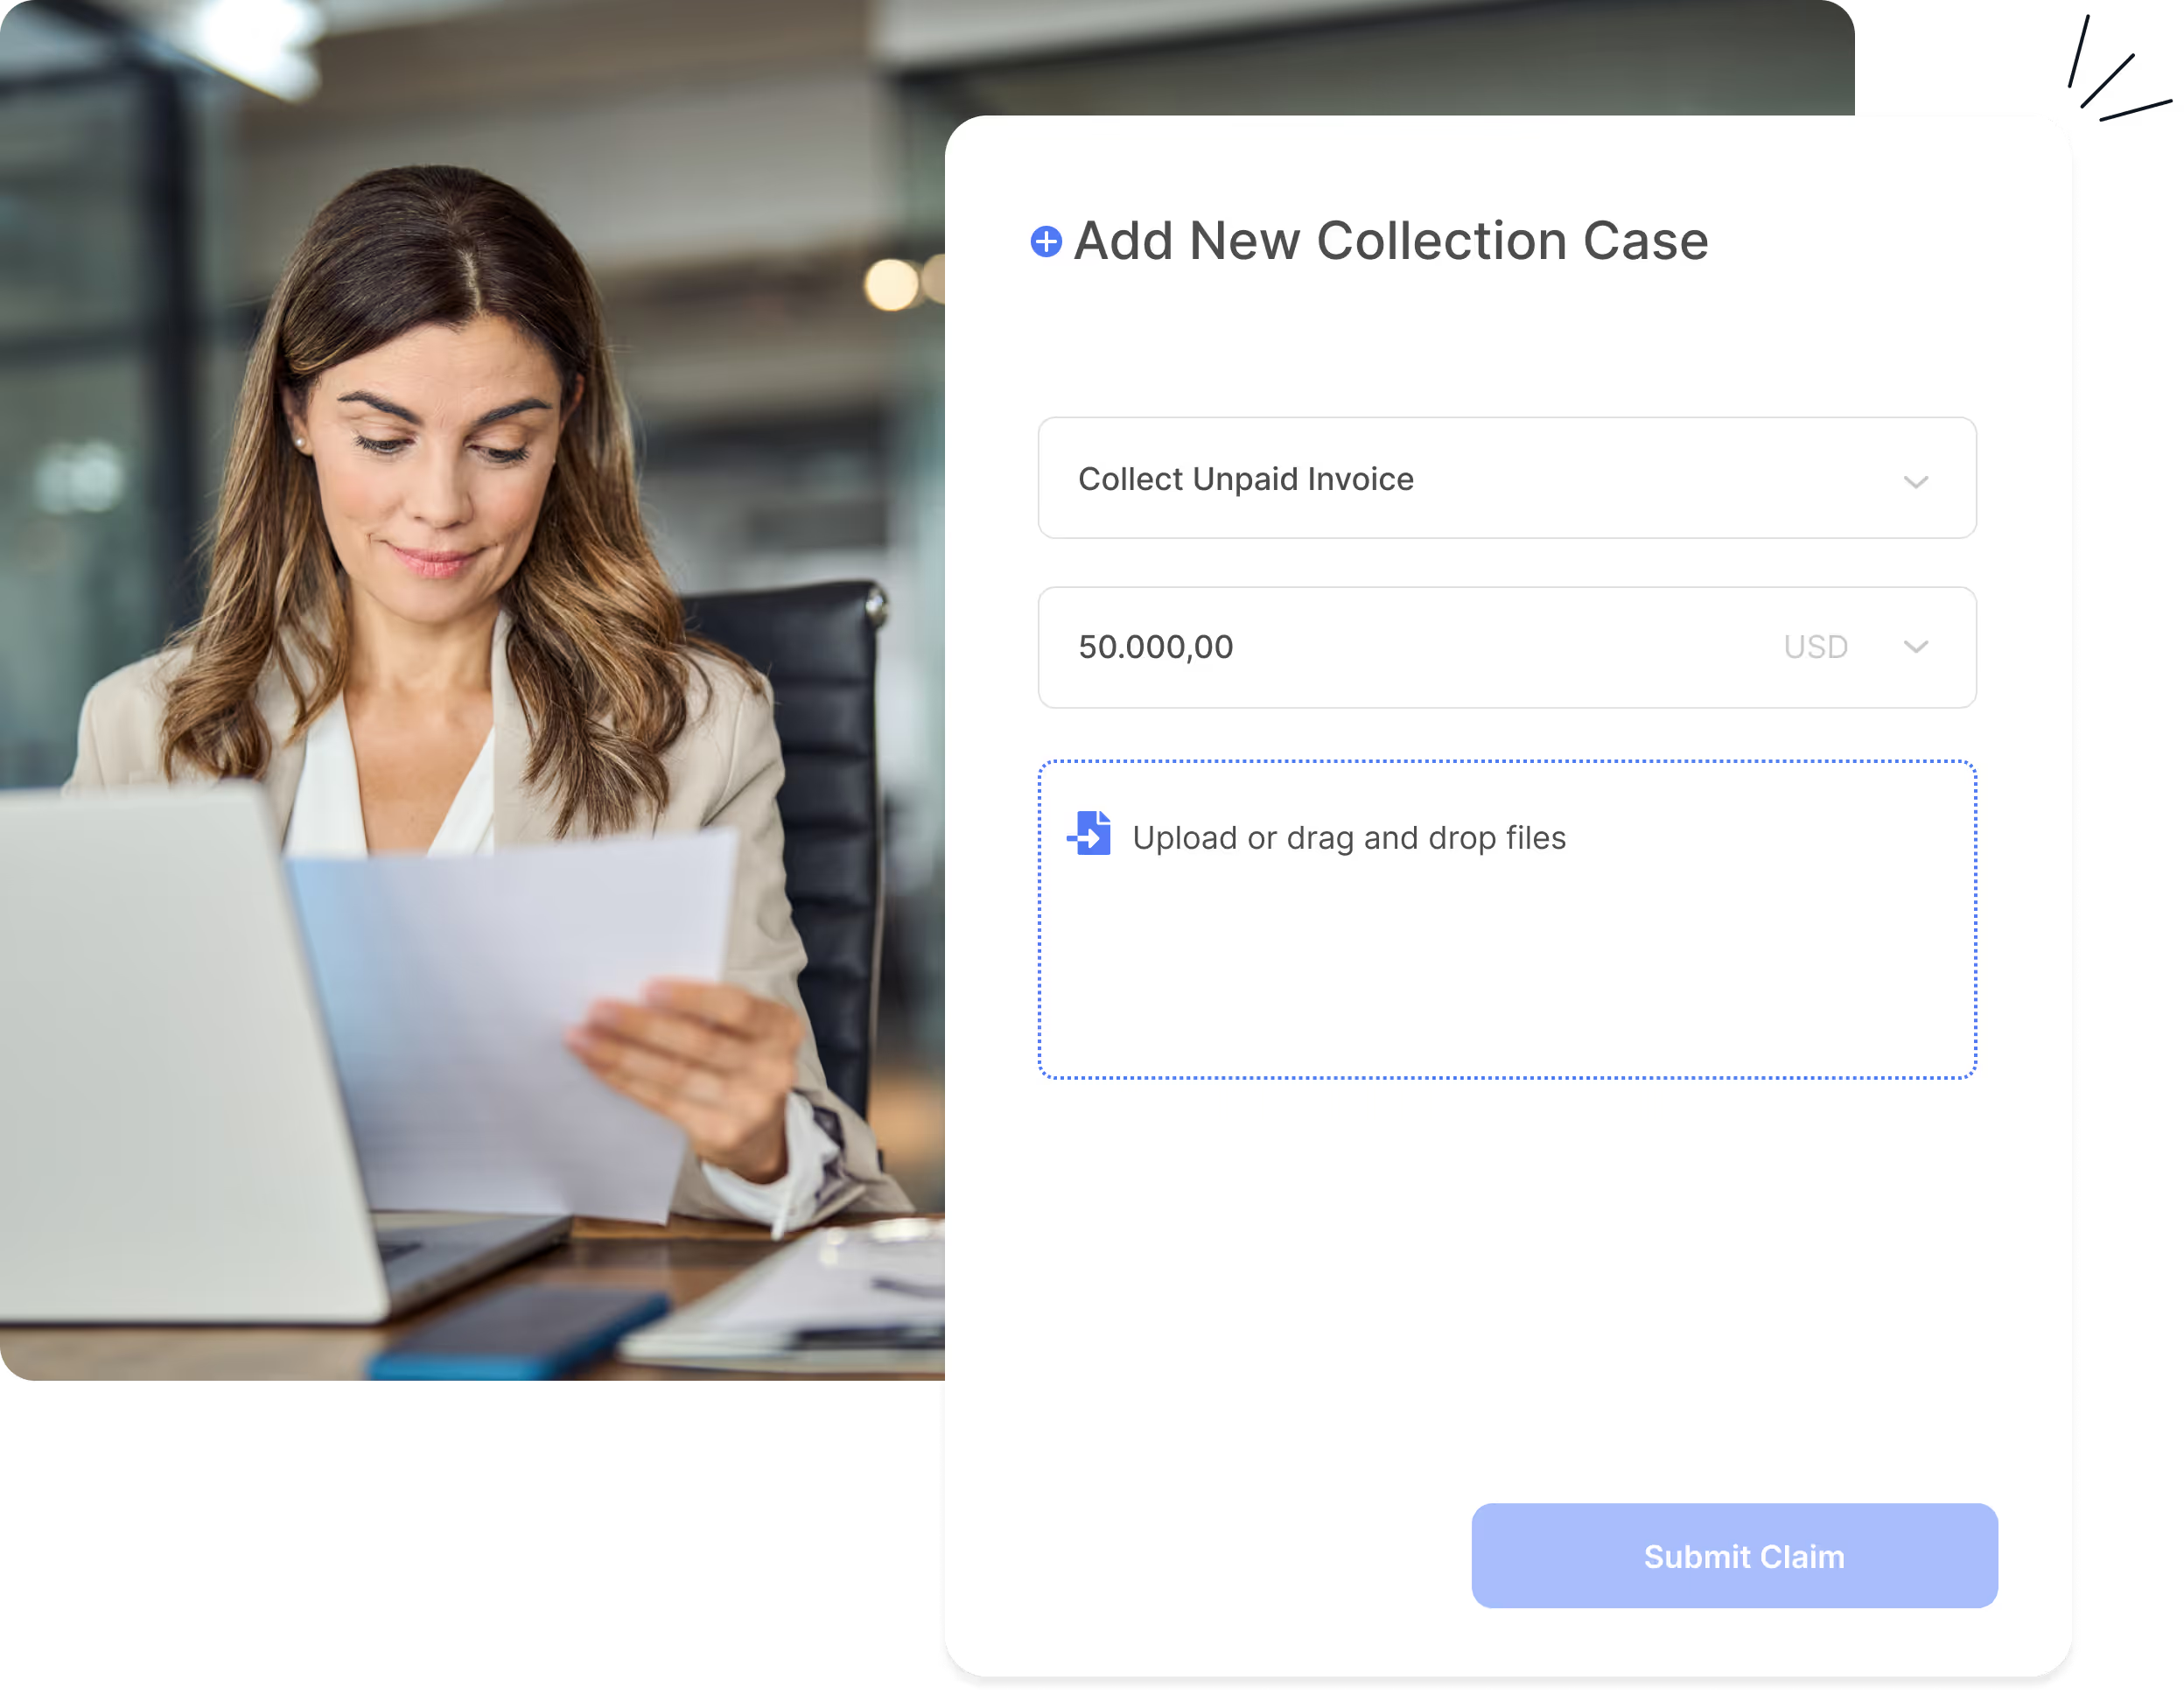
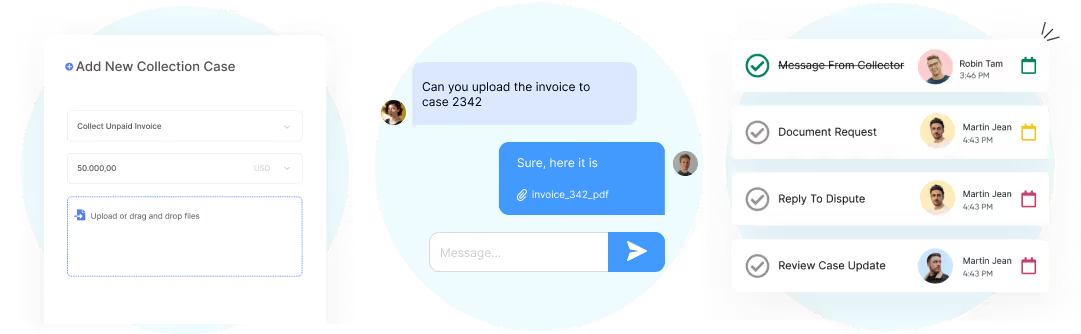
- Submit your claim: upload in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- Local collection begins: Cabinet d'Ormane contacts the debtor in French, opening the recouvrement amiable (amicable collection) process. Debitura partners must resolve open tasks and respond to client inquiries within 48 business hours.
- Get paid: funds are remitted once recovered. If needed, optional legal escalation follows the injonction de payer (payment order) procedure, always with a legal quote you approve first.
Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12–24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in France?
Debt collection in France runs in two stages. First comes amicable collection: a reminder and a formal demand (mise en demeure). If the debtor does not pay, the creditor can ask a court for an injonction de payer, an order for payment issued without a hearing. Claims are generally time-barred after 5 years (Code civil art. 2224), or 2 years against a consumer (Code de la consommation art. L218-2). Through Debitura, Cabinet d'Ormane in Paris handles the amicable stage.
- Formal demand. A reminder, then a mise en demeure that names the creditor, the amount and how to pay (CPCE arts. R124-1 to R124-7).
- Order for payment. The creditor applies for an injonction de payer: free at the tribunal judiciaire, EUR 30.23 at the commercial court (Infogreffe tariff).
- Service and opposition. The order must be served within 3 months for orders issued from 1 September 2026 (Code de procédure civile art. 1411); the debtor then has 1 month to oppose (art. 1416).
- Enforcement. An unopposed order becomes enforceable, and a commissaire de justice can enforce it, for example by bank garnishment (saisie-attribution).
- Submit your claim in 2 minutes online
- Local, licensed action from day one
- No Cure, No Pay, you owe nothing until we recover
- You approve every escalation, nothing happens without you
- Get paid directly when funds are recovered
The four steps from unpaid invoice to recovered cash
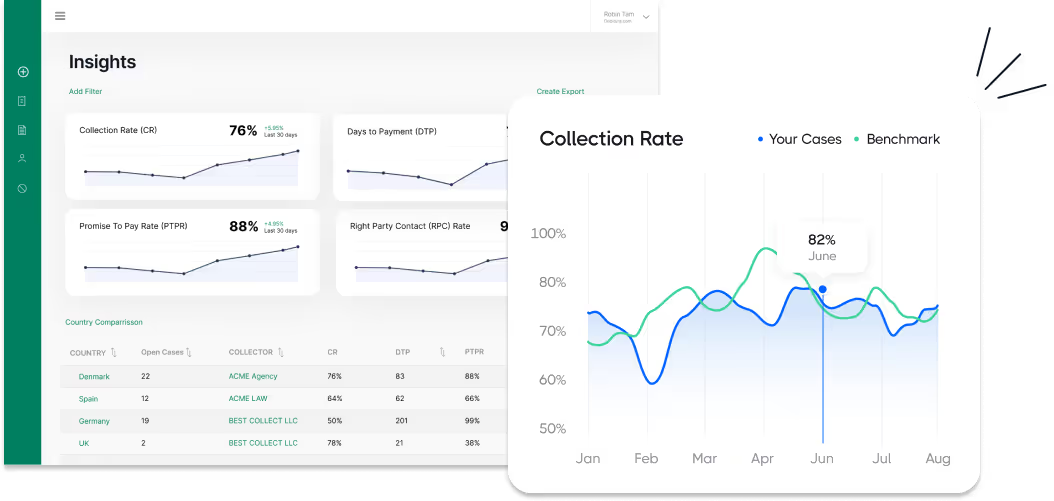
- Amicable collection: a reminder and a formal demand, handled locally by Cabinet d'Ormane. Most undisputed claims resolve here, without going to court.
- Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title, and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with an enforceable title, the enforcement authority can freeze bank accounts, garnish wages, and seize and sell assets until the claim is recovered.
- Insolvency: if the debtor cannot pay, your proof of claim is filed in the collective insolvency procedure, and any distribution is monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for France follows in the guide below.
Debt collection in France - the complete 2026 guide
This Debt Collection France guide is built for creditors, in-house counsel and finance teams collecting from debtors in France. It covers the laws and courts, who does what, the amicable phase, the injonction de payer (the payment order procedure) route to an enforceable title, enforcement by the commissaire de justice (the judicial officer), insolvency, and cross-border recovery.
On this page:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).
Contributing local experts:
Last updated:

Debt collection in France - quick answers
Debt Collection France runs on a fast, largely paper-based order-for-payment route, a simplified small-claims track run by the commissaire de justice (the judicial officer, formerly huissier de justice), and EU-based late-payment protection for businesses.
How much does debt collection cost in France?
Pre-legal collection in France is commonly success-based, No Cure, No Pay, and escalating to the injonction de payer costs a fixed 30.23 euro registry fee before the tribunal de commerce (the Commercial Court, or the tribunal des activités économiques in the 12 courts piloting that structure) for a commercial claim; filing is free at the tribunal judiciaire for a civil claim. A court can also order the debtor to bear the creditor's costs, including a contribution to legal fees under article 700 of the Code de procédure civile. For a B2B debt, a fixed 40 euro recovery indemnity is added automatically, and further justified recovery costs above that amount can also be claimed if the creditor can show them. Charging any recovery cost to a consumer debtor, by contrast, is a criminal offense in France.
How long does debt collection take in France?
An uncontested injonction de payer is decided on the file without a hearing, and the debtor then has one month from service to lodge opposition. Since a February 2026 reform, the creditor must now serve the order within three months of its date, down from six, or it lapses; if no opposition arrives within two months of service, the creditor can move straight to forced execution. Where the debt is genuinely disputed, an ordinary lawsuit (assignation en paiement) before the tribunal judiciaire takes longer, and a référé-provision can secure an interim payment faster where the debt is not seriously contestable.
What are the limitation periods and interest rules in France?
The general limitation period for a commercial or civil debt is five years from the date the creditor knew or should have known the facts allowing the claim (Code civil, the Civil Code, article 2224); a professional's claim against a consumer for goods or services supplied is shorter, at two years (Code de la consommation, the Consumer Code, article L218-2). Late-payment interest runs at the statutory rate (taux d'intérêt légal), reset every six months: for the second half of 2026 it is 2.75% for a professional debtor and 6.84% for an individual. Between two businesses, the contract can instead set its own late-payment rate, provided it is at least three times the statutory rate, or the interest defaults to the European Central Bank's main refinancing rate plus 10 points. Contractual payment terms are capped at 30 days from receipt of the goods or services, or 60 days from the invoice date if both parties agree. On top of interest, a business debtor automatically owes a fixed 40 euro recovery indemnity (Code de commerce, article L441-10); this indemnity, like the penalty rate itself, never applies against a consumer debtor.
| Topic | Rule |
|---|---|
| General limitation | 5 years from the due date (Code civil art. 2224). |
| Consumer (B2C) limitation | 2 years for a professional's claim against a consumer (Code de la consommation art. L218-2). |
| Late-payment interest, H2 2026 | 2.75% professional debtor / 6.84% individual debtor, reset every six months. |
| B2B recovery indemnity | Fixed EUR 40, automatic, B2B/B2G only (Code de commerce art. L441-10). |
| Commercial-route filing fee | EUR 30.23 registry fee (injonction de payer, tribunal de commerce/TAE). |
What documents do I need to collect a debt in France?
Keep the contract or purchase order, the invoices and statement of account, proof of delivery or performance, and all correspondence with the debtor. The injonction de payer is started by a written application (requête) supported by this evidence, with no hearing required, so a complete and well-organised file speeds up the decision.
Which route should my claim take in France?
A fixed, contractual money debt suits the injonction de payer (the payment order procedure). A claim of no more than 5,000 euro against a consumer or a mixed debtor can instead go through the simplified small-claims recovery run directly by a commissaire de justice, with no judge involved, though this route excludes an invoiced claim between two merchants. Where the debt is not seriously contestable but money is needed quickly, a référé-provision can secure an interim payment after a short hearing. A genuinely disputed claim goes to an ordinary lawsuit (assignation en paiement) before the tribunal judiciaire, and a cross-border EU claim can use the European Payment Order instead.
Who does what in France debt collection?
A Debt Collection Agency France engagement typically combines amicable recovery, the courts for an enforceable title, and the commissaire de justice (the judicial officer) for enforcement. Debitura connects you to all three stages through Cabinet d'Ormane, a licensed Paris-based partner.
Collection agencies in France
Amicable recovery can be run in-house or by a recovery company (société de recouvrement, a debt collection agency), regulated under the Code des procédures civiles d'exécution (the Code of Civil Enforcement Procedures), articles R124-1 to R124-7: mandatory professional-liability insurance, a dedicated client account, a written creditor agreement, and prescribed content in the debtor letter. Agencies are also subject to oversight by the DGCCRF (the consumer-protection and market-oversight authority), which can inspect compliance with these rules and enforces the criminal penalty for billing recovery costs to a consumer debtor. Fees for amicable work stay with the creditor and are never billed to the debtor unless the law or a court allows it. A commissaire de justice can also run amicable recovery and the simplified small-claims track described below.
The commissaire de justice
The commissaire de justice is the single bailiff profession created on 1 July 2022 by merging the former huissier de justice (process server) and commissaire-priseur judiciaire (judicial auctioneer). The commissaire serves court documents, runs the simplified small-claims recovery for debts up to 5,000 euro, and enforces titres exécutoires (enforceable titles) through bank attachment, wage garnishment and asset seizure.
Lawyers in France
A lawyer (avocat) is not required to file an injonction de payer. Above a certain claim value, instructing an avocat before the tribunal judiciaire becomes mandatory once the debtor opposes and the case goes to an ordinary hearing; below that threshold, a party can represent itself. Debitura's advantage: Cabinet d'Ormane assesses the dispute and coordinates any required lawyer instruction, so you never have to find and vet French counsel yourself.
Which laws and courts apply to debt collection in France?
French debt recovery runs on the Code de procédure civile (the Code of Civil Procedure) and the Code civil (the Civil Code), with a dedicated enforcement code and EU instruments layered on top for cross-border claims.
The civil court system in France
Money claims go to the tribunal judiciaire (the ordinary civil court), which has handled all first-instance civil and commercial claims nationally since 1 January 2020, when it was created by merging the former tribunal d'instance and tribunal de grande instance. A commercial claim between traders instead goes to the tribunal de commerce (the Commercial Court); in Alsace-Moselle, which has no tribunal de commerce, the commercial chamber of the tribunal judiciaire hears these cases. Twelve courts, including Paris, are piloting a replacement structure, the tribunal des activités économiques, from 2025 to 2028, with jurisdiction extended to agricultural operators, non-regulated liberal professions and civil associations. For a claim of 5,000 euro or less, the juge des contentieux de la protection (the consumer and protection judge) decides with no right of appeal.
Key legislation in France
- Code de procédure civile (the Code of Civil Procedure): the injonction de payer, articles 1405 to 1425, with the service and forced-execution rules at articles 1411 and 1422 reformed in February 2026.
- Code des procédures civiles d'exécution (the Code of Civil Enforcement Procedures): amicable-collection regulation, articles R124-1 to R124-7, the simplified small-claims recovery, article L125-1, and a new business-to-business streamlined procedure, articles L126-1 to L126-6, enacted April 2026 but not yet operational.
- Code civil (the Civil Code): the general five-year limitation, article 2224.
- Code de la consommation (the Consumer Code): the shorter two-year limitation on a professional's claim against a consumer, article L218-2.
- Code de commerce (the Commercial Code): B2B late-payment penalties, article L441-10, and the insolvency procedures of Book VI.
Conduct and data protection in France
Amicable collection agencies must carry professional-liability insurance and hold client funds in a dedicated account under the Code des procédures civiles d'exécution, and breaching the prescribed debtor-letter rules is punishable by a fifth-class fine. The DGCCRF (the consumer-protection authority) enforces a criminal penalty, up to two years' imprisonment and a 300,000 euro fine, against anyone who bills recovery costs to a consumer debtor outside narrow legal exceptions. A debtor's personal data must be handled under the EU General Data Protection Regulation, supervised in France by the CNIL (the National Commission for Information Technology and Civil Liberties).
Step 1 - How does amicable (pre-legal) debt collection work in France?
Amicable collection recovers an unpaid invoice without a lawsuit, through a reminder (relance) and, if that fails, a formal demand (mise en demeure). Neither step is legally required before suing, but the mise en demeure formally puts the debtor in default and triggers late-payment interest. The aim is full payment or a written acknowledgement of the debt, which can support a later claim if the debtor does not pay as promised.
| Stage | Action |
|---|---|
| Reminder (relance) | Invoice, due date and payment details restated to the debtor. |
| Formal demand (mise en demeure) | By registered letter, by a commissaire de justice, or as set out in the contract. |
| Negotiation | Settlement or an instalment plan, ideally acknowledged by the debtor in writing. |
| Escalation | File an injonction de payer, or a lawsuit if the claim is disputed. |
Making a valid formal demand in France
Under the Code civil (the Civil Code), articles 1344 to 1345-3, a mise en demeure can be made in three ways: a sommation served by a commissaire de justice, a registered letter with acknowledgement of receipt (lettre recommandée avec accusé de réception) containing a sufficient formal demand, or a clause written into the contract itself. It puts the debtor formally in default and supports the creditor's claim for late-payment interest from that date.
Who bears the cost, B2B versus B2C
Between two businesses, a fixed 40 euro recovery indemnity applies automatically from day one of late payment, on top of statutory or contractual interest (Code de commerce, article L441-10 and D.441-5); no notice is required and the amount cumulates across invoices. Against a consumer debtor, the position reverses entirely: billing any recovery cost to a consumer is a criminal offense under French law, so amicable costs stay with the creditor except in narrow, legally defined cases.
When to escalate
Cabinet d'Ormane moves to escalation only with your approval. If the debtor still does not respond within a reasonable period after the mise en demeure, or disputes the debt without paying, the next step is either the injonction de payer for an undisputed fixed debt, or an ordinary lawsuit where the claim is genuinely contested.
Step 2 - How do you obtain an enforceable title in France?
To enforce a debt you need an enforceable title (titre exécutoire). France's fast route is the injonction de payer (the payment order procedure), with a simplified small-claims track and ordinary proceedings as alternatives.
The order-for-payment procedure (injonction de payer)
The creditor files a written application (requête) with the competent court. The procedure is non-adversarial: there is no hearing, and the judge decides on the file alone. It applies to a fixed claim of contractual or statutory origin, but not to maintenance payments or a bounced cheque. A commercial-route application carries a 30.23 euro registry fee; the civil route at the tribunal judiciaire is free. If granted, the order carries the enforcement formula (formule exécutoire) and becomes an enforceable title once served and unopposed.
Service and opposition
Since a February 2026 reform, the order must be served on the debtor within three months of its date, down from six previously, or it becomes non avenue (void). The debtor then has one month from service to lodge opposition (opposition), unchanged by the reform, which sends the whole claim to an ordinary hearing. If no opposition is received within two months of service, the creditor can proceed straight to forced execution. A rejected application is not open to appeal, but the creditor can still bring an ordinary lawsuit instead.
Determining the appropriate court in France
The competent court is generally the one where the debtor lives or has its registered office. For a civil claim this is the tribunal judiciaire; for a commercial claim between traders, the tribunal de commerce (or, in 12 pilot courts including Paris, the tribunal des activités économiques, piloting a wider commercial-court jurisdiction from 2025 to 2028); in Alsace-Moselle, the commercial chamber of the tribunal judiciaire.
More on court proceedings in France
Simplified small-claims recovery and référé-provision
For a debt of 5,000 euro or less, a commissaire de justice can run the simplified small-claims recovery directly, with no judge involved: the debtor has one month to accept or refuse, silence counts as refusal, and on agreement the commissaire issues an enforceable title straight away (Code des procédures civiles d'exécution, article L125-1). This route excludes an invoiced claim between two merchants. Where money is needed quickly and the debt is not seriously contestable, a référé-provision can instead secure an interim payment after a short hearing.
A new business-to-business route, not yet usable
A 2026 statute (the "procédure de recouvrement des créances commerciales incontestées") creates a dedicated B2B route: a commissaire de justice serves a formal payment demand, and if the debtor neither pays nor contests it, the court clerk appends an enforcement formula after a purely formal check, with all costs shifting to the debtor. Its implementing decree was not yet published at the time of writing, so it is not yet usable.
Step 3 - How does debt enforcement work in France?
Enforcement of a titre exécutoire (an enforceable title) is carried out by a commissaire de justice (the judicial officer, formed from the 2022 merger of the huissier de justice and the commissaire-priseur judiciaire). The creditor chooses the measures that match the debtor's known assets, and the commissaire can be asked to investigate what the debtor owns before enforcement starts.
Ways to enforce a claim in France
- Bank attachment (saisie-attribution): the commissaire de justice seizes funds the debtor holds with a third party such as a bank, above a protected minimum pegged to the RSA (the minimum-income benefit) level; the debtor has one month to contest the seizure before the juge de l'exécution (the enforcement judge), after which the bank releases the funds to the creditor.
- Wage garnishment (saisie des rémunérations): de-judicialised to the commissaire de justice as of 1 July 2025 (previously run by the court); the commissaire notifies the debtor's employer and attaches wages above the legally protected minimum, in monthly instalments.
- Seizure and sale of movables (saisie-vente): the commissaire de justice seizes and sells the debtor's movable property, such as vehicles or equipment, at auction.
- Immovable property (saisie immobilière): for larger claims, real estate can be seized and sold under judicial supervision, a longer and more formal process reserved for significant debts.
The enforcement process in France
The creditor instructs the commissaire de justice with the enforceable title; the commissaire identifies the debtor's assets, chooses and applies the appropriate measure, and collects the funds. Proceeds are applied first to principal, then interest, then recoverable costs, with any surplus returned to the debtor. If a first measure recovers only part of the debt, the creditor can instruct further measures against any other assets the commissaire identifies, until the claim is satisfied or no further assets can be found.
Step 4 - How do insolvency procedures affect debt recovery in France?
Where the debtor cannot meet its obligations, a collective insolvency procedure (procédure collective) becomes the route, and individual enforcement generally stops once it opens. France has three: sauvegarde (safeguard, opened before the debtor stops paying its debts, aimed at reorganising while still solvent), redressement judiciaire (judicial reorganisation, once the debtor is in cessation des paiements but recovery is still considered possible), and liquidation judiciaire (judicial liquidation, where recovery is no longer possible and the business winds up and its assets are sold).
When insolvency opens
Cessation des paiements (the French insolvency trigger, Code de commerce article L631-1) means the debtor's available assets, cash, bank balances, sight instruments and undrawn credit lines, can no longer cover its due and payable liabilities. There is no minimum debt threshold: it is a liquidity test, not a debt-size floor, unlike common-law statutory-demand systems. A debtor must file for redressement or liquidation judiciaire within 45 days of reaching this point (Code de commerce, article L631-4); filing late can expose the debtor's managers to personal liability. Traders and artisans file with the tribunal de commerce, or, in the 12 courts piloting the tribunal des activités économiques from 2025 to 2028, that court instead; the pilot also extends to agricultural operators, non-regulated liberal professions and civil associations, a wider pool than the traditional trader/artisan base.
Filing your proof of claim
An unsecured creditor must file a proof of claim (déclaration de créance) with the court-appointed mandataire judiciaire (the insolvency practitioner representing creditors) within two months of the opening judgment being published in the BODACC (the official register of commercial announcements), extended to four months for a creditor based outside mainland France. The claim should state the amount owed, its legal basis, and attach supporting documents.
Missing the deadline
A creditor who misses the filing deadline is barred (forclos) from the distribution and goes unpaid, unless not at fault: a request to be relieved from the bar (relevé de forclusion) can be filed with the juge-commissaire (the supervising judge) within six months of the BODACC publication, with the claim itself then declared within one month of a favourable decision.
Priority and likely outcomes
Employees' wages are guaranteed and paid first through the AGS wage-guarantee scheme, ahead of procedure costs and other creditors; secured creditors and the state generally rank ahead of ordinary unsecured trade creditors, who are often paid only pro rata from whatever remains once higher-ranked claims are satisfied. Lodge your claim on time, with the contract, invoices and statement of account, and monitor the verification of claims through your partner and the mandataire judiciaire.
Fees, interest and who pays what in France
- Our fee: success-based, No Cure, No Pay (see pricing).
- Court and enforcement fees: statutory court and enforcement fees, such as the 30.23 euro injonction de payer registry fee on the commercial route and the commissaire de justice's enforcement costs, apply only if the case escalates to legal action, and are generally recoverable from the debtor if you win, including a contribution to legal costs under article 700 of the Code de procédure civile.
- Statutory debtor items: for a business debt, late-payment interest runs at the statutory rate (taux d'intérêt légal, reset every six months; 2.75% for a professional debtor in the second half of 2026), or at a contractual rate if one is agreed and it is at least three times the statutory rate. On top of interest, a fixed 40 euro recovery indemnity applies automatically from the day after the due date (Code de commerce, article L441-10), and further justified recovery costs above 40 euro can also be claimed if the creditor documents them. None of these B2B costs can be billed to a consumer debtor.
- Who keeps what: the recovered principal is yours; interest and statutory costs follow the contract, the statute and the court's order.
Cross-border debt collection in France
France is a founding European Union member state, so for a claim against a debtor in another EU country, three EU instruments apply directly, without extra formalities. The European Payment Order (Regulation EC 1896/2006) gives a uniform order-for-payment route for an uncontested cross-border claim: filed on a standard form, it is typically decided within 30 days, and the debtor then has 30 days to oppose it before it becomes automatically enforceable. The European Small Claims Procedure (Regulation EC 861/2007) is a simplified written procedure for a cross-border claim of no more than 5,000 euro, available in every EU state except Denmark, and is open to a French creditor pursuing a debtor elsewhere in the EU or vice versa. A French judgment is recognised and enforced in another EU member state under the Brussels I Recast Regulation (EU 1215/2012): exequatur is abolished, so no separate declaration of enforceability is needed, only a standard certificate.
Partners in our network
These firms are partners in our network for this country. Open a profile to learn more about each one. If court action is needed on your case, your partner sends a quote on the platform; nothing starts until you accept it.
- Verified specialists
- Nothing starts until you accept the quote
- Fair, pre-negotiated rates
MERCURE Finances is a premier debt recovery agency in Montrouge offering effective Debt Collection services in France, founded in 2003, operating on a success-based fee model, and recognized with awards and memberships including FENCA, serving over 104 countries according to the agency.


Cabinet FRANC is a premier law firm in Paris offering effective Debt Collection services in France, established in 1991, with international expertise across Europe and North America, and memberships in the Barreau de Paris and Barreau de Bruxelles.
Cabinet d'Ormane is a premier debt recovery agency in France offering effective Debt Collection services, established in 1956, and renowned for its No Cure No Pay model; as a Debitura partner, it serves clients across France and internationally.
Gayssot Recouvrement is a premier debt recovery agency in Lyon offering effective Debt Collection services in France, positioning itself as the go-to partner for debt recovery since 2014, with a focus on transparency and efficiency, and a member of the United Nations Global Compact.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.