B2B Debt Collection Agency in Canada: No Win, No Fee
Need a debt collection agency in Canada? For unpaid invoices from business customers in Canada, we match your case to a licensed local partner under one contract. You pay only when money is recovered.


Questions about your case?
Write to us, we reply by email.

Why choose Debitura for debt collection in Canada
Start recovering your claims in Canada in minutes
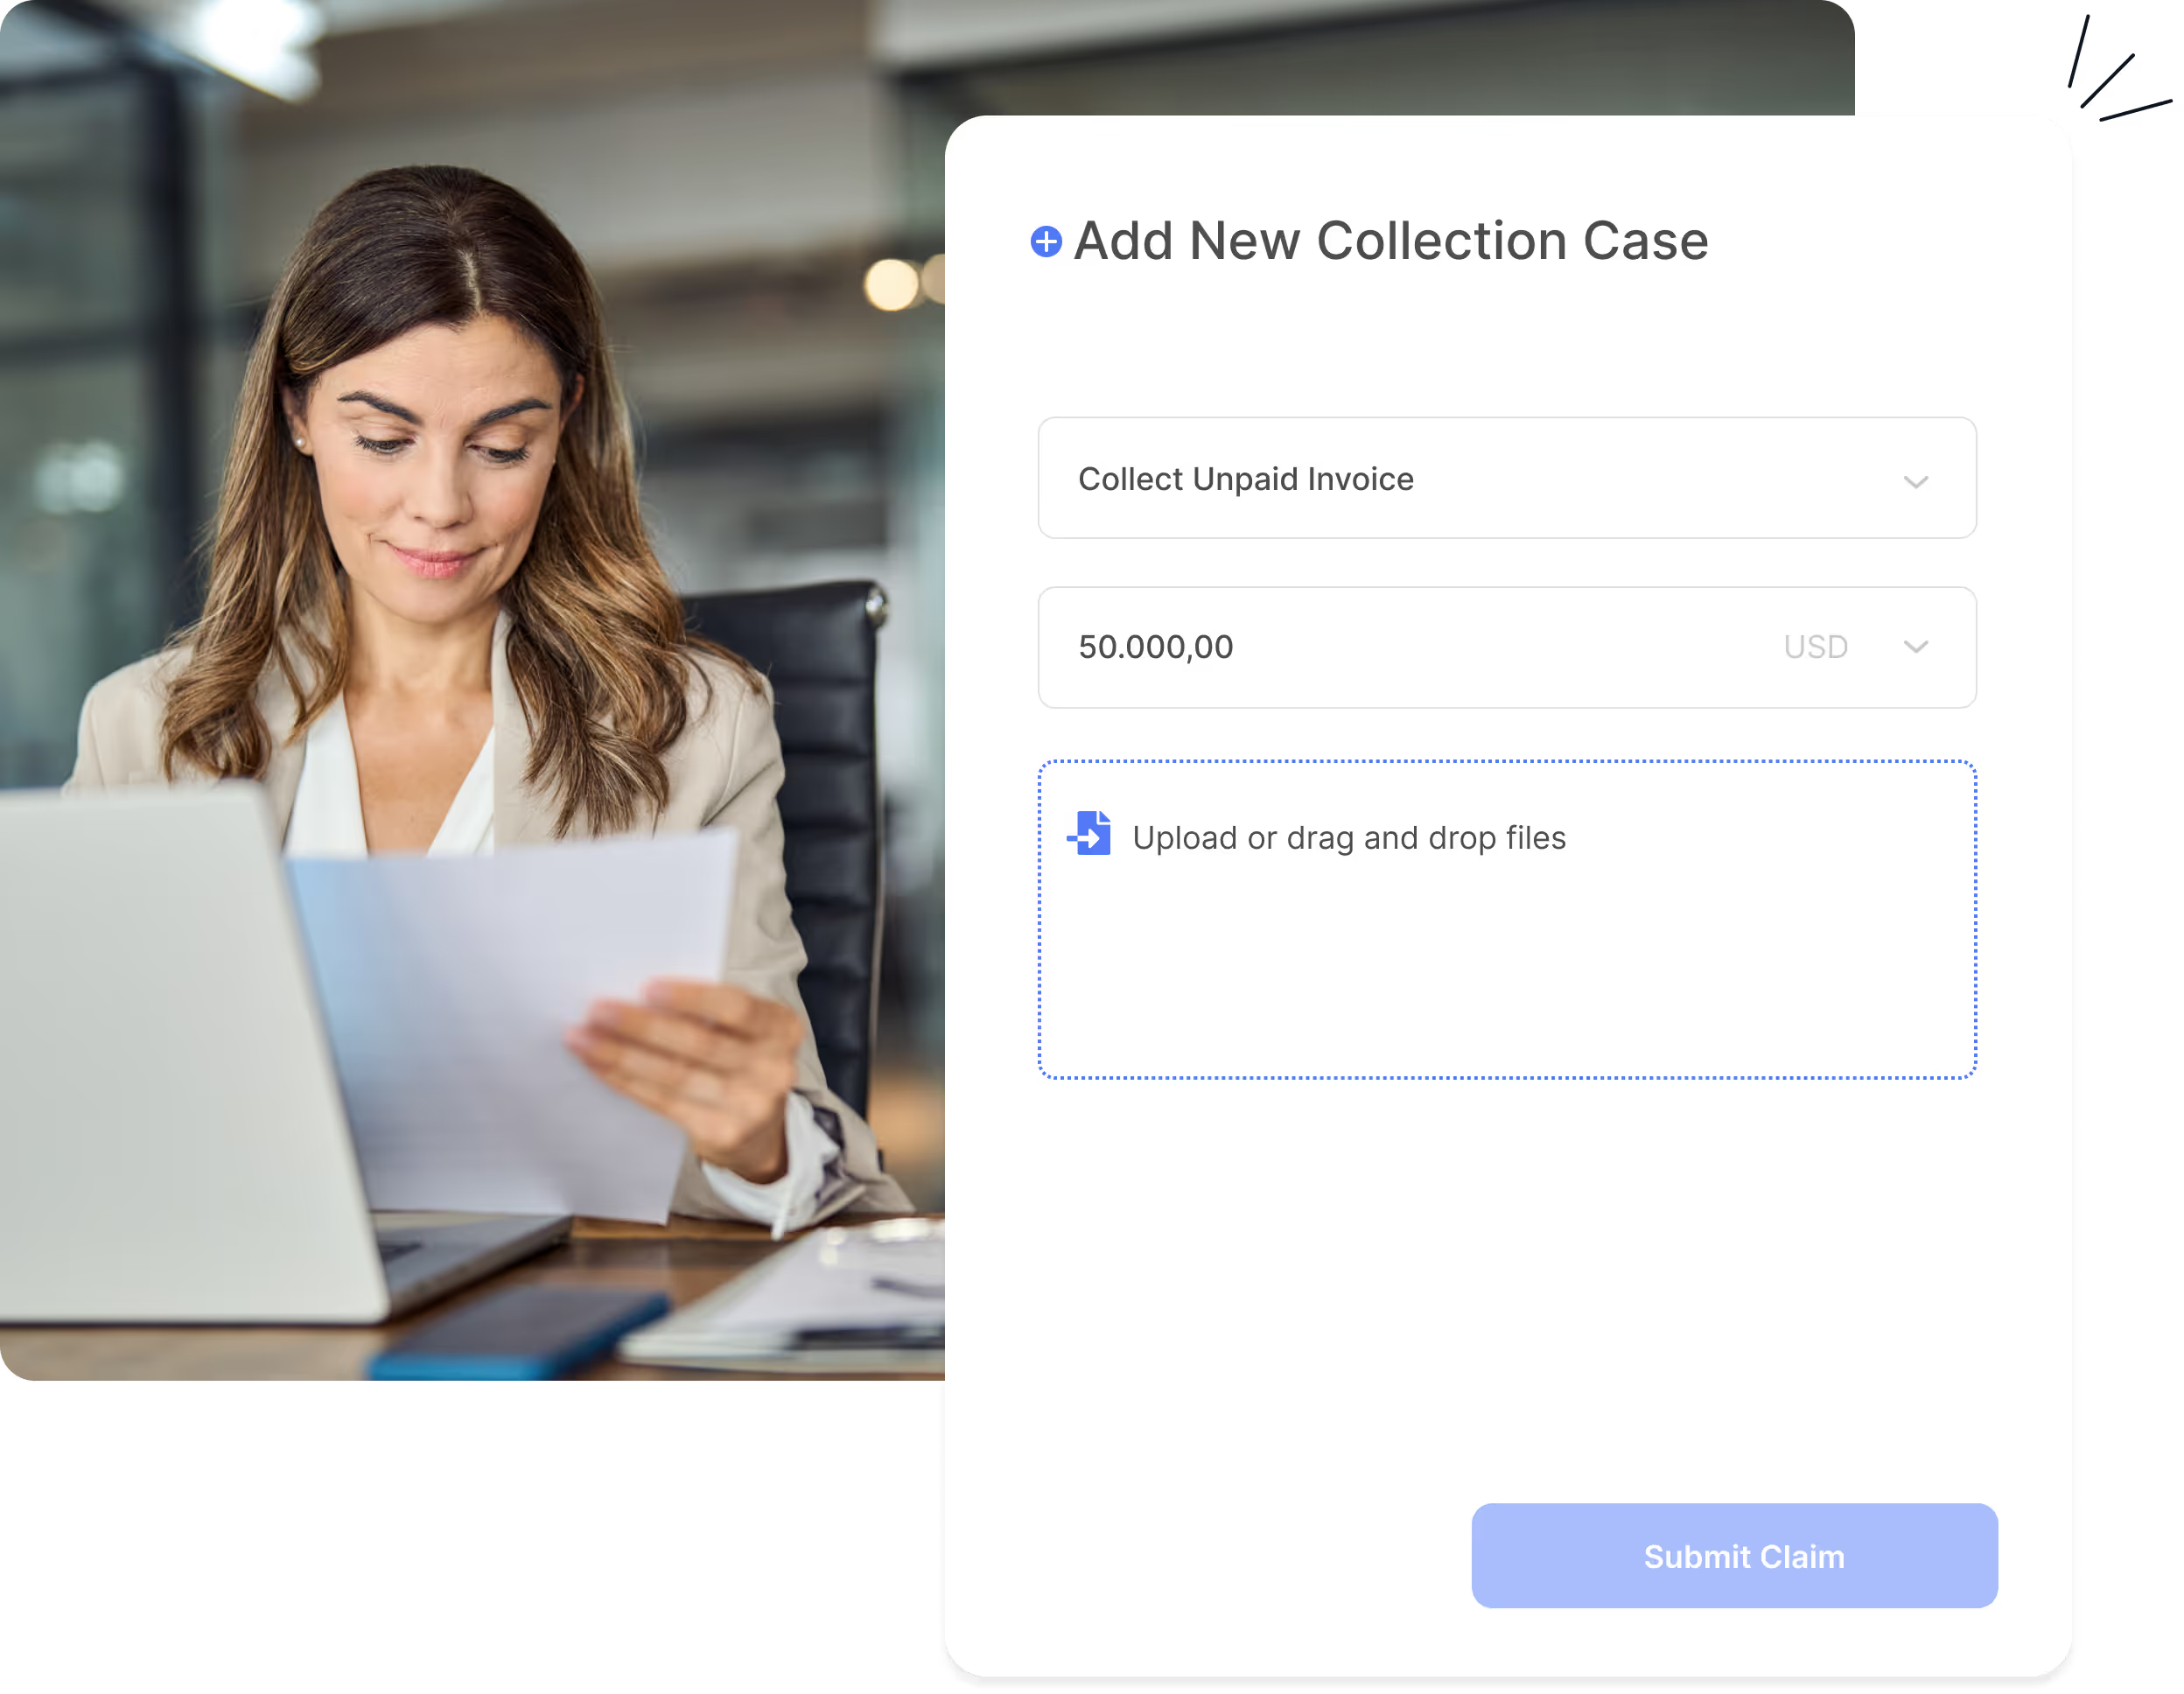
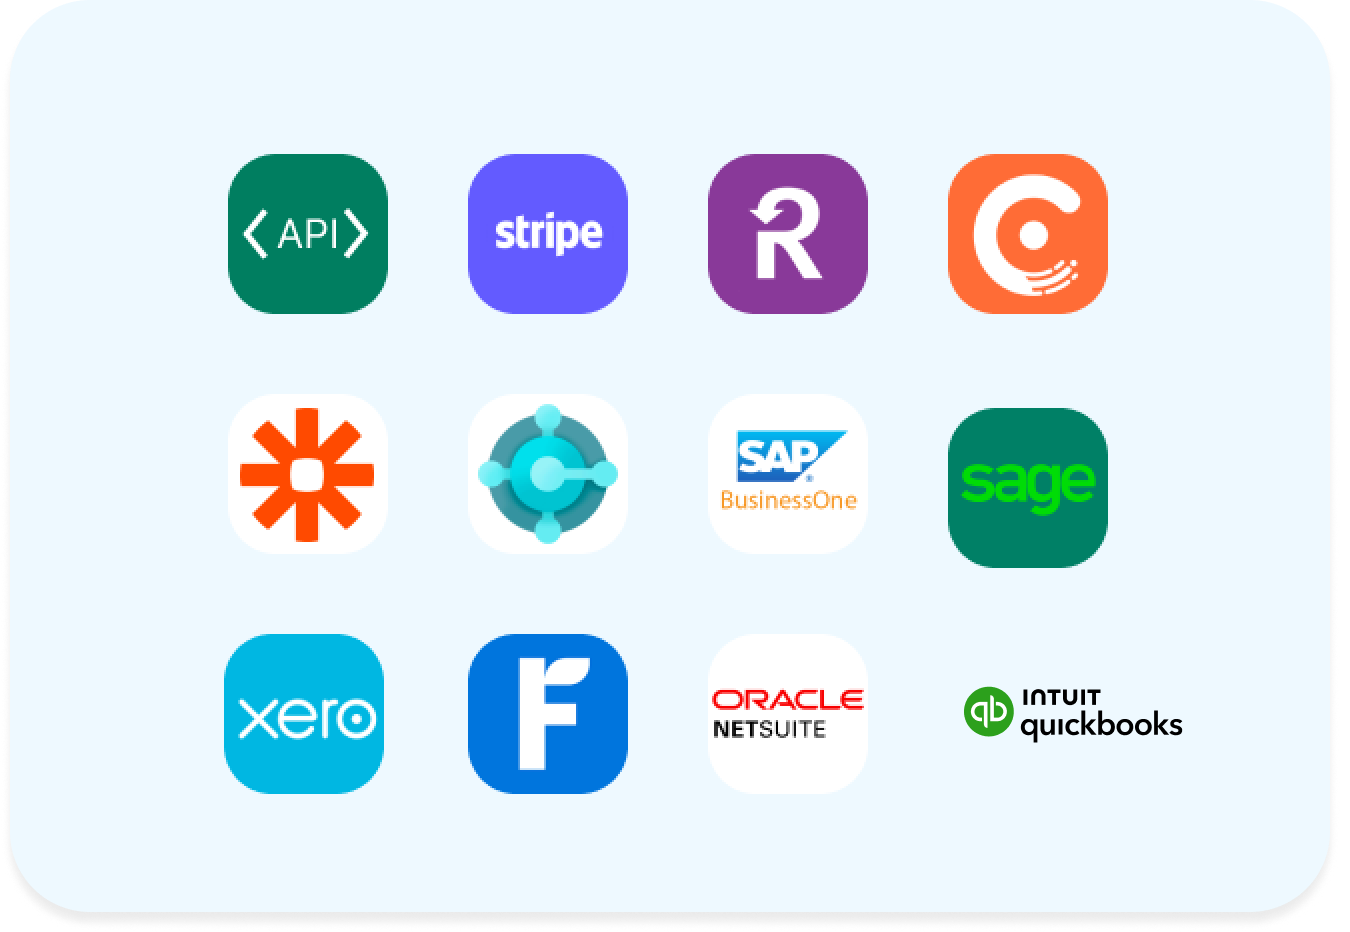
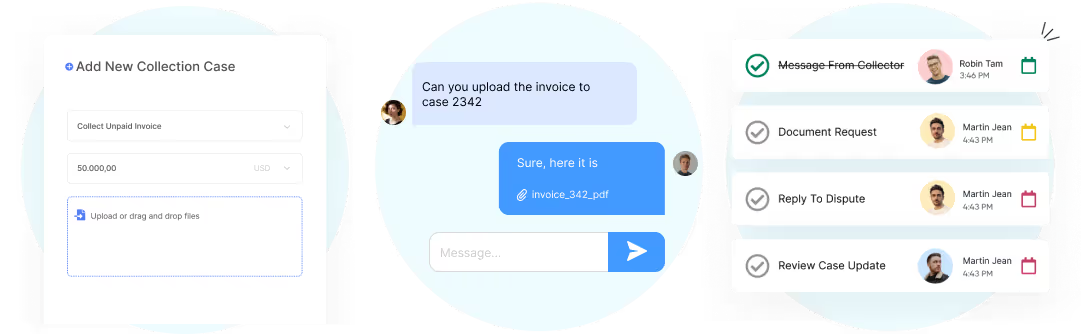
- Submit your claim: upload your unpaid invoice in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server. Add supporting documents in a few clicks, no paperwork and no setup fee.
- Local collection begins: your case is assigned to Kingston Data & Credit Inc., who starts amicable contact with the debtor on your behalf. If legal action is ever needed, you approve a legal quote before anything proceeds, so nothing is spent without your consent.
- Track and get paid: follow every update in real time on your dashboard, from the first reminder to the final payment, with a notification at each milestone. Your partner pays out your share within 30 business days, with a statement, and you pay only on success.
Transparent, success-based pricing
With Debitura you pay a success fee only when money is recovered. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Canada?
Debt collection in Canada begins with an amicable phase run by Kingston Data & Credit Inc., Debitura's licensed local partner: reminders, a formal demand and negotiation aimed at full payment or a written repayment plan. Most straightforward claims settle at this stage. If the debtor still does not pay, escalating to a court-based enforceable title is a separate step you approve, never automatic.
- Amicable collection resolves most undisputed claims without court involvement.
- Escalation to legal action requires your explicit approval of a legal quote.
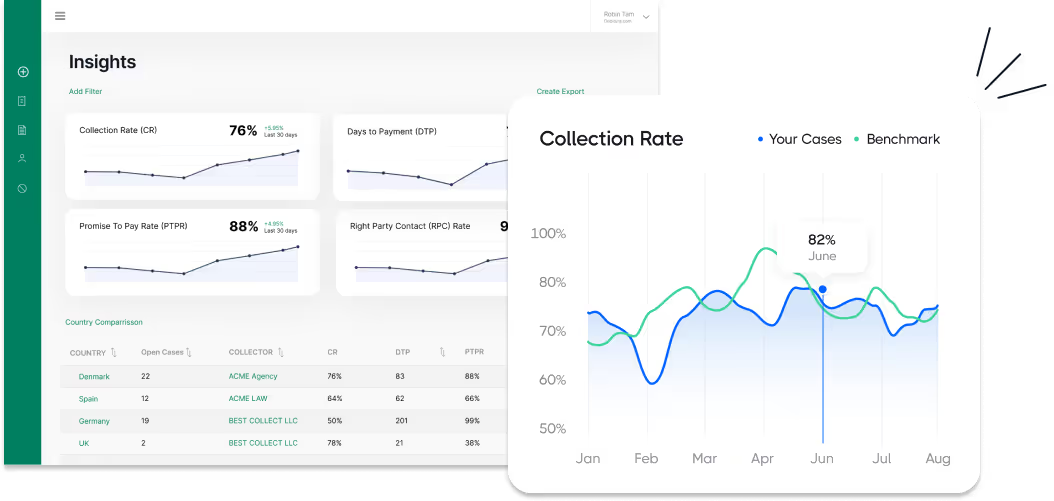
- Every step is tracked in your Debitura dashboard from first contact to payment.
The four steps from unpaid invoice to recovered cash
- Amicable collection: reminders, a formal payment demand and negotiation, handled by a licensed local partner. Most undisputed claims resolve at this stage, without going to court.
- Enforceable title: if the debtor still does not pay, your partner assesses the legal route to an enforceable title and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with an enforceable title in hand, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Insolvency: if the debtor turns out to be insolvent, a proof of claim is filed on your behalf and any distribution is monitored and reported back to you.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full detail for Canada, including timelines, costs, courts and enforcement, follows in the guide below.
Debt collection in Canada - the complete 2026 guide
This guide explains how debt collection works in Canada: the amicable phase, the courts, enforcement and insolvency. Canada has no single national court system or limitation period, so this guide uses Ontario, the largest province by claim volume, as a worked example throughout.
On this page:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).
Contributing local experts:
Last updated:

Debt collection in Canada - quick answers
How much does it cost to collect a debt in Canada?
Court fees vary by province, since Canada has no national court-fee schedule. In Ontario, the largest province by claim volume, filing a Small Claims Court claim costs $108 for an occasional filer or $228 for a claimant filing 10 or more claims a year, plus $144 to issue a garnishment notice and $68 for a writ of seizure and sale or an examination notice; these are Ontario figures only. Filing fees are separate from Debitura's own success-based fee, which is covered later in this guide.
How long does a debt collection case take in Canada?
There is no fixed national timeline. Amicable collection typically runs weeks to a few months before an escalation decision. In Ontario, claims up to the province's $50,000 Small Claims Court limit (effective 1 October 2025) and claims of $200,000 or less in the Superior Court of Justice both follow a mandatory Simplified Procedure under Rule 76.02 of the Rules of Civil Procedure, built to move faster than a full trial track; no province publishes a guaranteed end-to-end duration, since it depends on court backlog and whether the claim is contested.
What is the limitation period for debt claims in Canada?
Canada has no single national limitation period; each province sets its own. In Ontario, used here as a worked example, the basic limitation period is 2 years from discovery of the claim under the Limitations Act, 2002, s.4, extendable to an ultimate 15 years from the act or omission under s.15(2). A debtor's written acknowledgment or part payment resets the 2-year clock under s.13, so keeping dated correspondence of any such acknowledgment is useful evidence if a claim is later disputed.
What interest can I charge on a late payment in Canada?
Where a contract sets no interest rate, the federal Interest Act, s.3, applies a default annual rate of 5%, and s.4 requires that any rate stated for a period shorter than a year disclose its annual equivalent, a protection against disguised high interest rates. In Ontario, once a claim reaches court, the Courts of Justice Act, ss.127-130, sets prejudgment and postjudgment interest at a bank-rate-linked figure republished quarterly; the most recently published rate is 2.5% prejudgment and 4.0% postjudgment (Q1 2026), and costs are awarded at the court's discretion under s.131.
What documents do I need to collect a debt in Canada?
Courts generally require the underlying invoice or contract, proof of the goods or services provided, and a record of amicable contact attempts. In Ontario, a Small Claims Court claim is filed with the prescribed claim form together with supporting documents, or an explanation for why none are attached. Keeping this documentation organized from the start of the amicable phase shortens the eventual court filing step if escalation becomes necessary.
Which legal route should I use to collect a debt in Canada?
The route depends on claim value and province, since Canada has no uniform small-claims ceiling. In Ontario, claims up to $50,000 go to Small Claims Court, a branch of the Superior Court of Justice; claims up to $200,000 in the Superior Court itself follow the mandatory Simplified Procedure; larger or more complex claims proceed through ordinary Superior Court proceedings, with the Divisional Court hearing appeals. A creditor uncertain which route applies to a specific claim should confirm the current limit and procedure in the debtor's own province before filing, since limits change over time, as Ontario's own 2025 increase shows.
Is Ontario representative of the rest of Canada?
No. Ontario is used throughout this guide only as a worked example because it is Canada's largest province by claim volume; no verified small-claims limit, limitation period or court-fee figure for any other province is presented here. Treat every Ontario figure in this guide as illustrative, and confirm the applicable rule in the debtor's own province before relying on it. The federal insolvency rules covered later in this guide are the exception: those apply uniformly across Canada.
| Ontario figure (worked example) | Amount / period |
|---|---|
| Small Claims Court limit (from 1 Oct 2025) | $50,000 |
| Basic limitation period | 2 years from discovery |
| Ultimate limitation period | 15 years |
| Simplified Procedure ceiling (Superior Court) | $200,000 |
| Small Claims filing fee (occasional / frequent filer) | $108 / $228 |
Because these figures are set separately by each province, a creditor with debtors in more than one province should expect different court fees, deadlines and monetary limits for each case; only the federal insolvency rules discussed in Step 4 below apply the same way nationwide.
Who does what in Canada debt collection?
Three types of professional handle debt recovery in Canada: collection agencies work the amicable phase, court enforcement officers execute judgments once a court order exists, and lawyers handle contested or higher-value claims. Regulation of each role sits mostly at provincial level, since Canada has no single national regulator for any of them.
Collection agencies
A collection agency contacts the debtor to negotiate payment before any court step. In Ontario, used here as a worked example, agencies must register under the Collection and Debt Settlement Services Act (R.S.O. 1990, c. C.14) and are overseen by the Registrar at Consumer Protection Ontario, part of the Ministry of Public and Business Service Delivery and Procurement. Regulation 74 caps contact to 3 attempts in any 7-day period within set hours and bans harassment. Debitura's advantage: we work only with a licensed, performance-tracked partner, Kingston Data & Credit Inc., so you never need to vet a collector's registration or conduct history yourself.
Court enforcement officers
Once a judgment is obtained, a court enforcement officer, in Ontario operationally the sheriff, carries out garnishment and writs of seizure and sale under the Rules of Civil Procedure. Provincial fees apply for these steps, for example $144 for a garnishment notice and $68 for a writ of seizure and sale or an examination notice in Ontario. These officers act only once a court has issued an enforceable title; they play no role during the amicable phase.
Lawyers
A lawyer becomes necessary once a claim is contested or exceeds the Small Claims Court limit, since Superior Court proceedings in Ontario generally call for legal representation beyond the Simplified Procedure track. Debitura's partner assesses whether legal escalation is warranted, and you approve a legal quote before any legal cost is incurred, so a lawyer is only engaged with your explicit sign-off.
Which laws and courts apply to debt collection in Canada?
The civil court system in Canada
Canada has no single national civil court system; each province and territory runs its own courts, while insolvency matters are carved out to federal law. In Ontario, used here as a worked example, civil claims start in the Superior Court of Justice, with Small Claims Court operating as a branch of the Superior Court for smaller claims, and the Divisional Court hearing appeals. A creditor pursuing a debtor based in a different province needs to confirm that province's own court structure and limits before filing, since Ontario's structure is not universal.
Key legislation
Two federal statutes apply to insolvency nationwide: the Bankruptcy and Insolvency Act (R.S.C., 1985, c. B-3), which governs personal and corporate bankruptcy and consumer proposals, and the Companies' Creditors Arrangement Act (R.S.C., 1985, c. C-36), which applies only above $5,000,000 in total claims for large corporate restructuring. Ordinary civil claims and their limitation periods, by contrast, sit at provincial level; in Ontario the governing statute is the Limitations Act, 2002, and collection-agency conduct is regulated under the Collection and Debt Settlement Services Act (R.S.O. 1990, c. C.14), renamed from the Collection Agencies Act in 2013. Numerous equivalent provincial statutes exist elsewhere in Canada, none of which are cited here since they fall outside this guide's verified Ontario worked example.
Consumer protection in debt collection (Ontario worked example)
In Ontario, Regulation 74 under the Collection and Debt Settlement Services Act sets specific consumer protections: a collector cannot contact a debtor until 6 days after a prescribed written notice is sent (s.21), and permitted contact hours run 7am-9pm on weekdays and 1pm-5pm on Sundays only, capped at 3 contacts in any 7-day period, with harassment, threats and undue pressure banned (s.22(6)). These protections are set provincially and vary outside Ontario, so a licensed local partner, rather than a generic national script, is the practical way to stay compliant with whichever province's rules apply to a given debtor.
Step 1 - How does amicable (pre-legal) debt collection work in Canada?
Amicable collection is the first stage of debt recovery in Canada: a licensed collection agency contacts the debtor to negotiate payment before any court step. In Ontario, used here as a worked example, agencies are registered under the Collection and Debt Settlement Services Act (R.S.O. 1990, c. C.14) and regulated by the Registrar at Consumer Protection Ontario, part of the Ministry of Public and Business Service Delivery and Procurement.
Ontario's Regulation 74 sets specific rules for this phase: a collector cannot contact the debtor until 6 days after a prescribed written notice is sent (s.21), and permitted contact hours are 7am-9pm on weekdays and 1pm-5pm on Sundays only, capped at 3 contacts in any 7-day period, with harassment, threats and undue pressure prohibited (s.22(6)). These rules exist to keep the amicable phase fair to the debtor while still giving the creditor a genuine opportunity to recover payment without court cost or delay.
| Timeline (typical, Ontario example) | Action |
|---|---|
| Day 0 | Prescribed written notice sent to the debtor |
| Day 6 | Earliest date direct contact is permitted (Reg. 74, s.21) |
| Day 7-60 | Reminders and negotiation within the permitted contact windows |
| Day 60-90 | Case reviewed for escalation if the debtor remains unresponsive |
Escalation to a court-based enforceable title is considered only once amicable contact has been exhausted and the debtor still has not paid or agreed a repayment plan; this decision, and any legal cost, requires your approval. Most straightforward, undisputed claims never need to go beyond this stage.
Step 2 - How do you obtain an enforceable title in Canada?
Canada has no single national small-claims threshold or civil procedure; each province runs its own courts and rules. In Ontario, the largest province by claim volume, claims of $50,000 or less go to Small Claims Court, a branch of the Superior Court of Justice, following the increase to that limit effective 1 October 2025.
Claims above the Small Claims threshold and up to $200,000 in the Superior Court of Justice itself must follow the mandatory Simplified Procedure under Rule 76.02 of the Rules of Civil Procedure, a streamlined track built for mid-value claims. Larger or more complex claims proceed as an ordinary Superior Court action, with the Divisional Court hearing appeals. Choosing the correct track matters, since filing in the wrong court or outside the correct procedure can delay a claim rather than speed it up.
If either party disagrees with the outcome, an appeal to the Divisional Court is possible, which adds time before a judgment becomes final; this is a further reason a creditor should weigh the size and strength of a claim before escalating past the amicable phase described in Step 1.
Filing an Ontario Small Claims Court claim costs $108 for an occasional filer or $228 for a claimant filing 10 or more claims a year. If the debtor does not respond within the prescribed time, the creditor can apply for a default judgment without a full hearing; if the debtor defends the claim, the matter proceeds under the applicable track described above, which typically takes longer and costs more than an undefended claim. Once judgment is granted, prejudgment and postjudgment interest apply at the rate most recently published under the Courts of Justice Act, ss.127-130 (2.5% prejudgment and 4.0% postjudgment for Q1 2026), and costs are awarded at the court's discretion under s.131. A creditor should weigh these potential costs against the claim value before deciding to escalate past the amicable phase described in Step 1.
Step 3 - How does debt enforcement work in Canada?
Once a judgment is granted, Canada has no single national enforcement authority; each province runs its own. In Ontario, used here as a worked example, the sheriff, operationally referred to as a Court Enforcement Officer, carries out enforcement under the Rules of Civil Procedure.
In practice, a creditor typically starts with an examination in aid of execution under Rule 60.18 to identify the debtor's assets and income, limited to once every 12 months, then proceeds to a garnishment notice against wages or bank funds under Rule 60.08, or a writ of seizure and sale against non-exempt property, as appropriate. The Execution Act (R.S.O. 1990, c. E.24) exempts up to $10,000 of household goods, up to $5,000 of a vehicle, tools of trade, and equity in a debtor's principal residence up to the statutory limit, so enforcement recovers what the debtor can afford to lose rather than everything they own.
A judgment from another Canadian province or territory is not automatically enforceable in Ontario. Under the Reciprocal Enforcement of Judgments Act (R.S.O. 1990, c. R.5), a creditor can register a judgment from another reciprocating province or territory, other than Quebec, for enforcement in Ontario within 6 years of the original judgment, without relitigating the claim. This matters for a creditor who obtains judgment in one province against a debtor who later moves, or holds assets, in Ontario. In practice, a creditor should instruct enforcement promptly once judgment is granted, since a debtor's assets and location can change, and the mechanisms described above are the only enforcement tools available in Ontario.
Step 4 - How do insolvency procedures affect debt recovery in Canada?
Insolvency law in Canada, unlike civil claims and court procedure, is entirely federal and applies nationwide under the Bankruptcy and Insolvency Act (R.S.C., 1985, c. B-3) and, for large corporate restructuring, the Companies' Creditors Arrangement Act (R.S.C., 1985, c. C-36). This is the one area of Canadian debt recovery where the rules are identical regardless of the debtor's province.
Types of proceeding
An individual or business becomes an "insolvent person" under the BIA once liabilities reach $1,000, the threshold at which creditors can also apply to force an entity into involuntary bankruptcy. A debtor can instead file a consumer proposal to renegotiate up to $250,000 of unsecured debt, repayable within 5 years, under BIA ss.66.11 and 66.12, which can extend a creditor's recovery timeline but often improves the total amount eventually recovered compared to liquidation. Large corporations facing more than $5,000,000 in total claims can restructure under the CCAA instead of liquidating, continuing operations under court supervision while a plan is negotiated. All bankruptcy filings are administered by a Licensed Insolvency Trustee, licensed and overseen by the federal Office of the Superintendent of Bankruptcy.
Creditor process: proof of claim and priority
To participate in a distribution, a creditor files a Proof of Claim with the trustee. Under BIA s.136(1), the trustee pays claims in a fixed order: administration costs and the BIA levy first, then unpaid wages, taxes, a landlord's arrears of rent, and finally ordinary unsecured creditors, all subject to whatever secured creditors are owed against specific assets. Unsecured creditors typically recover only a partial dividend, if the estate has funds left after higher-ranked claims, which is why an early, accurate Proof of Claim filing matters more than in a straightforward civil enforcement case.
Discharge and outcome
A first-time bankrupt is automatically discharged after 9 months if the bankruptcy is unopposed, or 21 months if opposed, under BIA s.168.1; a second bankruptcy extends this to 24 or 36 months. Once discharged, most debts are released, so a creditor's practical recovery window closes at that point unless a dividend has already been paid from the estate. This is why creditors are generally advised to file a Proof of Claim promptly once notified of a bankruptcy, rather than waiting.
Fees, interest and who pays what in Canada
- Our fee: success-based, No Cure No Pay (see pricing).
- Court and enforcement fees: apply only if the case escalates to legal action, and are separate from Debitura's own fee. In Ontario, a Small Claims Court filing costs $108 (occasional filer) or $228 (frequent filer), a garnishment notice costs $144, and a writ of seizure and sale or an examination notice costs $68; these are Ontario figures only, since Canada has no national court-fee schedule, and other provinces set their own.
- Statutory debtor items: where a contract sets no interest rate, the federal Interest Act applies a default annual rate of 5% (s.3), applicable from the amicable phase onward. Once a claim reaches an Ontario court, prejudgment and postjudgment interest instead apply at the rate most recently published under the Courts of Justice Act (2.5% and 4.0% respectively for Q1 2026).
- Who keeps what: the recovered principal is yours; statutory interest and any recoverable court costs follow the rules above and are added to what you recover, never deducted from it.
Cross-border debt collection in Canada
Canada is not a party to the 2005 Hague Convention on Choice of Court Agreements, so a foreign judgment is not automatically recognized here on that basis. A creditor holding a foreign judgment against a Canadian debtor generally needs to bring a separate recognition action, or start proceedings for the underlying debt directly in the debtor's province, rather than relying on treaty-based automatic enforcement.
Partners in our network
These firms are partners in our network for this country. Open a profile to learn more about each one. If court action is needed on your case, your partner sends a quote on the platform; nothing starts until you accept it.
- Verified specialists
- Nothing starts until you accept the quote
- Fair, pre-negotiated rates

Kingston Data & Credit Inc. is a premier debt recovery agency in Cambridge offering effective Debt Collection services in Canada, positioning itself as the go-to partner with a solid reputation since 2011, serving Canada and the United States, and recognized by industry accolades and memberships.


Debt Recovery Resources is a premier debt recovery agency in the United States offering effective debt collection services, a member of the CLLA, partnering with Debitura for No Cure No Pay solutions.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.