Debt Collection Agency in Estonia - No Win, No Fee
Your Estonian claims are handled exclusively by LECCIS (Credit Management Solutions LLC), our IACC-member regional partner for the Baltics and CIS, founded in 2007 and working from Kyiv. Submit a claim in two minutes and pay only when your money is recovered.


Get free expert advice
Response from a specialist within 24 hours.
Why Choose Debitura for Debt Collection in Estonia
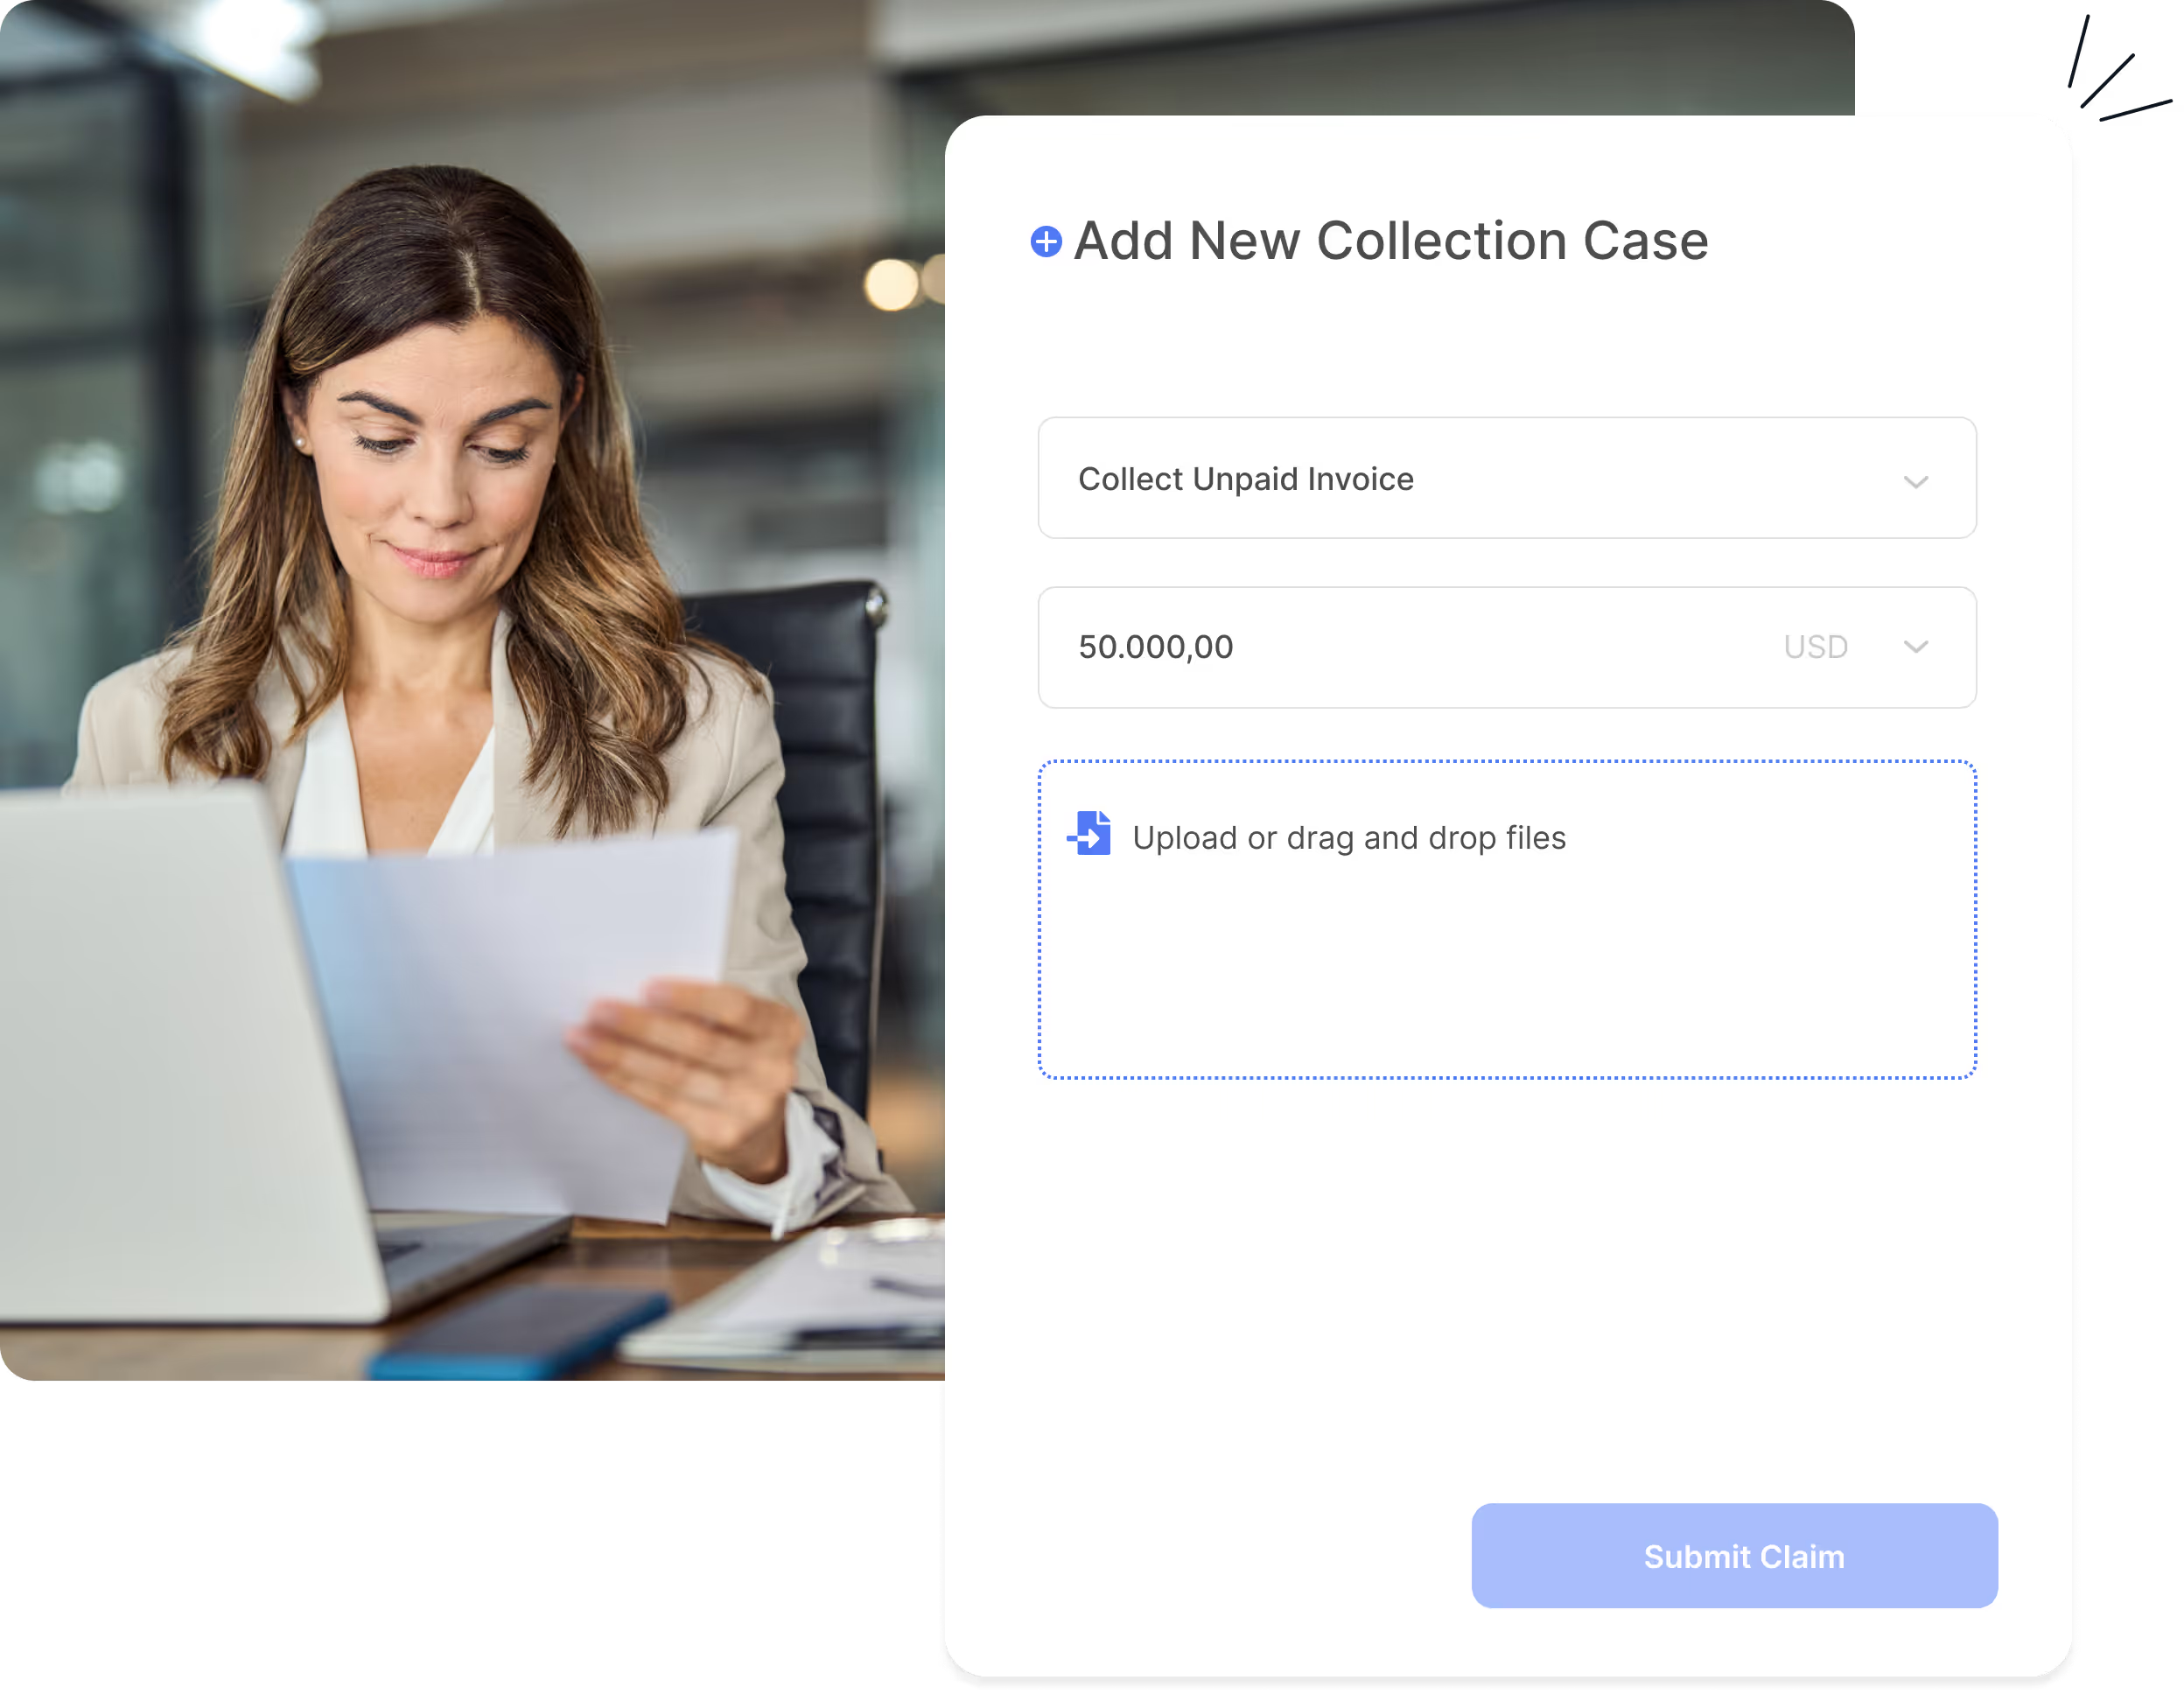
Fast, simple and risk-free debt collection in Estonia
Get your Estonian invoice paid without paying anything up front. Debitura is the platform: we route your claim to a vetted partner, price it before you commit, and keep you in control of every escalation. For Estonia that partner is LECCIS (Credit Management Solutions LLC), our exclusive regional partner for the Baltics and CIS, a law firm founded in 2007 and a member of the International Association of Commercial Collectors.
- Zero risk: you pay a success fee only if the claim is recovered.
- Two-minute submission: upload the invoice, see the fee, approve.
- Full transparency: follow every step live in your dashboard.
- Escalation on your terms: court action needs your approval and a fixed-price quote.
Start recovering your claims in Estonia in minutes
- Submit your claim: Upload your unpaid invoice through the Debitura dashboard, the REST API, or a plug-and-play ERP integration such as Xero or QuickBooks. Add supporting documents in a few clicks, with no paperwork and no setup fees.
- Local collection begins: Your case is assigned to LECCIS (Credit Management Solutions LLC), who starts amicable contact with the debtor on your behalf. If court action is ever needed later, you choose from fixed-price legal quotes before anything proceeds, so nothing is spent without your consent.
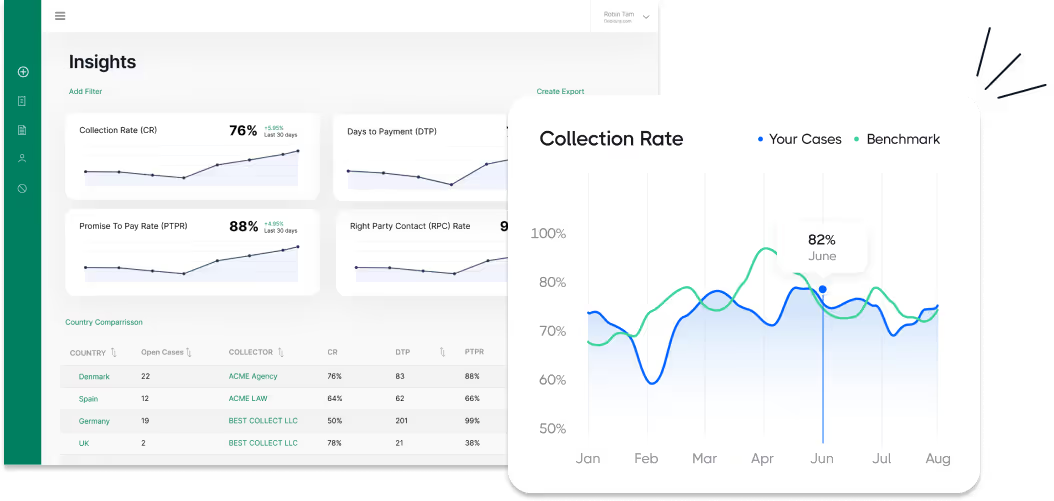
- Track and get paid: Follow every update in real time on your dashboard, from the first reminder to the final payment, with a notification at each milestone. Recovered funds are remitted to you as soon as they clear, and you only pay on success.

Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12–24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve fixed-price quotes before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Estonia?
Debt collection in Estonia starts with an amicable phase handled locally by LECCIS (Credit Management Solutions LLC): reminders and a formal payment demand, aimed at full payment or a written instalment agreement. Most straightforward claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic - your partner assesses the legal route and you approve a quote before any court step.
The four steps from unpaid invoice to recovered cash
- Step 1 - Amicable collection: reminders, a formal payment demand and negotiation, handled locally by LECCIS (Credit Management Solutions LLC). Most undisputed claims are resolved in this phase, without going to court.
- Step 2 - Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title and you approve a fixed-price quote before anything proceeds.
- Step 3 - Enforcement: with a legal title, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Step 4 - Insolvency: if the debtor turns out to be insolvent, your proof of claim is filed and any distributions are monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Estonia - timelines, costs, courts and enforcement - follows in the guide below.

Debt collection in Estonia - the complete 2026 guide
This guide explains debt collection in Estonia for creditors, in-house counsel and finance teams recovering unpaid invoices from Estonian debtors. It covers limitation periods, the fully digital payment-order procedure, enforcement through kohtutäiturid (bailiffs), insolvency outcomes and EU cross-border routes, naming the governing Act at each step.
On this page:
Why you can trust this guide
At Debitura, we uphold the highest standards of impartiality and precision to bring you comprehensive guides on international debt collection. Every guide is written from primary legal sources and reviewed by licensed local experts in the jurisdiction it covers.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 767 licensed partners - collection agencies and law firms in our network
- 180 countries covered - with cases handled in 174 of them
- 5,306 businesses registered with Debitura
- 33 days median time to first payment on European cases
Expert-led, locally validated
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery). Every page is reviewed by top local attorneys to ensure legal accuracy and practical steps you can use.
Contributing local experts:
Last updated:

Debt collection in Estonia - quick answers
The five questions creditors ask most often before starting debt collection in Estonia, answered with the governing Act.
How long do I have to collect a debt in Estonia?
A contract debt in Estonia is time-barred after three years. Claims arising from law rather than from a transaction, claims for intentionally caused damage, and transaction claims where the obligor intentionally violated the obligation all carry ten years instead. The period does not change with the debtor's status: Estonia has no separate consumer or business limitation regime, and its consumer protections work through withdrawal rights, information duties and unfair-terms review rather than through a different clock. Filing a payment-order application suspends the limitation period, which matters when a claim is close to expiry.
| Claim | Limitation period |
|---|---|
| Ordinary contract or transaction debt | 3 years |
| Claims arising from law; intentionally caused damage; intentional breach of a transaction obligation | 10 years |
| Claim already recognised by judgment, court settlement or other enforcement instrument | 10 years from entry into force |
| Judgments entering into force after 1 July 2019 for unlawful damage or linked to criminal proceedings | 20 years |
What does debt collection cost in Estonia?
Pre-legal collection through Debitura costs nothing up front, because our fee is success-based and follows the debtor's country rather than yours. Estonian state fees start only when you go to court: the payment-order procedure carries a state fee of 3 per cent of the claim with a minimum of EUR 65 (Riigilõivuseadus § 59(6)). A bankruptcy petition is a much heavier commitment, at a EUR 420 state fee plus an average trustee-fee deposit of roughly EUR 4,600 paid up front by the petitioning creditor.
What interest and collection costs can I add?
Statutory late-payment interest in Estonia is the European Central Bank main refinancing rate plus eight percentage points (Võlaõigusseadus § 113(1)), with the reference rate published twice a year by Eesti Pank under § 94. On a business-to-business contract you can also claim a fixed EUR 40 minimum compensation for recovery costs under § 113¹ without proving any actual cost, plus reasonable compensation above that figure; a contract term restricting the claim below EUR 40 is void. This provision transposes the EU Late Payment Directive 2011/7/EU and applies to commercial transactions only, so it is not available against a consumer debtor.
Which legal route should I use to collect a debt in Estonia?
For an undisputed money claim up to EUR 8,000 in total, the payment-order procedure (maksekäsu kiirmenetlus) is the route: it is filed only through the e-toimik e-File system with an ID-card digital signature, is handled centrally by the Payment Order Department of Pärnu County Court, and is resolved within ten working days. The EUR 8,000 ceiling covers principal plus ancillary claims, and the ancillary claims may not exceed the principal. The debtor has fifteen days to object, or thirty days if served abroad, and an objection moves the claim into ordinary proceedings before a County Court. Anything above EUR 8,000, and anything genuinely disputed, starts in the County Court.
What happens if my Estonian debtor goes bankrupt?
Expect very little: the average creditor recovery rate in Estonian bankruptcies is approximately 3 per cent, according to the Estonian Insolvency Service's own briefing to the Riigikogu on 28 May 2026. The reasons are structural rather than legal. 81 per cent of the petitions investigated were filed too late, and 45 per cent involved asset stripping before filing, so the estate is usually empty by the time proceedings open. Estonia declared 154 bankruptcies in 2025, down 4 per cent on 2024, against 1,973 bankruptcy and insolvency petitions filed. The practical conclusion for a creditor is to act early on Estonian arrears rather than to rely on the insolvency estate.
Who does what in Estonia debt collection?
Estonian debt recovery separates persuasion from coercion sharply: a collection agency can only ask, while a kohtutäitur (bailiff) can seize, and the boundary between them is the enforcement instrument.
Collection agencies (inkassofirmad)
Collection agencies handle the pre-legal phase: reminders, formal demand letters, telephone contact and negotiated repayment plans, under the general rules of the Võlaõigusseadus (Law of Obligations Act). They hold no coercive powers and cannot attach an account or a wage. Licensing is narrower than it first appears. The Krediidiinkassode ja -ostjate seadus (Credit Servicers and Credit Purchasers Act, CCPA), which transposed EU Directive 2021/2167, requires Finantsinspektsioon (the Estonian Financial Supervision Authority) authorisation for firms collecting or acquiring debts arising from a CREDIT AGREEMENT of a bank or licensed creditor; existing operators had to comply by 30 June 2025, the application fee is EUR 3,000 and processing takes three to six months. Collectors of fines and maintenance arrears are explicitly exempt, and ordinary trade or invoice collection does not appear to trigger the CCPA because such a claim is not a credit-agreement claim. Whether general trade-debt collectors require any other Estonian licence is not settled by any source this guide could verify, so it is not asserted here either way.
Bailiffs (kohtutäiturid)
Bailiffs are independent liberal-profession officers, roughly 52 of them nationally, operating under the Täitemenetluse seadustik (Code of Enforcement Procedure). They act only on an enforcement instrument such as a court judgment or an enforceable payment order, and they hold the whole coercive toolkit: bank-account freezes, attachment of receivables and wages, seizure and auction of movables, and liens over or sale of immovables.
Lawyers (advokaadid)
A lawyer becomes necessary once the debtor objects to a payment order, once the claim exceeds EUR 8,000, or once insolvency is in play. Debitura sources fixed-price quotes from vetted Estonian firms before any court step, so the decision to litigate stays commercial rather than automatic.
Which laws and courts apply to debt collection in Estonia?
Estonian debt recovery runs on one Act for the substantive claim, one for the route to a title, one for enforcement, and a separate set for insolvency. All are consolidated on Riigi Teataja, the official state gazette.
The civil court system
- Maakohtud (County Courts): first instance for all civil and debt claims, and the home of the payment-order procedure through the centralised department at Pärnu County Court.
- Ringkonnakohtud (Circuit Courts): the appellate tier, sitting in Tallinn and Tartu.
- Riigikohus (Supreme Court): the final instance, sitting in Tartu, which also exercises constitutional review.
Key legislation
- Võlaõigusseadus (Law of Obligations Act): contracts and obligations, statutory late-payment interest (§ 113(1)) and the EUR 40 B2B recovery-cost compensation (§ 113¹).
- Tsiviilseadustiku üldosa seadus (General Part of the Civil Code Act): limitation periods.
- Tsiviilkohtumenetluse seadustik (Code of Civil Procedure): civil litigation and the maksekäsu kiirmenetlus payment-order procedure.
- Täitemenetluse seadustik (Code of Enforcement Procedure): bailiff enforcement.
- Pankrotiseadus (Bankruptcy Act), Saneerimisseadus (Reorganisation Act) and Võlgade ümberkujundamise ja võlakaitse seadus (Debt Restructuring and Debt Protection Act): corporate insolvency, corporate rescue and individual debt restructuring respectively.
- Krediidiinkassode ja -ostjate seadus (Credit Servicers and Credit Purchasers Act): Finantsinspektsioon authorisation for collecting or acquiring credit-agreement debt.
- Riigilõivuseadus (State Fees Act): court fees, including the payment-order fee in § 59(6).
Consumer protection in collection
Estonian consumer protection operates through withdrawal rights, pre-contract information duties and unfair-terms review under the Võlaõigusseadus and the Tarbijakaitseseadus (Consumer Protection Act), rather than through a shortened limitation period or a debt-collection-specific conduct statute. A consumer debtor can take a dispute to the Consumer Disputes Committee, an alternative dispute resolution body, instead of to court. The one genuine business-versus-consumer difference relevant to collection sits in costs, not in limitation: the § 113¹ EUR 40 recovery-cost compensation is a commercial-transactions provision and is unavailable against a consumer.
Step 1 - How does amicable (pre-legal) debt collection work in Estonia?
Amicable collection is the first and cheapest route in Estonia: a formal written demand (nõudekiri), direct contact with the debtor, and a negotiated payment or instalment agreement, with no court fee and no bailiff. It is where most undisputed Estonian invoices are resolved, and nothing about it is compulsory, so a creditor can move to the payment-order procedure at any point.
What happens, and when
| Stage | What happens |
|---|---|
| Within 48 hours | Case approval: your partner reviews the documentation and confirms the claim is accepted. |
| Days 1 to 7 | Debtor details verified, then a formal demand (nõudekiri) stating the principal, the accrued statutory interest and the consequences of non-payment. |
| Days 7 to 90 | Structured follow-up by letter, email and telephone, aimed at payment in full or a signed instalment plan. |
| After 3 to 6 months | If the debtor has not paid, the file is assessed for the payment-order procedure or an ordinary claim, and you approve a fixed-price quote first. |
Two things to get right before you escalate
First, calculate the accrued interest properly and put it in the demand: statutory late-payment interest under Võlaõigusseadus § 113(1) is the ECB main refinancing rate plus eight percentage points, and on a business-to-business contract the EUR 40 fixed recovery-cost compensation under § 113¹ can be added without proving any cost. A demand that quantifies both is materially harder to ignore than one that states the invoice alone. Second, check the limitation position, because a three-year contract claim that is close to expiry should go straight into the payment-order procedure: filing that application suspends the limitation period, while continued negotiation does not.
When to stop negotiating
Escalate when the debtor disputes the debt on the merits, when a payment plan is broken, when the debtor stops responding after a formal demand, or when the three-year clock is near its end. Estonian consumer debtors can also refer a dispute to the Consumer Disputes Committee rather than to court, which is worth anticipating where the debtor is a private individual.
Step 2 - How do you obtain an enforceable title in Estonia?
Estonia offers one of the fastest routes to an enforceable title in Europe, and it is entirely digital. For an undisputed money claim up to EUR 8,000 the payment-order procedure (maksekäsu kiirmenetlus) produces a decision within ten working days, without a hearing and without the creditor ever attending a court.
The payment-order procedure (maksekäsu kiirmenetlus)
The application is filed only through the e-toimik e-File system and must be signed with an ID-card digital signature, which in practice means a foreign creditor files through a representative with Estonian digital identity. All applications are handled centrally by the Payment Order Department of Pärnu County Court rather than by the court local to the debtor. The key parameters are fixed by statute.
| Parameter | Rule |
|---|---|
| Claim ceiling | EUR 8,000 in total, principal plus ancillary claims; ancillary claims may not exceed the principal. |
| State fee | 3% of the claim, minimum EUR 65 (Riigilõivuseadus § 59(6)). |
| Resolution time | 10 working days. |
| Debtor objection window | 15 days, or 30 days if the debtor is served abroad. |
| Effect of filing | Suspends the limitation period. |
| Filing channel | e-toimik only, ID-card digital signature required. |
If the debtor objects, or the claim is larger
An objection inside the fifteen-day window ends the fast procedure and moves the claim into ordinary proceedings before a Maakohus (County Court), where the claim is pleaded, evidence is exchanged and the matter is decided on the merits. The same County Court route applies from the outset to any claim above EUR 8,000 and to any claim you already know is disputed. Court fees in ordinary proceedings scale with the value of the claim under the Riigilõivuseadus and are recoverable from the debtor on success, but published, reliable duration figures for ordinary Estonian civil proceedings were not available for this guide, so your partner will quote a timetable on the specific file rather than a national average.
More on court proceedings in Estonia
The digital-identity requirement
Estonia's courts are e-first rather than paper-first, and the practical consequence for a foreign creditor is procedural rather than legal: the barrier is not the right to file but the ID-card signature needed to do it. This is the single most common reason a straightforward Estonian claim stalls before it starts, and it is solved by filing through a local representative.
Appeals
A County Court judgment is appealed to a Ringkonnakohus (Circuit Court) in Tallinn or Tartu, and from there, on limited grounds, to the Riigikohus (Supreme Court) in Tartu. For an ordinary trade debt, an appeal is rare and usually signals a genuine dispute over liability rather than a delay tactic, because an unsuccessful appellant carries the costs.
Step 3 - How does debt enforcement work in Estonia?
Enforcement in Estonia is carried out by kohtutäiturid (bailiffs), independent liberal-profession officers under the Täitemenetluse seadustik (Code of Enforcement Procedure), of whom there are roughly 52 nationally. You choose which bailiff to instruct, submit the enforcement instrument, and the bailiff then holds every coercive power in the process: no creditor, agency or lawyer may seize anything directly.
How long an Estonian title stays enforceable
A claim recognised by a judgment, a court-approved settlement or another enforcement instrument can be enforced for ten years from the moment the instrument entered into force. For judgments entering into force after 1 July 2019 that concern unlawfully caused damage or are linked to criminal proceedings, that window is extended to twenty years. An ordinary trade debt therefore has a full decade of enforceability, which makes it worth re-testing a dormant Estonian judgment against the debtor's current assets rather than writing it off.
What a bailiff can do
| Measure | What it reaches |
|---|---|
| Bank-account freeze | Balances held with Estonian banks, above the debtor's protected minimum. |
| Attachment of receivables and wages | Salary and third-party debts owed to the debtor, above the protected minimum income. |
| Seizure and auction of movables | Vehicles, equipment and stock, realised at public auction. |
| Lien over or sale of immovables | Registered property, either encumbered or sold. |
The process, step by step
- The creditor submits an enforcement application together with the enforcement instrument to a chosen bailiff.
- The bailiff notifies the debtor and normally allows a period for voluntary compliance.
- If the debtor does not pay, the bailiff searches registers, then freezes accounts and seizes assets.
- Seized assets are sold, ordinarily by public auction.
- Proceeds are distributed to the creditor after enforcement costs are deducted.
Debtor protections
Estonian enforcement law exempts essential assets and a minimum level of income from seizure, and the bailiff applies those limits automatically. This is why an enforcement file against an individual with modest income can run for years at a low monthly yield, whereas a corporate debtor with a live bank account is usually resolved quickly or not at all.
Step 4 - How do insolvency procedures affect debt recovery in Estonia?
Estonian insolvency is the point at which most of the value in a claim disappears: the average creditor recovery rate in Estonian bankruptcies is approximately 3 per cent, according to the Estonian Insolvency Service's briefing to the Riigikogu on 28 May 2026. That number should govern the whole strategy on an Estonian receivable, because it makes early action worth far more than a well-argued proof of claim.
Why recovery is so low
The Insolvency Service's own findings point at timing rather than at the statute. Of the petitions it investigated, 81 per cent had been filed too late, and 45 per cent involved asset stripping before filing, so the estate is frequently empty before the trustee is appointed. The cost of opening proceedings compounds the problem: a petitioning creditor advances a EUR 420 state fee plus an average trustee-fee deposit of roughly EUR 4,600, which is money at risk against an estate that may return almost nothing.
How much of this actually happens
| Procedure (2025) | Volume |
|---|---|
| Bankruptcies declared (Pankrotiseadus) | 154, down 4% on 2024 |
| Bankruptcy and insolvency petitions filed | 1,973 |
| Reorganisation proceedings opened (Saneerimisseadus) | 20, down from 38 in 2024 |
| Individual debt-restructuring cases (Võlgade ümberkujundamise ja võlakaitse seadus) | 8 |
The gap between 1,973 petitions and 154 declared bankruptcies is itself informative: most petitions do not end in a declared bankruptcy, and a petition is therefore used in Estonia at least as often as pressure as it is as a genuine liquidation route.
The three procedures
The Pankrotiseadus (Bankruptcy Act) governs liquidation of a company's estate by a court-appointed trustee. The Saneerimisseadus (Reorganisation Act) offers a rescue route for a company that is distressed but viable, and it is used rarely. The Võlgade ümberkujundamise ja võlakaitse seadus (Debt Restructuring and Debt Protection Act) does the same job for a private individual and is used more rarely still.
What a creditor should do
File a proof of claim with full documentation within the deadline set when proceedings open, and expect distribution to follow the statutory priority order, with secured creditors realising their collateral ahead of the general estate. The detailed creditor-priority waterfall and personal-bankruptcy discharge periods could not be verified against primary Estonian text for this guide, so take local advice rather than relying on a summary. The more useful action, given the 3 per cent figure, is upstream: chase Estonian arrears early, take security where the exposure justifies it, and use the ten-working-day payment-order procedure before the debtor's position deteriorates.
Fees, interest and who pays what in Estonia
- Our fee: success-based - No Cure, No Pay (see pricing). The rate follows the debtor's country, not yours.
- Court & enforcement fees: Estonian state fees arise only if the case escalates beyond the amicable phase, are advanced by the claimant and are recoverable from the debtor on success.
- Statutory debtor items: late-payment interest and the fixed B2B recovery-cost compensation are added to the debt itself, not to your invoice from us.
- Who keeps what: the recovered principal is yours; statutory interest and costs follow Estonian rules.
What Estonian law adds to the debt
| Item | Position under Estonian law |
|---|---|
| Statutory late-payment interest (Võlaõigusseadus § 113(1)) | ECB main refinancing rate plus 8 percentage points; the reference rate is published semi-annually by Eesti Pank under § 94. |
| Recovery-cost compensation, B2B only (§ 113¹) | EUR 40 minimum with no proof of cost required, plus reasonable compensation above that; a contract term restricting it below EUR 40 is void. Transposes EU Directive 2011/7/EU, so it is unavailable against a consumer. |
| Payment-order state fee (Riigilõivuseadus § 59(6)) | 3% of the claim, minimum EUR 65. |
| Bankruptcy petition | EUR 420 state fee plus an average trustee-fee deposit of roughly EUR 4,600, both advanced by the petitioning creditor. |
The EUR 40 compensation is the most frequently overlooked item on an Estonian B2B claim. It is owed per invoice and needs no evidence, so it belongs in the first formal demand rather than being introduced later.
Cross-border debt collection in Estonia
Estonia is an EU member state, so a judgment given in another EU member state is recognised and enforced in Estonia automatically under the Brussels I Recast Regulation, with no exequatur proceedings. In practice a creditor with an existing EU judgment can go more or less straight to an Estonian kohtutäitur (bailiff) with it, which is a materially better position than in a non-EU jurisdiction.
The European Payment Order
For an uncontested cross-border claim, the European Payment Order gives a creditor in another member state a single procedure that produces a title enforceable across the EU. It is the natural alternative to Estonia's domestic maksekäsu kiirmenetlus when the creditor is not established in Estonia and has no ID-card digital signature to file domestically.
The European Small Claims Procedure
The European Small Claims Procedure covers cross-border claims up to EUR 5,000, a ceiling raised from EUR 2,000 in 2017. Unlike the payment-order routes it accepts disputed claims, it can be conducted by video conference, and in Estonia it is filed through the Avalik e-toimik public e-File system. For a modest disputed invoice against an Estonian debtor, this is usually the cheapest route to a judgment.
Choosing between the routes
If your claim is undisputed and up to EUR 8,000, the domestic Estonian payment order is faster, at ten working days. If you cannot file domestically, or the debtor disputes the claim, the two European procedures do the work instead. All three end in the same place: an instrument an Estonian bailiff can enforce for ten years.
Find a Local Debt Collection Lawyer
Need court-ready representation? Share your case once and receive up to three proposals from vetted litigation attorneys. Free, fast, and with no commitment.
- Verified specialists
- Quotes in 24 h, no hidden fees
- Fair, pre-negotiated rates

Julianus Inkasso OÜ is a premier debt recovery agency in Tallinn offering effective Debt Collection services in Estonia, known for nearly three decades of expertise in the Baltics, founded in 2000, with accolades and memberships enhancing its trusted reputation.


Narlex Law Firm is a premier law firm in Tallinn offering effective Debt Collection services in Estonia, established in 2011, with over 30 years of professional experience and membership in the Estonian Bar Association, making it the trusted partner for debt recovery.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.