Debt Collection Agency in Iceland - No Win, No Fee
Your claims in Iceland are handled by ESJA Legal ehf, our licensed local partner. No upfront cost, No Cure No Pay, and you track every step online.


Get free expert advice
Response from a specialist within 24 hours.
Why Choose Debitura for Debt Collection in Iceland
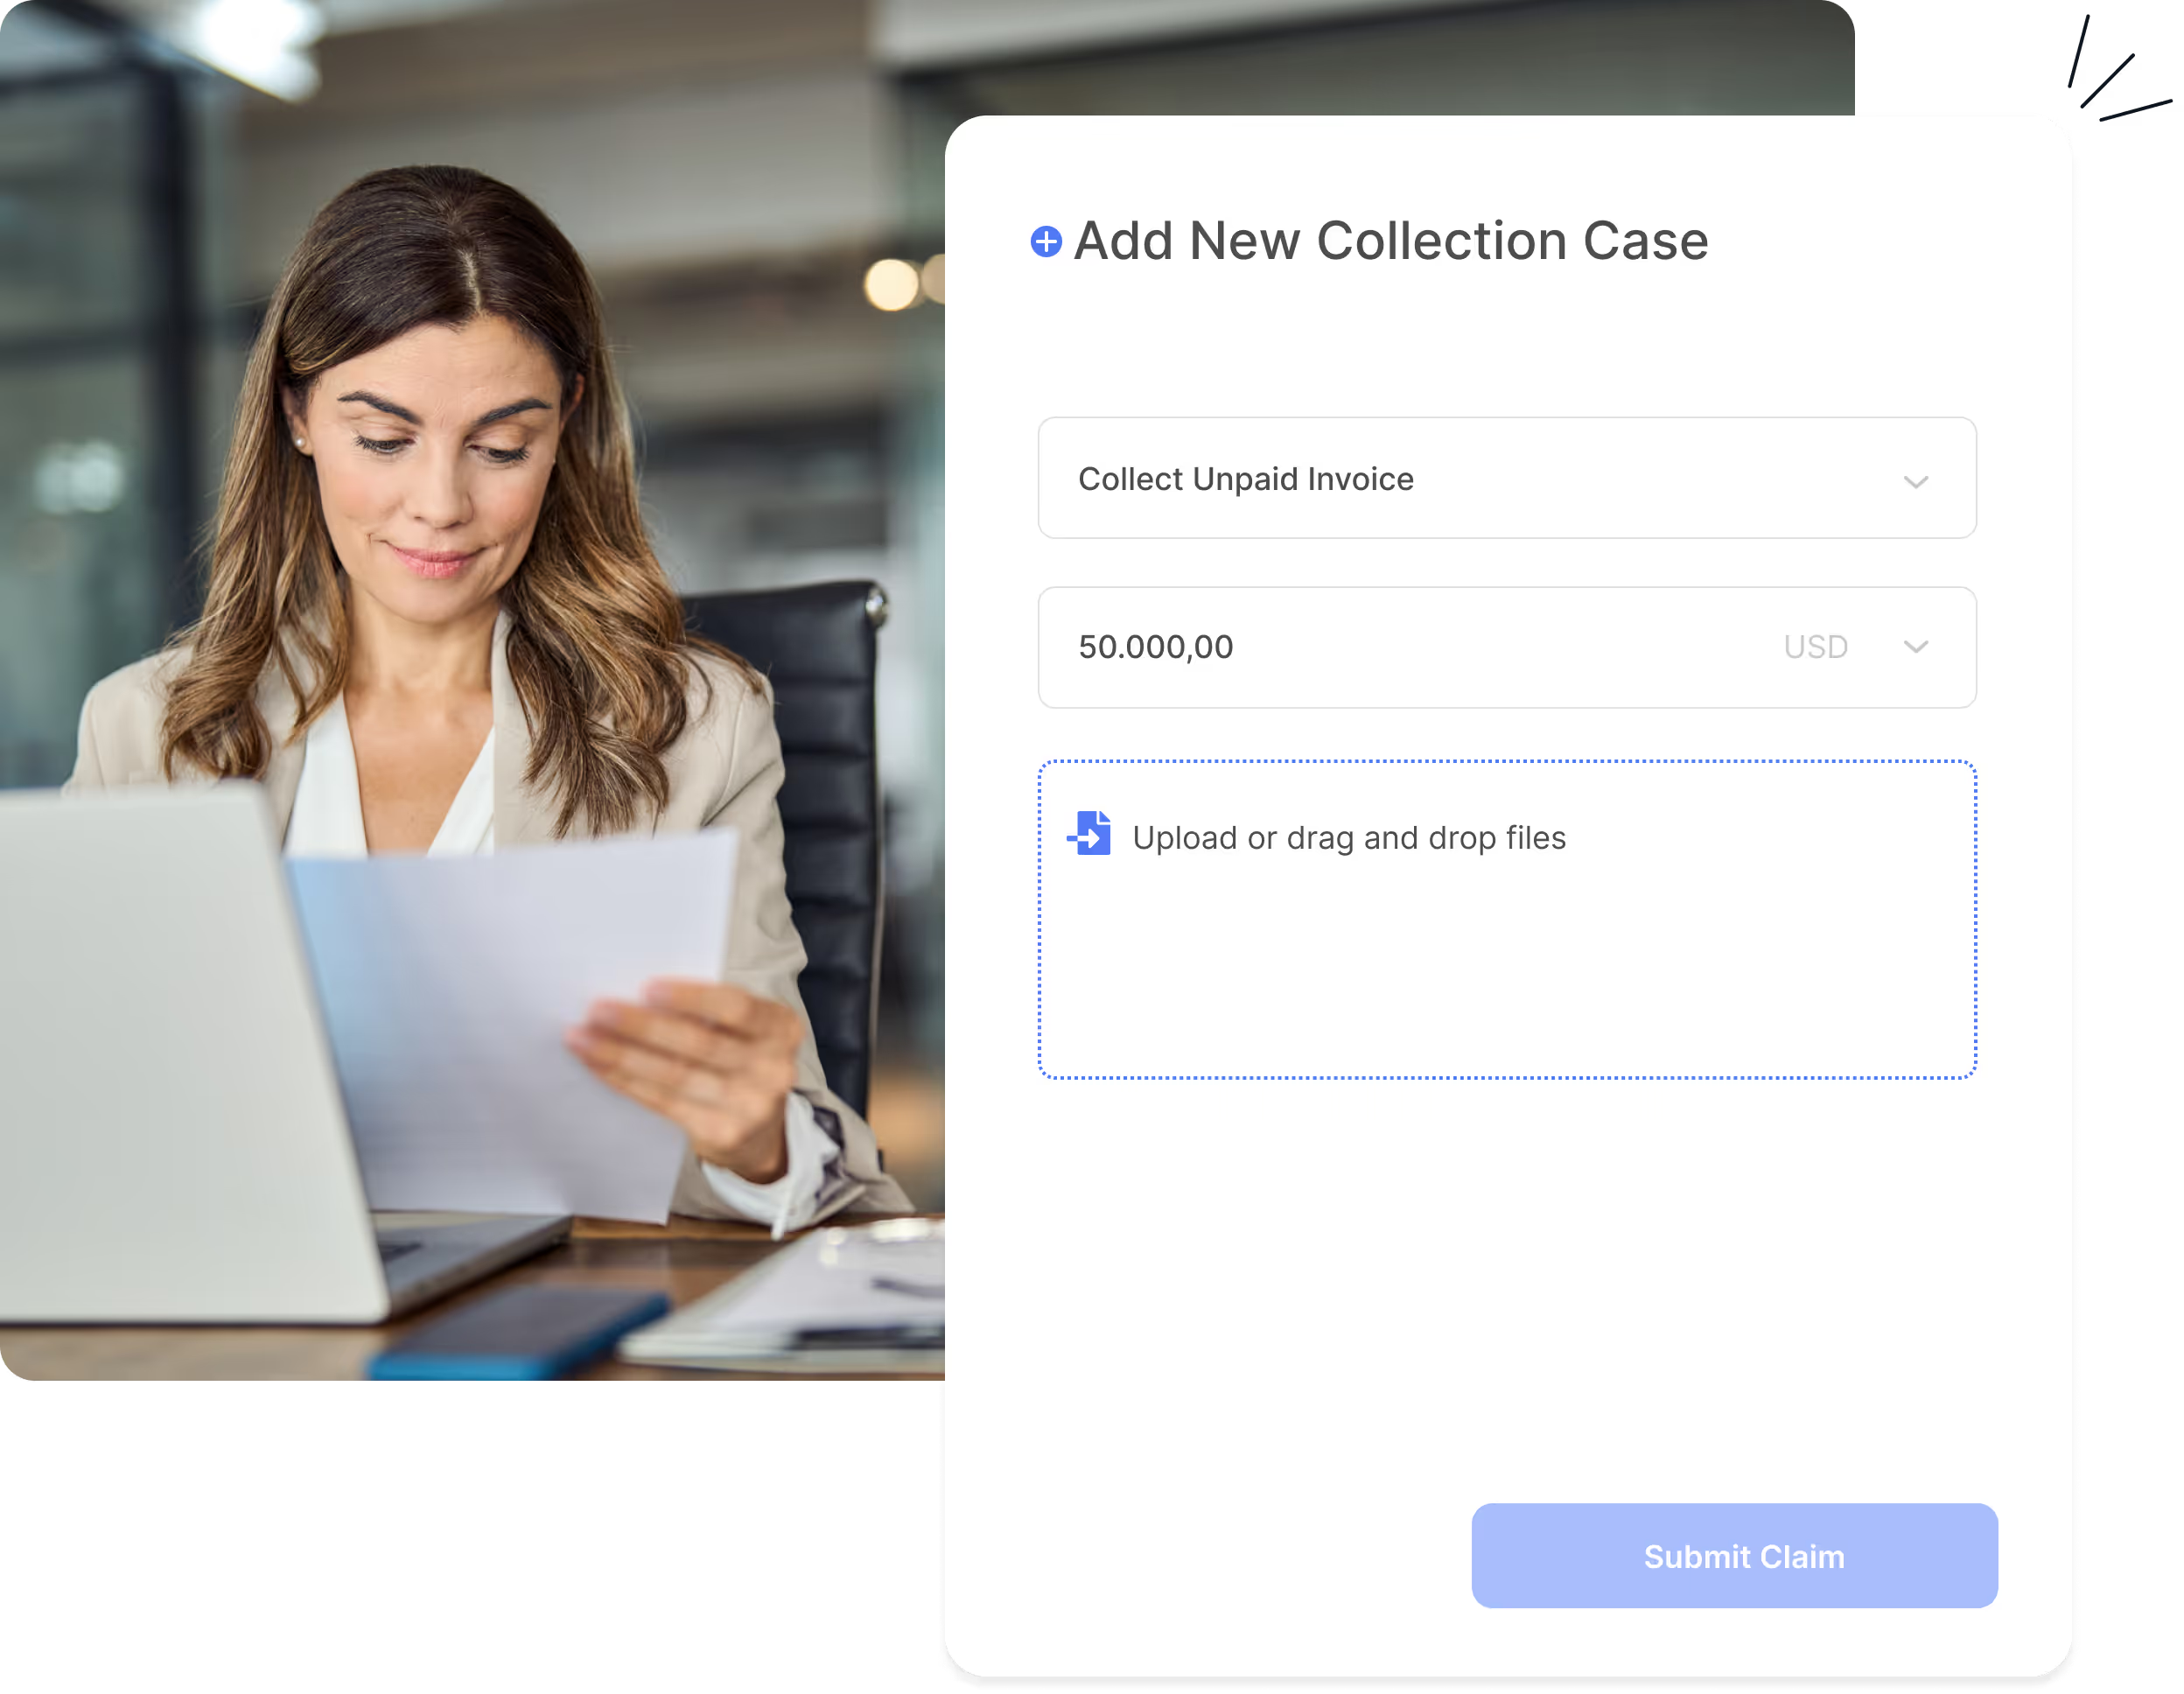
Fast, simple and risk-free debt collection in Iceland
Debitura recovers unpaid invoices from debtors in Iceland through ESJA Legal ehf, a licensed law firm based in Reykjavík and a member of the AEA International Lawyers Network, authorised by Lögmannafélag Íslands (the Icelandic Bar Association) to carry out debt collection.
- Risk-free: No Cure, No Pay, so you owe nothing unless we recover.
- Quick setup: submit your claim online in minutes.
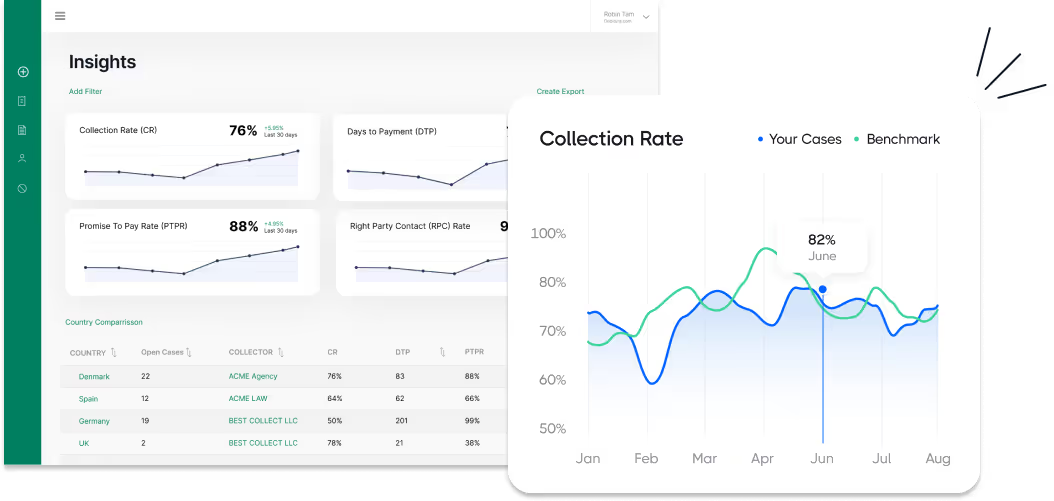
- Real-time tracking: follow your case status from your dashboard.
- Licensed local partner: ESJA Legal ehf handles the regulated work on the ground in Iceland.
Start recovering your Icelandic debts in three steps
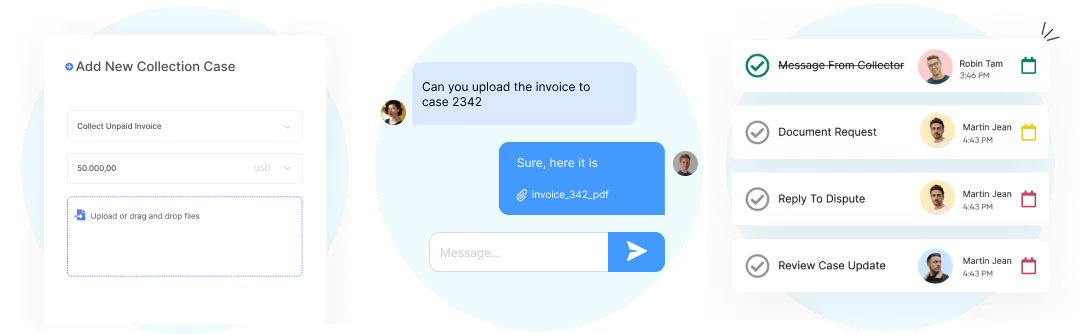
- Upload your claim: submit the invoice and supporting documents online in minutes.
- ESJA Legal ehf takes action: a formal payment demand goes out, followed by negotiation where useful.
- Get paid: funds go directly to your account; escalation to court only happens with your approval.

Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12–24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve fixed-price quotes before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Iceland?
Debt collection in Iceland starts amicably: your case is handled locally by ESJA Legal ehf, a licensed law firm based in Reykjavík, which sends payment reminders and a formal demand before any court step. Most claims resolve at this stage without ever reaching a judge. If the debtor still does not pay, escalation to court and enforcement follows only with your approval, never automatically, so you stay in control of the cost and the timeline at every step.
- Submit your claim online in under 2 minutes.
- A licensed local partner takes the first action on your behalf.
- No Cure, No Pay: you owe nothing unless we recover.
- You approve every escalation before it happens.
- Track your case and get paid directly to your own account.
The four steps from unpaid invoice to recovered cash
- Step 1, Amicable collection: reminders and a formal payment demand from a licensed local partner, aimed at getting you paid without ever going to court.
- Step 2, Enforceable title: if the debtor still does not pay, we help you obtain a court judgment or other enforceable title that a bailiff can act on.
- Step 3, Enforcement: with an enforceable title, the debtor's assets, bank accounts or wages can be seized to satisfy the debt.
- Step 4, Insolvency: if the debtor is genuinely unable to pay, insolvency proceedings determine what, if anything, creditors ultimately recover.
The guide below walks through each of these four steps for Iceland in detail, with the specific courts, laws and timeframes that apply.

Debt collection in Iceland - the complete 2026 guide
This guide explains, step by step, how debt collection works in Iceland: which laws and courts apply, how long you have to act, and what each stage costs. It is written for creditors, in-house counsel and finance teams deciding how to recover a debt in Iceland.
Why you can trust this guide
At Debitura, we uphold the highest standards of impartiality and precision to bring you comprehensive guides on international debt collection. Every guide is written from primary legal sources and reviewed by licensed local experts in the jurisdiction it covers.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 767 licensed partners - collection agencies and law firms in our network
- 180 countries covered - with cases handled in 174 of them
- 5,306 businesses registered with Debitura
- 33 days median time to first payment on European cases
Expert-led, locally validated
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery). Every page is reviewed by top local attorneys to ensure legal accuracy and practical steps you can use.
Contributing local experts:
Last updated:

Debt collection in Iceland - quick answers
How long do I have to collect a debt in Iceland?
You have four years from the due date to bring a claim before it becomes time-barred, under the Limitation Act (Lög um fyrningu kröfuréttinda nr. 150/2007, 3. gr.). Some claim types run longer: money loans, bonds and securities are barred after 10 years, deposits and e-money after 20 years, and once you hold a court judgment or settlement a fresh 10-year period starts (21. gr.). A written demand, or the debtor acknowledging the debt, interrupts the clock and restarts it, so acting early matters even inside the four years.
How much does it cost to collect a debt in Iceland?
Recovering a debt in Iceland does not have to cost you anything upfront, because Debitura works on a No Cure, No Pay basis: you pay only once money is actually recovered. If the case escalates to court or enforcement, the district court's own filing fee and the district commissioner's enforcement fee apply on top, and both are set by statute rather than by Debitura.
What interest and costs can I add to an unpaid invoice in Iceland?
You can charge statutory default interest (dráttarvextir) from the invoice's due date under the Interest Act (Lög um vexti og verðtryggingu nr. 38/2001); the Central Bank of Iceland (Seðlabanki Íslands) publishes the applicable rate every month, and its most recently confirmed notice put it at 15.50% per year, with a higher 8-percentage-point margin over the Central Bank's base rate for business-to-business claims against 7 points for consumer claims. Capped, reasonable collection costs can also be added under the Debt Collection Act (Innheimtulög nr. 95/2008), provided the debtor first received the one written warning notice the Act requires.
Which court handles a debt collection case in Iceland?
Most claims start at one of Iceland's 8 district courts (héraðsdómstólar), the courts of first instance, with appeals going to Landsréttur (the Court of Appeal, established 2018) and, in limited cases, on to Hæstiréttur Íslands (the Supreme Court of Iceland). Iceland has no separate small-claims court: the same civil-procedure track under the Code of Civil Procedure (Lög um meðferð einkamála nr. 91/1991) applies to every money claim regardless of amount, though an undisputed claim reaches judgment faster because there is no evidentiary hearing to schedule.
What documents do I need to collect a debt in Iceland?
At minimum you need the underlying contract or order confirmation, the unpaid invoice, proof that goods or services were delivered, and evidence that a payment demand was sent, since the Debt Collection Act (Innheimtulög nr. 95/2008, 7. gr.) requires at least one written warning notice before further collection costs can be charged to the debtor.
| Claim type | Limitation period |
|---|---|
| General contract or commercial claim | 4 years from the due date |
| Money loans, bonds and securities | 10 years |
| Deposits, valuables and e-money | 20 years |
| After a court judgment or settlement | New 10-year period |
Is collecting from a business different to collecting from a consumer in Iceland?
Yes, in the interest and notice rules rather than in the limitation period. The Interest Act sets an 8-percentage-point default-interest margin for business-to-business claims against 7 points for consumer claims, and negotiated short-term interest rates cannot be applied to consumer loans at all. The Debt Collection Act also lets a business creditor and a business debtor agree by contract to depart from some of the notice requirements that otherwise protect a consumer debtor. The general four-year limitation period itself, by contrast, applies the same way to both.
Who does what in Iceland debt collection?
Licensed collection agencies and law firms
Professional debt collection in Iceland requires an innheimtuleyfi (collection licence) under the Debt Collection Act (Innheimtulög nr. 95/2008, 3.-4. gr.), and a licence-holder must keep a fixed place of business in Iceland and carry professional liability insurance (14. gr.). Lawyers and law firms are exempt from needing a separate licence and instead answer to the Icelandic Bar Association, which is how ESJA Legal ehf, Debitura's exclusive local partner, is authorised to collect. Debitura is the platform that connects you to ESJA Legal ehf; ESJA Legal ehf carries out the licensed, regulated collection work in Iceland.
The supervisory authorities
Non-lawyer collection licence holders are supervised by the Central Bank of Iceland's financial supervision function (the standalone Fjármálaeftirlitið merged into the Central Bank on 1 January 2020); lawyer-run collection, including ESJA Legal ehf's work, is instead supervised by Lögmannafélag Íslands (the Icelandic Bar Association). Neytendastofa (the Icelandic Consumer Agency) covers general consumer protection but has no debt-collection-specific oversight role.
Courts and enforcement officers
Iceland's district courts issue judgments, but enforcement itself is carried out separately by sýslumenn (district commissioners) and their legally trained deputies under the Enforcement Act (Lög um aðför nr. 90/1989, 4. gr.), not by the courts themselves.
Debitura's role
Debitura is the platform: you submit your claim once, we route it to ESJA Legal ehf, and you track progress from one dashboard while ESJA Legal ehf performs the licensed work on the ground in Iceland.
Which laws and courts apply to debt collection in Iceland?
The court system
Iceland runs a three-tier civil court system: 8 héraðsdómstólar (district courts) as courts of first instance, Landsréttur (the Court of Appeal, established 2018) as the intermediate tier, and Hæstiréttur Íslands (the Supreme Court of Iceland) as the final tier, under the Courts Act (Lög um dómstóla nr. 50/2016). Venue generally follows the defendant's legal residence.
Key legislation
Four statutes govern the process end to end: the Code of Civil Procedure (Lög um meðferð einkamála nr. 91/1991) sets out how a case is filed and heard, starting with a stefna (summons) served by a stefnuvottur (process server); the Debt Collection Act (Innheimtulög nr. 95/2008) licenses and regulates who may collect a debt professionally and what notice a debtor must receive first; the Enforcement Act (Lög um aðför nr. 90/1989) governs how a judgment is turned into seized assets; and the Interest Act (Lög um vexti og verðtryggingu nr. 38/2001) sets the statutory default interest rate. The Limitation Act (Lög um fyrningu kröfuréttinda nr. 150/2007) caps how long you have to act.
Consumer and data protection
The Interest Act treats consumer debtors more protectively than business debtors in several places: a lower, 7-percentage-point default-interest margin applies to consumer claims against 8 points for business-to-business claims, and negotiated short-term interest rates cannot be applied to consumer loans at all (6. gr., 2. mgr.). Personal data handled during collection falls under the Data Protection Act (Lög um persónuvernd og vinnslu persónuupplýsinga nr. 90/2018), which implements the EU's GDPR in Iceland through the EEA Agreement and is supervised by Persónuvernd, the Icelandic Data Protection Authority.
How a case is filed
Civil proceedings begin when the creditor's stefna (summons) is formally served on the debtor by a stefnuvottur; for a defendant domiciled in Iceland, the Code of Civil Procedure requires a minimum three full days' notice between service and the case being registered with the district court (art. 91), giving the debtor a short window to prepare before the case is officially underway.
Step 1 - How does amicable (pre-legal) debt collection work in Iceland?
Amicable collection in Iceland starts with a written warning notice, which the Debt Collection Act (Innheimtulög nr. 95/2008, 7. gr.) requires before any further collection costs can be added; a business creditor and a business debtor can agree to depart from some of these notice requirements by contract, but the standard consumer-facing process is a demand letter followed by a short window to pay before costs increase (11. gr.). ESJA Legal ehf handles this stage on your behalf: sending the demand, negotiating a payment plan where useful, and keeping you informed throughout. Escalation to court is a decision you make, not one that happens automatically.
| Timeframe | What happens |
|---|---|
| Day 0 | Claim submitted; ESJA Legal ehf reviews the file and contacts the debtor. |
| Day 1-14 | Formal written payment demand sent, starting the statutory notice period. |
| Day 14-45 | Follow-up contact and, where appropriate, a negotiated payment plan. |
| Day 45-90 | If unpaid, the file is prepared for escalation to court, with your approval. |
Escalate once the debtor stops responding, disputes the claim without a credible basis, or the agreed payment plan is broken; ESJA Legal ehf will recommend the next step before any court fee is incurred.
Reaching an acknowledgement from the debtor at this stage is valuable beyond simply moving toward payment: under the Limitation Act, a debtor acknowledging the debt, whether expressly or through conduct such as a partial payment, interrupts the four-year limitation clock and starts it running again, which protects an older claim from lapsing while amicable contact continues.
Step 2 - How do you obtain an enforceable title in Iceland?
Iceland does not operate a separate small-claims monetary track: every money claim, large or small, follows the same civil-procedure route under the Code of Civil Procedure (Lög um meðferð einkamála nr. 91/1991), starting with a stefna (summons) served on the debtor. What changes with the amount is the district court's filing fee (dómsmálagjald), tiered under the Treasury Fees Act (Lög um aukatekjur ríkissjóðs nr. 88/1991) from ISK 20,000 for claims up to ISK 3,000,000 up to ISK 337,000 for claims above ISK 150,000,000.
Uncontested vs contested claims
A claim moves faster when the debtor does not contest it: Article 80(2) of the Code of Civil Procedure provides a route to judgment for a claim that can be satisfied by an enforcement measure without a full evidentiary hearing, functioning as Iceland's uncontested-claim fast track. A contested claim instead proceeds through pleadings and, where needed, an evidentiary hearing before the district court rules.
Determining the right court
Venue (varnarþing) generally follows the defendant's legal residence among Iceland's 8 district courts; ESJA Legal ehf identifies the correct venue and prepares the summons.
Duration and enforceable titles
An uncontested claim can reach judgment within a few months of filing; a contested claim takes longer and depends on the district court's calendar. Once issued, a court judgment becomes an enforceable title (aðfararhæft skjal) under the Enforcement Act (Lög um aðför nr. 90/1989, 1. gr.), alongside authenticated settlements, certified-signature bonds and recognised foreign court decisions.
More on court proceedings in Iceland
How the district court filing fee scales
| Claim value | Filing fee (dómsmálagjald) |
|---|---|
| Up to ISK 3,000,000 | ISK 20,000 |
| Higher-value claims, in steps | Rising with claim value |
| Over ISK 150,000,000 | ISK 337,000 |
Appeals
A district court judgment can be appealed to Landsréttur (the Court of Appeal), and in limited cases a further appeal reaches Hæstiréttur Íslands (the Supreme Court of Iceland); an appeal does not automatically pause enforcement of the underlying judgment.
Step 3 - How does debt enforcement work in Iceland?
With an enforceable title in hand, enforcement (aðför) in Iceland is carried out by sýslumenn (district commissioners) and their legally trained deputies, never by the courts themselves, under the Enforcement Act (Lög um aðför nr. 90/1989, 4. gr.).
Starting enforcement
The creditor files a written aðfararbeiðni (enforcement request) with the district commissioner together with the enforceable title. The commissioner sends the debtor a greiðsluáskorun (payment demand) with a minimum 15-day notice period before certain enforcement steps proceed (7. gr.).
What can be seized
The primary enforcement instrument is fjárnám (asset seizure), which reaches money, real property, movable property and the debtor's claims against third parties, functionally equivalent to a garnishment order. Certain assets are protected from seizure (41.-50. gr.), including essential household items, part of recent wages, disability compensation and pension contributions, so not every debtor asset is available to satisfy a claim.
How quickly assets are secured
Money in a bank account is generally the fastest asset to secure once fjárnám is granted, since it can be frozen directly. Real property and vehicles registered in the debtor's name can also be attached, but converting seized property into cash for the creditor typically takes longer than a straightforward account seizure, because registration and, where necessary, a forced sale process follow before proceeds reach you.
If enforcement finds nothing
Where the district commissioner's search turns up no seizable assets, the case typically moves toward the insolvency route covered in Step 4, since a debtor with no attachable assets cannot be forced to pay through fjárnám alone.
Step 4 - How do insolvency procedures affect debt recovery in Iceland?
Business insolvency in Iceland runs under the Bankruptcy Act (Lög um gjaldþrotaskipti o.fl. nr. 21/1991), and any creditor may petition for a debtor's bankruptcy with a written, clearly specified and documented request (7. gr.).
Filing a proof of claim
Once a court declares bankruptcy, an umsjónarmaður (court-appointed trustee) publishes a call for claims (innköllun) in Lögbirtingablaðið, the official gazette. Creditors must lodge a written proof of claim (kröfulýsing) with the trustee within 4 weeks of that first publication (44. gr., 1. mgr.); missing the deadline can cost you priority in the distribution.
Composition and pre-bankruptcy protection
Before bankruptcy, a debtor can seek greiðslustöðvun (a court-supervised payment suspension) as a protective measure, and during bankruptcy a nauðasamningur (composition agreement) can discharge certain debts once confirmed by the court, subject to exceptions for priority and secured claims.
Priority in the distribution
Iceland's Bankruptcy Act sets a statutory priority order for paying estate costs and different classes of creditor claim before general unsecured creditors are paid; the exact article-by-article ranking should be confirmed with your Icelandic counsel for the specific estate, since it turns on the facts of each bankruptcy. General unsecured creditors are typically paid last, after secured and priority claims, and often recover only a fraction of what is owed. The exact article-by-article ranking (commonly cited from around 109. gr. onward, covering estate costs, priority wage claims, tax claims and then general unsecured claims) has not been independently verified for this guide; treat it as [NEEDS VERIFIED SOURCE] and confirm the current ranking with Icelandic counsel before relying on it for a specific estate.
Individual debtors
Where the debtor is an individual rather than a company, personal debt relief runs through a separate framework administered by the Umboðsmaður skuldara (Debtors' Ombudsman), primarily under the payment-adjustment law for individuals (Lög nr. 101/2010, greiðsluaðlögun einstaklinga). The Ombudsman itself was established by Lög nr. 100/2010, and two further laws, Lög nr. 50/2009 (temporary payment adjustment for residential mortgage claims) and the older Lög nr. 63/1985 (residential mortgage payment equalisation), sit alongside it for mortgage-specific relief. None of these individual-debtor mechanisms run through the corporate Bankruptcy Act.
Fees, interest and who pays what in Iceland
- Our fee: success-based, No Cure, No Pay. Fees depend on the debtor's country, not yours; for a debtor in Iceland (a European jurisdiction), rates start from 6%. See pricing for the full schedule.
- Court and enforcement fees: apply only if the case escalates, and are set by Icelandic statute rather than by Debitura, tiered by claim value.
- Statutory interest: you may charge the Central Bank of Iceland's published default interest rate (dráttarvextir) from the due date under the Interest Act (Lög um vexti og verðtryggingu nr. 38/2001); its most recently confirmed rate was 15.50% per year, reviewed monthly, with an 8-percentage-point margin for business-to-business claims.
- Recoverable collection costs: reasonable, capped collection costs can be added under the Debt Collection Act (Innheimtulög nr. 95/2008, 12. gr.); the exact ISK cap is set by ministerial regulation and should be confirmed for the current invoice rather than assumed.
- Who keeps what: once a debt is recovered, the principal and any recoverable statutory interest and costs go to you; Debitura's success fee is deducted only from what is actually recovered.
Cross-border debt collection in Iceland
Iceland is an EEA member through EFTA rather than an EU member state, so EU-internal instruments that require EU membership to apply directly, the European Payment Order (Regulation 1896/2006) and the European Small Claims Procedure (Regulation 861/2007), do not apply to Iceland the way they apply between two EU member states.
Instead, recognition and enforcement of civil and commercial judgments between Iceland and the EU (as well as Norway and Switzerland) runs through the 2007 Lugano Convention, to which Iceland, Norway, Switzerland and the EU are all parties. A foreign judgment recognised under Lugano is then enforced through Iceland's ordinary domestic enforcement machinery under the Enforcement Act (Lög um aðför nr. 90/1989, 1. gr.), which lists recognised foreign court decisions among Iceland's enforceable titles.
Find a Local Debt Collection Lawyer
Need court-ready representation? Share your case once and receive up to three proposals from vetted litigation attorneys. Free, fast, and with no commitment.
- Verified specialists
- Quotes in 24 h, no hidden fees
- Fair, pre-negotiated rates
Jonatansson & Co. Legal is a premier law firm in Reykjavik offering effective Debt Collection services in Iceland, recognized as "The Strongest in Iceland" and a member of EUROJURIS International, serving clients since 1984 with award-winning excellence.


Nordik Legal Services is a premier law firm in Reykjavík offering effective Debt Collection services in Iceland, established in 2010, and recognized for its expertise in advising both Icelandic and international businesses, with membership in the Icelandic Bar Association.
FOCUS Lögmenn G.Jónsson & Partners ehf. is a premier law firm in Reykjavik offering effective Debt Collection services in Iceland, renowned for its expertise since 2014 and leveraging global networks through FENCA, ECA, and LIC memberships for comprehensive cross-border solutions.
ESJA Legal EHF is a premier law firm in Reykjavik offering effective Debt Collection services in Iceland, positioning the firm as the go-to partner for debt recovery, founded in 2020, and a member of the AEA International Lawyers Network.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.