Debt Collection Agency in Ireland: No Win, No Fee
Need a debt collection agency in Ireland? For unpaid invoices from business customers in Ireland, your claim is handled by Miller James Limited, an FCA-authorised debt collection firm in Belfast. You track every step in one dashboard, with no upfront fees.


Questions about your case?
Write to us, we reply by email.

Your advantage with Debitura for debt collection in Ireland
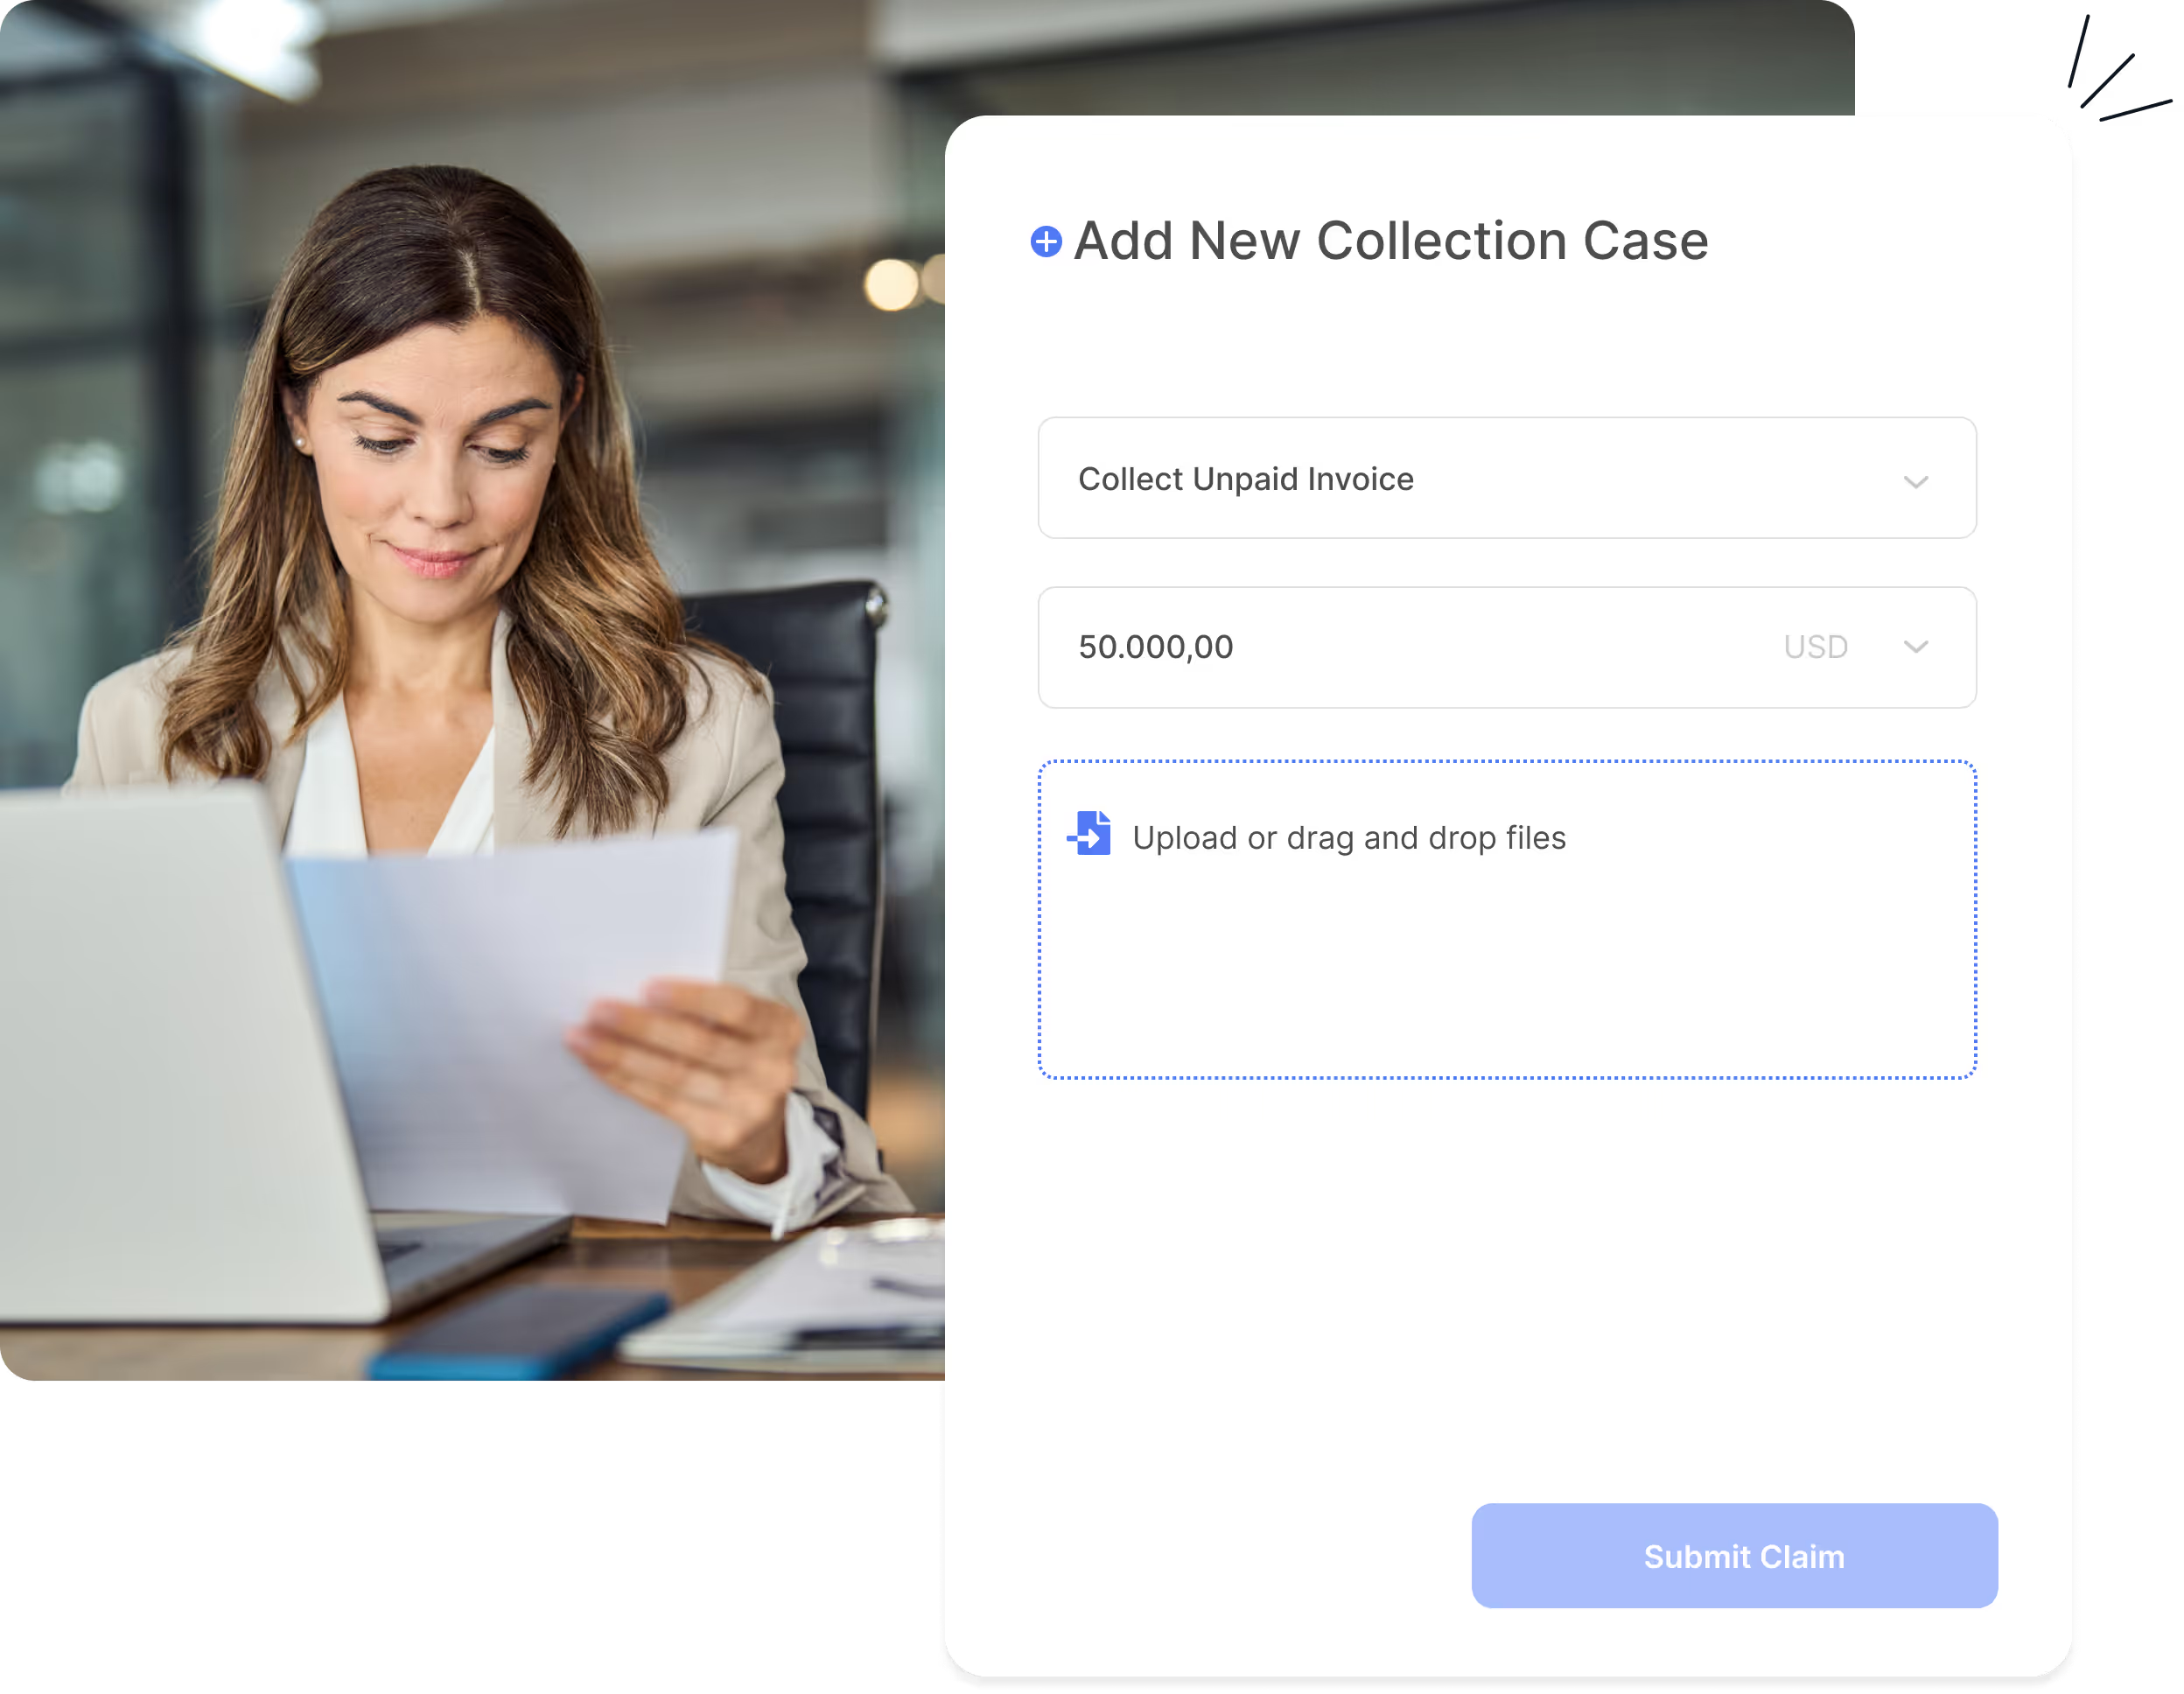
Start recovering your Irish claims in 2 minutes
- Submit your claim: Upload your unpaid claim in minutes in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- Local collection begins: We assign the case to Miller James Limited, who contacts the debtor in English. If court action is needed, you approve a legal quote (e.g., European Order for Payment or a District/Circuit Court claim) before anything proceeds.
- Get paid: Funds are remitted on recovery. For litigation, approve a legal quote
Transparent, success-based pricing
With Debitura you pay a success fee only when money is recovered. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Ireland?
Debt collection in Ireland starts with an amicable phase handled by Miller James Limited: reminders and a formal payment demand, aimed at full payment or a written instalment agreement. Most straightforward claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic - your partner assesses the legal route and you approve a quote before any court step.
The four steps from unpaid invoice to recovered cash
- Amicable collection: reminders, a formal payment demand and negotiation, handled by Miller James Limited. Most undisputed claims are resolved in this phase, without going to court.
- Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a legal title, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Insolvency: if the debtor turns out to be insolvent, recovery depends on the local insolvency proceedings and is often uncertain. Any step in those proceedings is quoted separately and only starts if you accept.
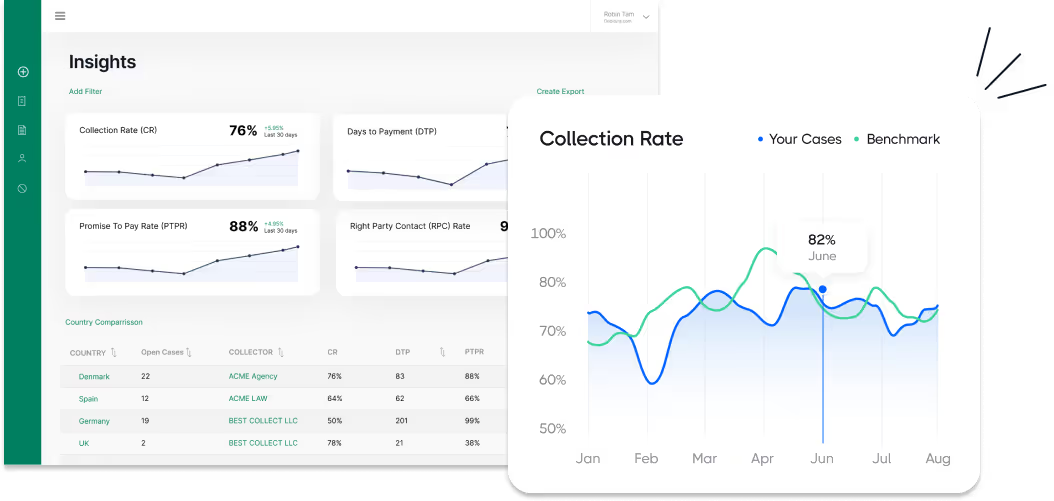
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Ireland - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in Ireland - the complete 2026 guide
This guide explains how debt collection works in Ireland: the courts, the governing law, the four-step recovery process and what it costs. It is written for creditors, in-house counsel and finance teams deciding how to recover a debt in Ireland.
On this page:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).
Contributing local experts:
Last updated:

Debt collection in Ireland - quick answers
How much does debt collection cost in Ireland?
Pre-legal debt collection in Ireland is typically success-based (No Cure, No Pay), so there is no upfront cost. If a claim escalates to court, the state charges an issue fee that scales with the claim value, and a B2B creditor can add statutory interest and fixed compensation on top of the principal.
| Court | Issue fee |
|---|---|
| District Court | EUR 25 (up to EUR 5,000), EUR 70 (over EUR 5,000 to EUR 10,000), EUR 80 (over EUR 10,000) |
| Circuit Court | EUR 90 (up to EUR 45,000), EUR 130 (over EUR 45,000) |
| Small Claims Procedure | EUR 25 flat (excludes business claims) |
All figures are from the Courts Service of Ireland's own published fee schedules. Enforcing a judgment adds a further, instrument-specific fee, covered in Step 3 below.
How long does debt collection take in Ireland?
There is no fixed statutory timeline for the amicable phase; most straightforward claims are resolved through demand letters and negotiation within around three months. In the Small Claims Procedure specifically, a debtor has around 15 days to respond before a disputed claim moves to a District Court hearing, and a debtor generally has 28 days to comply once an order is made, after which an unpaid award is enforced through the Sheriff or County Registrar (Citizens Information). A judgment itself, once obtained through any of Ireland's courts, remains enforceable for twelve years (Statute of Limitations 1957, s.11).
What is the limitation period for a debt claim in Ireland, and can I add interest?
Simple contract debts must be claimed within six years of the due date, while judgment debts and debts under seal (specialty debts) have twelve years (Statute of Limitations 1957, s.11). On business-to-business debts, statutory interest accrues automatically, without needing a reminder, at the ECB main refinancing rate (set each 1 January and 1 July) plus 8 percentage points, alongside fixed compensation for recovery costs (European Communities (Late Payment in Commercial Transactions) Regulations 2012, S.I. No. 580/2012). Further reasonable recovery costs above the fixed amount can also be claimed where justified. For B2C debts, these Regulations do not apply, so interest can only be claimed where it was contractually agreed.
| Debt band | Fixed compensation |
|---|---|
| Up to EUR 1,000 | EUR 40 |
| Over EUR 1,000 to EUR 10,000 | EUR 70 |
| Over EUR 10,000 | EUR 100 |
What documents do I need to collect a debt in Ireland?
Assemble the contract or purchase order, invoices and a statement of account, proof of delivery, and any written correspondence or acknowledgement of the debt. A signed acknowledgement or a part-payment record strengthens both a demand letter and a later court claim, and is worth keeping on file from the moment a claim is first sent to Debitura's partner for the amicable phase. For a Small Claims Procedure filing specifically, keep the underlying contract or receipt to hand, since the claim form is completed at the local District Court office.
Which route should my claim take in Ireland?
A consumer claim up to EUR 2,000 can use the Small Claims Procedure (EUR 25 fee), but the procedure excludes debt claims brought by a business (Citizens Information). Business claims and larger consumer claims are decided by claim value across three ordinary courts.
| Court | Jurisdiction |
|---|---|
| District Court | Up to EUR 15,000 |
| Circuit Court | Up to EUR 75,000 (Courts and Civil Law (Miscellaneous Provisions) Act 2013, s.14) |
| High Court | Above EUR 75,000 |
Once a judgment issues from any of these courts, the choice of enforcement instrument (Sheriff execution, Judgment Mortgage, Attachment/Garnishee, Receiver, or an Instalment Order) depends on the debtor's known assets, not on which court granted the judgment; see Step 3 for the full list.
Who does what in Ireland debt collection?
Debt collection agencies in Ireland
No regulator licenses or supervises private debt collection agencies in Ireland: the Central Bank of Ireland's Consumer Protection Code reaches collection only indirectly, through regulated lenders' outsourced agents, and sets a contact-hours rule of no calls between 9pm and 9am Monday to Saturday, and none on Sundays or public holidays without agreement (Citizens Information). Within that light-touch framework, agencies handle the entire amicable phase: tracing the debtor, sending demand letters, negotiating a payment plan, and applying statutory interest and compensation where a B2B debt qualifies under S.I. No. 580/2012.
The District and Circuit Courts
The District Court hears civil claims up to EUR 15,000 and the Circuit Court up to EUR 75,000; both issue the judgment that becomes the enforceable title once amicable collection fails (courts.ie, Citizens Information). Claims above EUR 75,000 go to the High Court, which has unlimited civil jurisdiction.
Enforcement authorities
Once a judgment is obtained, the Sheriff or County Registrar carries out execution against the debtor's goods, and other instruments such as a Judgment Mortgage, an Attachment/Garnishee order or a court-appointed Receiver are available depending on the debtor's assets (courts.ie's enforcement guide). All of these sit downstream of the court that granted judgment, not the agency that ran the amicable phase.
Solicitors
Once a claim is disputed, or needs to proceed beyond the Small Claims Procedure, a solicitor prepares and files the court claim and, where relevant, advises on enforcement. All debtors, regardless of who is collecting, retain criminal-law protection from harassment or intimidation under s.11 of the Non-Fatal Offences Against the Person Act 1997, which applies equally to agencies, solicitors and creditors acting directly.
Debitura's advantage: one contract and one dashboard connect you to Miller James Limited for the amicable phase and, if escalation is needed, to a legal quote for the court and enforcement stages, without you having to manage separate local relationships.
Which laws and courts apply to debt collection in Ireland?
The civil court system
Ireland's civil courts are organised by claim value. The District Court hears civil claims up to EUR 15,000 (courts.ie, Citizens Information); the Circuit Court hears claims up to EUR 75,000 (Courts and Civil Law (Miscellaneous Provisions) Act 2013, s.14); the High Court has unlimited jurisdiction above that.
| Court / procedure | Claim value |
|---|---|
| Small Claims Procedure (consumer only) | Up to EUR 2,000 |
| District Court | Up to EUR 15,000 |
| Circuit Court | Up to EUR 75,000 |
| High Court | Above EUR 75,000 |
Within the District Court, the Small Claims Procedure gives consumers a low-cost route for claims up to EUR 2,000, but it excludes debt claims brought by a business, so most business creditors use the ordinary District, Circuit or High Court route by claim value, and the correct court is fixed by the amount claimed rather than by choice.
Key legislation
The Statute of Limitations 1957, s.11, sets a six-year limitation period for simple contract debts and twelve years for judgment debts and specialty debts under seal, both running from when the debt fell due. The European Communities (Late Payment in Commercial Transactions) Regulations 2012 (S.I. No. 580/2012) entitles a business creditor to statutory interest at the ECB main refinancing rate plus 8 percentage points, and to fixed compensation for recovery costs, on B2B debts. Where a debtor cannot pay at all, the Companies Act 2014 (winding-up, s.570; examinership, Part 10, s.519) and the Personal Insolvency Act 2012 (Debt Relief Notices, Debt Settlement Arrangements and Personal Insolvency Arrangements) govern the collective insolvency processes covered in Step 4 below.
Consumer and data protection
A debt-collection-specific consumer-protection regime beyond the Central Bank's Consumer Protection Code was not separately confirmed for this guide; the Code's main practical rule for collection is the contact-hours restriction (no calls 9pm to 9am Monday to Saturday, none on Sundays or public holidays without agreement), reaching collectors only indirectly through regulated lenders' outsourced agents. Separately, s.11 of the Non-Fatal Offences Against the Person Act 1997 gives every debtor criminal-law protection from persistent, alarming demands regardless of who is collecting. The General Data Protection Regulation and the Data Protection Act 2018 apply generally to how a creditor or collector processes a debtor's personal data, though this guide did not separately research a debt-collection-specific data-protection regime beyond that general application.
Step 1 - How does amicable (pre-legal) debt collection work in Ireland?
Amicable collection in Ireland begins with tracing the debtor and sending a formal payment demand, followed by negotiation aimed at full payment or a written instalment agreement, all without going to court. Where the debt is a B2B claim, the demand can also state the statutory interest and fixed compensation the creditor is entitled to add under S.I. No. 580/2012, which often encourages faster settlement.
| Day | Action |
|---|---|
| Day 0-7 | Case reviewed, debtor traced, first payment demand sent |
| Day 7-30 | Follow-up contact and negotiation; an instalment plan may be offered |
| Day 30-90 | Further demands; if there is still no payment or agreement, escalation to court is discussed with you |
Throughout this phase, no regulator licenses the agency running collection, but the Central Bank of Ireland's Consumer Protection Code sets a contact-hours rule (no calls 9pm to 9am Monday to Saturday, none Sundays or public holidays without agreement), and s.11 of the Non-Fatal Offences Against the Person Act 1997 protects every debtor from harassment or intimidation regardless of who is collecting.
When to escalate in Ireland
Escalate once the demand lapses without a response, or the debtor disputes the claim without substance. Because the simple-contract limitation period is six years from the due date (Statute of Limitations 1957, s.11), do not let an amicable phase run so long that it puts the limitation period at risk. Escalation is never automatic: your partner assesses the legal route and you approve a quote before any court step, choosing between the Small Claims Procedure, the District Court, the Circuit Court or the High Court by claim value (Step 2 below). A written acknowledgement of the debt, or any part-payment obtained during the amicable phase, is worth keeping on file in case it is needed to support a later court claim.
Step 2 - How do you obtain an enforceable title in Ireland?
If amicable contact fails, the next step depends on the claim's value and who is claiming. A consumer claim up to EUR 2,000 can use the low-cost Small Claims Procedure; larger or business claims go through the ordinary District, Circuit or High Court route.
The Small Claims Procedure
The Small Claims Procedure is capped at EUR 2,000 and costs EUR 25 to file with the District Court office, but it specifically excludes debt claims brought by a business (Citizens Information). The debtor has around 15 days to respond; a disputed claim moves to a District Court hearing, and a debtor has 28 days to comply once an order is made. Unpaid awards are enforced through the Sheriff or County Registrar, the same as any other District Court judgment.
Determining the court
Outside the Small Claims Procedure, the District Court hears civil claims up to EUR 15,000 (courts.ie, Citizens Information); the Circuit Court hears claims up to EUR 75,000 (Courts and Civil Law (Miscellaneous Provisions) Act 2013, s.14); the High Court has unlimited jurisdiction for claims above that. A business claim for any amount, however small, must use one of these three courts rather than the Small Claims Procedure.
| Court | Jurisdiction | Issue fee |
|---|---|---|
| District Court | Up to EUR 15,000 | EUR 25 (up to EUR 5,000), EUR 70 (over EUR 5,000 to EUR 10,000), EUR 80 (over EUR 10,000) |
| Circuit Court | Up to EUR 75,000 | EUR 90 (up to EUR 45,000), EUR 130 (over EUR 45,000) |
An uncontested claim can proceed to judgment without a full hearing; a contested claim requires the debtor to defend, after which the court decides the claim or the parties settle before judgment. Whichever court grants it, the resulting judgment is the enforceable title used in Step 3, and it also starts its own twelve-year limitation period for enforcement (Statute of Limitations 1957, s.11).
Costs beyond the issue fee
Where the claim is a qualifying B2B debt, the statutory interest and fixed compensation described in the fees section below (S.I. No. 580/2012) can be claimed as part of the same court proceedings, on top of the principal and the issue fee. Once judgment issues, choosing which enforcement instrument to use, and whether to combine more than one, is a separate decision covered in Step 3.
Step 3 - How does debt enforcement work in Ireland?
Once a court judgment is final, several enforcement instruments are available depending on the debtor's assets and cooperation (courts.ie's enforcement guide). A judgment debt carries its own twelve-year limitation period from the date of judgment (Statute of Limitations 1957, s.11), so enforcement should not be left indefinitely.
| Instrument | What it does | Fee |
|---|---|---|
| Sheriff execution | The Sheriff or County Registrar seizes and sells the debtor's goods | EUR 19 |
| Instalment Order | District Court orders payment by instalments; breach can lead to a Committal Order | EUR 15 |
| Judgment Mortgage | Registers the judgment as a charge against the debtor's property | EUR 20 plus Property Registration Authority fees |
| Attachment/Garnishee | A third-party debt order attaches money a third party owes the debtor | Court fee applies |
| Receiver | A court-appointed receiver collects income or assets on the creditor's behalf | Court fee applies |
| Bankruptcy petition | Used where the debtor cannot pay at all (see Step 4) | See Step 4 |
The enforcement process
The creditor selects the instrument that matches the debtor's known assets: Sheriff execution for goods, a Judgment Mortgage for property, an Attachment/Garnishee order for money a third party owes the debtor, or a Receiver over income or assets. An Instalment Order can be used where the debtor can pay only over time, and breach of that order can lead to a Committal Order. Where none of these instruments recovers the debt because the debtor genuinely cannot pay, a bankruptcy petition moves the case into the insolvency process described in Step 4.
Choosing between instruments
These instruments are not mutually exclusive: a creditor can register a Judgment Mortgage against property while separately pursuing an Attachment/Garnishee order against a bank account or third-party debt, and can combine any of them with Sheriff execution where the debtor holds movable goods of value. Which combination makes sense depends on what the creditor already knows about the debtor's assets; enforcement generally moves faster where a bank account or identifiable property is already known, and slower where the creditor must first establish what the debtor owns.
Step 4 - How do insolvency procedures affect debt recovery in Ireland?
Corporate insolvency
A creditor owed EUR 10,000 or more can serve a statutory demand at the company's registered office; if it is not satisfied within 21 days, the creditor can petition the High Court to wind up the company (Companies Act 2014, s.570). Alternatively, the company itself, its directors, a creditor, or members holding 10 percent or more of the shares can petition the High Court for examinership, which gives the company an initial 70 days of protection from creditors while an independent accountant reports on its survival prospects; the appointment is notified to the Companies Registration Office on Form E24 within 3 days (Companies Act 2014, Part 10, s.519). Examinership is aimed at rescuing a viable company, so a creditor pursuing a winding-up petition should expect the process to pause if examinership is opened first.
Personal insolvency
Ireland has three personal insolvency arrangements below bankruptcy, each under the Personal Insolvency Act 2012, scaled to the debtor's means and the size of the debt.
| Arrangement | Scope | Duration |
|---|---|---|
| Debt Relief Notice (DRN) | Debts up to EUR 35,000; net monthly disposable income EUR 60 or less; assets up to EUR 1,500 | 3-year supervision; early discharge once 50 percent or more is repaid |
| Debt Settlement Arrangement (DSA) | Unlimited unsecured debt; needs 65 percent or more creditor approval by value | Up to 5 years, extendable to 6 |
| Personal Insolvency Arrangement (PIA) | Secured debt up to EUR 3 million (extendable with consent), plus unlimited unsecured debt | Up to 6 years, extendable to 7; 70-day protective certificate |
Bankruptcy is available above EUR 20,000 of debt, on petition to the High Court's Examiner's Office, and carries a EUR 200 fee and an automatic discharge after 1 year (citizensinformation.ie). Because the DSA and PIA both require a creditor-approval vote by value, a large creditor's response to the proposal can materially affect whether either arrangement passes.
The creditor process
Once any of these processes opens, a creditor should file proof of the claim promptly and monitor the process; individual enforcement against the debtor generally cannot continue once a personal insolvency arrangement or bankruptcy is in place, and a winding-up or examinership similarly displaces individual creditor action against a company. This guide sets out the confirmed thresholds, durations and outcomes for each process; the detailed ranking and proof-of-claim mechanics within a given Irish insolvency case go beyond what this guide can confirm, so confirm those specifics with Irish counsel once a case arises.
Fees, interest and who pays what in Ireland
- Our fee: success-based, No Cure, No Pay (see pricing).
- Court & enforcement fees: apply only if the case escalates to legal action.
- Statutory debtor items: on B2B debts, statutory interest accrues automatically at the ECB main refinancing rate plus 8 percentage points, plus fixed compensation depending on the debt band (European Communities (Late Payment in Commercial Transactions) Regulations 2012, S.I. No. 580/2012).
- Who keeps what: recovered principal is yours; statutory interest and recoverable costs follow the rules below and are separate from Debitura's fee.
| Item | Amount |
|---|---|
| District Court summons fee | EUR 25 to EUR 80, by claim value |
| Circuit Court civil bill fee | EUR 90 or EUR 130, by claim value |
| Statutory interest (B2B) | ECB main refinancing rate plus 8 percentage points |
| Fixed compensation (B2B) | EUR 40 / EUR 70 / EUR 100, by debt band |
| Enforcement instrument fees | EUR 15 to EUR 20, by instrument (see Step 3) |
All figures are from the Courts Service of Ireland's fee schedules and the official S.I. No. 580 of 2012 statutory instrument (Courts Service of Ireland, irishstatutebook.ie). None of these statutory items are a Debitura fee; they are amounts the law allows a creditor to recover from the debtor, separate from what Debitura charges for the recovery service itself.
Cross-border debt collection in Ireland
Brussels I Recast (Regulation (EU) No. 1215/2012) governs recognition and enforcement of judgments from other EU member states in Ireland; a qualifying judgment is enforced here through the Master of the High Court, without a separate exequatur procedure. A European Enforcement Order (Regulation (EC) No. 805/2004) for an uncontested claim is enforced in Ireland as if it were a High Court judgment (e-justice.europa.eu).
For an uncontested cross-border claim, a creditor can apply for a European Order for Payment (Regulation (EC) No. 1896/2006, transposed by the European Communities (European Order for Payment) Regulations 2008) through the Central Office of the Superior Courts; the procedure is available in every EU member state except Denmark (courts.ie).
For a cross-border claim up to EUR 5,000, the European Small Claims Procedure (Regulation (EC) No. 861/2007) is open to business claims, costs EUR 25 to file, and applies across the EU except Denmark (Citizens Information).
Partners in our network
These firms are partners in our network for this country. Open a profile to learn more about each one. If court action is needed on your case, your partner sends a quote on the platform; nothing starts until you accept it.
- Verified specialists
- Nothing starts until you accept the quote
- Fair, pre-negotiated rates
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.