Debt Collection Agency in Pakistan - No Win, No Fee
International Credit Information Limited, our licensed partner in Karachi, collects unpaid invoices in Pakistan on a No Cure, No Pay basis. Track your claim in real time and pay nothing unless we recover your money.


Get free expert advice
Response from a specialist within 24 hours.
Why Choose Debitura for Debt Collection in Pakistan
Fast, simple and risk-free debt collection in Pakistan
Debitura connects you to a licensed local partner to recover unpaid invoices in Pakistan: submit your claim on our platform, and International Credit Information Limited, a Karachi-based debt collection agency licensed since 1998 and a member of ACA International, works your case on a No Cure, No Pay basis while you track progress in real time.
- Risk-free: pay only when we recover your money.
- Quick setup: submit your claim in a few clicks.
- Real-time tracking: monitor progress live in one portal.
- Local expertise: a licensed Pakistani agency handles the case on the ground.
Getting started is simple
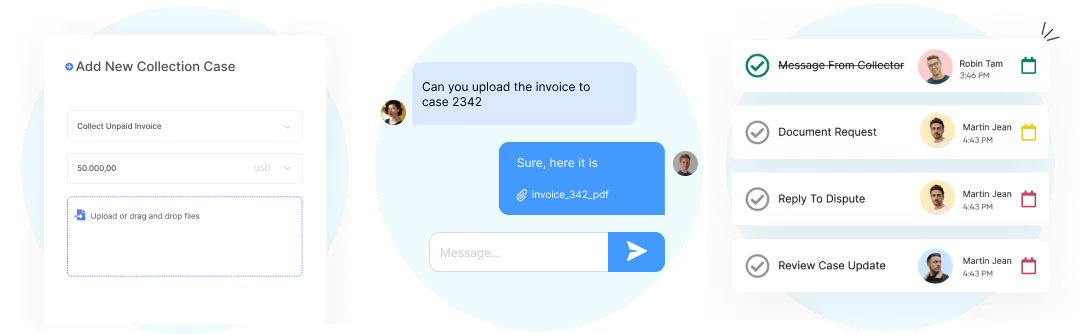
- Create your free Debitura account and submit your Pakistani claim with invoice details.
- International Credit Information Limited reviews your claim and contacts your debtor.
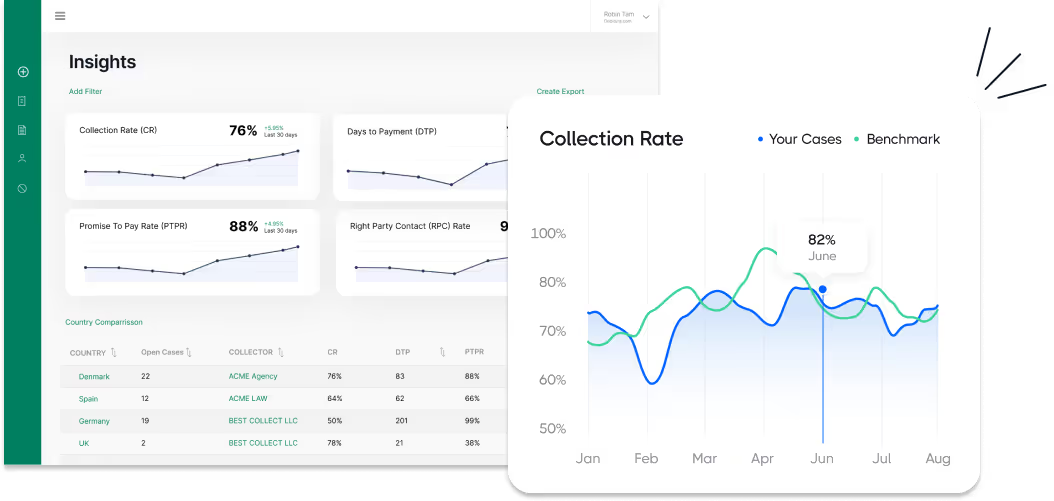
- Track real-time progress in your dashboard. Pay only when funds are recovered.
Prefer automation? Connect your ERP or accounting software to submit claims automatically.

Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12–24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve fixed-price quotes before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Pakistan?
Debt collection in Pakistan starts with an amicable phase handled by International Credit Information Limited, Debitura's licensed local partner: reminders and a formal payment demand, aimed at full payment or a written instalment agreement. Most straightforward claims are resolved at this stage. If the debtor still does not pay, escalation to court is a separate, approved step, never automatic.
- Submit your claim in under 2 minutes.
- Local action starts from Karachi.
- No Cure, No Pay: nothing to pay unless we recover.
- You stay in control: nothing escalates without your approval.
- Get paid: funds are remitted once recovered.
The four steps from unpaid invoice to recovered cash
- Step 1 - Amicable collection: International Credit Information Limited, Debitura's licensed partner in Karachi, sends reminders and a formal payment demand and negotiates directly with the debtor. Most undisputed claims resolve here, without going to court.
- Step 2 - Enforceable title: if the debtor still does not pay, your partner assesses the route to a court decree under the Code of Civil Procedure 1908, and you approve a fixed-price quote before anything proceeds.
- Step 3 - Enforcement: with a decree in hand, the court's own execution process under CPC Order XXI can attach and sell the debtor's assets until the claim is recovered.
- Step 4 - Insolvency: if the debtor turns out to be insolvent, a proof of claim is filed under the Companies Act 2017 for a company or the applicable insolvency Act for an individual, and any distribution is monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Pakistan, timelines, costs, courts and enforcement, follows in the guide below.

Debt collection in Pakistan - the complete 2026 guide
This guide to debt collection Pakistan covers the full process for creditors, in-house counsel and finance teams: the amicable phase, the courts and statutes that apply, enforcement, insolvency and what it costs.
On this page:
Why you can trust this guide
At Debitura, we uphold the highest standards of impartiality and precision to bring you comprehensive guides on international debt collection. Every guide is written from primary legal sources and reviewed by licensed local experts in the jurisdiction it covers.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 767 licensed partners - collection agencies and law firms in our network
- 180 countries covered - with cases handled in 174 of them
- 5,306 businesses registered with Debitura
- 33 days median time to first payment on European cases
Expert-led, locally validated
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery). Every page is reviewed by top local attorneys to ensure legal accuracy and practical steps you can use.
Contributing local experts:
Last updated:

Debt collection in Pakistan - quick answers
Here are the specific, sourced numbers behind Debt Collection Pakistan: cost, deadlines, courts and what you need to start a claim.
How much does debt collection in Pakistan cost?
Debitura's fee is success-based, No Cure, No Pay, charged only on money actually recovered; the fees section below sets out the full frame. If a claim escalates to court, Pakistani courts charge an ad valorem court fee, a percentage of the claim value, under the Court Fees Act 1870 s.7(i), and can award interest at a rate the court considers reasonable under the Code of Civil Procedure 1908 s.34.
How long do I have to collect a debt in Pakistan?
Most trade-debt claims must be pursued within three years of the breach or due date. Under the Limitation Act 1908, an ordinary unregistered contract debt is time-barred three years after breach (Schedule I, Art. 115), and money lent with no fixed repayment date is time-barred three years from the loan date (Art. 57). A debt under a registered written contract has six years (Art. 116), matching the residual six-year period for claims with no other prescribed limitation (Art. 120). A written acknowledgement of the debt signed by the debtor, or a payment on account evidenced in the debtor's own hand, restarts the clock (Limitation Act 1908 ss.19-20).
| Claim type | Limitation period |
|---|---|
| Ordinary contract debt (unregistered) | 3 years from breach |
| Money lent, no fixed repayment date | 3 years from the loan date |
| Registered written contract | 6 years from breach |
| Residual claims (no other period prescribed) | 6 years from accrual |
Which court handles a debt claim in Pakistan?
The route depends on who owes the money and where the claim is filed. Claims against banks and other financial institutions go to specialised Banking Courts under the Financial Institutions (Recovery of Finances) Ordinance 2001: a defendant who does not obtain leave to defend within 30 days faces an automatic decree (s.10), and claims above Rs 100 million go directly to the High Court. Other commercial debt goes through the ordinary civil courts, whose pecuniary jurisdiction is set provincially and territorially, not nationally: in Islamabad Capital Territory, claims below Rs 50 million go to the Civil Judge and claims above go to the District Judge (Code of Civil Procedure (Amendment) Act 2019, s.6), while the Sindh High Court's own original civil jurisdiction begins above Rs 65 million. Current figures for Punjab, Khyber Pakhtunkhwa and Balochistan were not located; the threshold in those provinces should be confirmed at the time a claim is filed.
What documents do I need to collect a debt in Pakistan?
You need the underlying contract or invoice, proof that goods or services were delivered, and any correspondence in which the debtor accepted the debt. A signed acknowledgement is especially valuable in Pakistan because it restarts the limitation clock under Limitation Act 1908 s.19, so it is worth requesting one even during the amicable stage, before a claim is filed.
What happens once a Pakistani court issues a judgment?
The judgment creditor applies for execution under the Code of Civil Procedure 1908, Order XXI, which lets the court attach and sell the debtor's movable and immovable property and attach debts a third party owes to the debtor. The application for execution must be filed within six years of the decree date (CPC s.48), so a decree left unenforced for longer risks becoming impractical to act on.
What if my debtor is a company that becomes insolvent?
A company is deemed unable to pay its debts under the Companies Act 2017 s.302 if a creditor owed more than Rs 100,000 serves a written demand at the registered office and goes unpaid, unsecured or uncompounded for 30 days, among other tests; a creditor can then petition to wind up the company (s.301). Once a winding-up order is made, preferential debts, including employee wages and certain tax and statutory claims, are paid before the general unsecured pool (s.390).
Who does what in Pakistan debt collection?
A debt collection agency in Pakistan handles the amicable, pre-legal stage, working alongside courts and legal counsel, and no single dedicated debt-collection-conduct regulator oversees the whole market.
Collection agencies
Licensed collection agencies, such as Debitura's local partner International Credit Information Limited, handle the amicable, pre-legal stage: contacting the debtor, negotiating payment or an instalment plan, and preparing the file for escalation if needed. For general commercial and trade-debt collection, no dedicated conduct statute exists; conduct instead follows the Contract Act 1872's good-faith principles and the Penal Code's provisions against intimidation and harassment. A separate, sector-specific code (the Pakistan Banks Association's SBP-coordinated collection-agency guidelines) sets binding conduct rules for agencies engaged by banks and other financial institutions, but this applies only to bank-originated debt, not ordinary B2B trade debt. Debitura's advantage: the agency works on a No Cure, No Pay basis and recommends court action only once amicable options are exhausted.
Banking Courts
Where the creditor is a bank or other financial institution, claims are heard by specialised Banking Courts, staffed by District-Judge-rank judges, under the Financial Institutions (Recovery of Finances) Ordinance 2001. These courts run a summary procedure: the defendant must obtain leave to defend within 30 days or face an automatic decree (s.10), and claims above Rs 100 million, or involving an alleged criminal offence, go directly to the High Court instead.
Civil courts and advocates
Non-banking commercial debt goes through the ordinary civil court hierarchy, Civil Courts, then District Courts, with the provincial High Court on appeal, under the Code of Civil Procedure 1908. A licensed advocate is standard practice once a case is contested, since pleadings, evidence and enforcement applications all follow the CPC's formal procedure.
Which laws and courts apply to debt collection in Pakistan?
Civil court system
Pakistan's civil judiciary is tiered: Civil Courts hear first-instance claims, District Courts hear larger claims and appeals from the Civil Courts, and each province's High Court sits above them, both as an appellate court and to decide constitutional questions. Pakistan is a federation: the pecuniary jurisdiction of the civil courts, the rupee thresholds that decide which level of court hears a given claim, is set and revised provincially and territorially, not nationally. In Islamabad Capital Territory, the Civil Judge hears claims below Rs 50 million and the District Judge hears claims above that figure (Code of Civil Procedure (Amendment) Act 2019, s.6); the Sindh High Court's own original civil jurisdiction begins above Rs 65 million. Current figures for Punjab, Khyber Pakhtunkhwa and Balochistan were not located and should be confirmed at the time a claim is filed rather than assumed.
Key legislation
Contract law is governed by the Contract Act 1872. Civil procedure and enforcement follow the Code of Civil Procedure 1908, whose Order XXI sets out execution: attachment and sale of assets, garnishee-style attachment of debts, and arrest of the judgment-debtor in specific circumstances. Limitation periods sit in the Limitation Act 1908. Bank and financial-institution debt recovery is governed separately by the Financial Institutions (Recovery of Finances) Ordinance 2001, heard by dedicated Banking Courts. Corporate insolvency and winding-up sit in the Companies Act 2017, administered by the Securities and Exchange Commission of Pakistan (SECP), while individual insolvency splits between the Insolvency (Karachi Division) Act 1909 (former Karachi Division) and the Provincial Insolvency Act 1920 (elsewhere).
Consumer and data protection
Pakistan has no dedicated debt-collection-conduct statute or regulator guideline for general commercial debt, comparable to an FDCPA or a UK-style code of practice. General protection against intimidation or harassment during recovery instead sits in the Contract Act 1872's good-faith principles and the Pakistan Penal Code's provisions on criminal intimidation. A narrower, sector-specific conduct code (the Pakistan Banks Association's SBP-coordinated collection-agency guidelines) binds agencies collecting bank-originated debt, but does not extend to ordinary trade-debt collection.
Step 1 - How does amicable (pre-legal) debt collection work in Pakistan?
Pakistan has no statutory pre-action protocol that a creditor must follow before suing for a debt: amicable collection is standard commercial practice, not a legal requirement, and typically involves direct contact with the debtor and a formal written payment demand aimed at full payment or an instalment agreement.
Why a written record matters
Under the Limitation Act 1908, a written acknowledgement of the debt signed by the debtor (s.19), or a payment on account of the debt evidenced in the debtor's own handwriting or a writing they sign (s.20), restarts the limitation clock: a fresh limitation period runs from the date it was given. Capturing either during the amicable stage protects a claim that might otherwise be approaching its time bar.
Applicable limitation periods
Ordinary trade-debt claims are generally time-barred three years after breach (Limitation Act 1908, Schedule I, Art. 115), and money lent with no fixed repayment date is time-barred three years from the loan date (Art. 57). A debt under a registered written contract has six years (Art. 116), matching the residual six-year period for claims with no other prescribed limitation (Art. 120). Because most trade debts fall under the shorter three-year period, claims approaching that deadline should move toward the enforceable-title stage in good time.
Sector-specific conduct rules
Where the underlying creditor is a bank, DFI or other financial institution, a separate conduct code, the Pakistan Banks Association's SBP-coordinated guidelines for collection, recovery and repossession agencies, sets binding rules on contact hours, prohibited threats and impersonation, and complaint handling. This code does not extend to ordinary commercial or trade-debt collection between non-financial parties.
Step 2 - How do you obtain an enforceable title in Pakistan?
Which route gets you an enforceable title in Pakistan depends on who owes the money: bank and financial-institution debt goes through a fast, specialised summary procedure, while other commercial debt goes through the ordinary civil courts.
Banking Courts (fast track for financial-institution debt)
Claims by banks and other financial institutions are heard by Banking Courts, staffed by District-Judge-rank judges, under the Financial Institutions (Recovery of Finances) Ordinance 2001. The procedure is summary: once the suit is filed, the defendant must apply for and obtain leave to defend within 30 days (s.10); leave is granted only if the defendant raises a substantial triable question, and if it is not sought or granted, the court decrees the claim automatically. An appeal against a Banking Court decree goes to the High Court within 30 days, on a security deposit equal to the decretal amount, heard by a bench of at least two judges within 90 days (s.22(1)). Claims above Rs 100 million, or involving an alleged criminal offence, are filed directly in the High Court rather than the Banking Court.
Ordinary civil courts (other commercial debt)
Non-banking commercial debt is pursued through the ordinary civil court hierarchy: Civil Courts, then District Courts, with the provincial High Court hearing appeals. Which level hears a given claim depends on its value against a pecuniary-jurisdiction threshold, and Pakistan sets these provincially and territorially rather than nationally. In Islamabad Capital Territory, the Civil Judge hears claims below Rs 50 million and the District Judge hears claims above that figure (Code of Civil Procedure (Amendment) Act 2019, s.6); the Sindh High Court's own original civil jurisdiction begins above Rs 65 million for general civil matters. Current figures for Punjab, Khyber Pakhtunkhwa and Balochistan were not located this session and should be confirmed when a claim is filed. Court fees for money suits are ad valorem, a percentage of the amount claimed, under the Court Fees Act 1870 s.7(i); the exact current provincial slab was not located.
Interest on the judgment
Pakistani courts have discretion, not a fixed statutory rate, to award interest under the Code of Civil Procedure 1908 s.34: pre-suit interest if it was claimed, interest for the period the case is pending, and post-decree interest, all "at such rate as the Court deems reasonable." If the decree is silent on interest, that is treated as a refusal, and no separate suit can be brought for it later.
Step 3 - How does debt enforcement work in Pakistan?
Once a Pakistani court issues a decree, the creditor applies to the same court for execution under the Code of Civil Procedure 1908, Order XXI, and the court's own enforcement process seizes and sells the debtor's assets to satisfy the debt.
How enforcement works
| Enforcement method | What it does |
|---|---|
| Attachment and sale of property | The court attaches and sells the debtor's movable or immovable assets to satisfy the decree |
| Garnishee-style attachment | The court attaches a debt a third party owes to the judgment-debtor, redirecting it to the creditor |
| Arrest and detention (CPC s.55) | Civil detention of the judgment-debtor in specific circumstances; women are exempt (s.56) |
CPC s.60 protects certain categories of the debtor's property from attachment regardless of the debt: wearing apparel, cooking vessels, tools of trade, part of their salary, and provident-fund deposits, among other statutory exemptions. Enforcement therefore targets the debtor's other assets and income first.
Time limit to apply for execution
An application for execution must be filed within six years of the date of the decree (CPC s.48). Pakistan has kept this six-year execution time-bar, so a creditor who lets a decree sit unenforced for longer risks losing the practical ability to enforce it.
Enforcement of Banking Court decrees
Decrees from the specialised Banking Courts, issued under the Financial Institutions (Recovery of Finances) Ordinance 2001, are enforced through the same CPC execution machinery once the 30-day appeal window (s.22(1)) has passed or the appeal has been decided.
Step 4 - How do insolvency procedures affect debt recovery in Pakistan?
Pakistan runs separate insolvency regimes for companies and for individuals, and which one applies changes how a creditor should proceed once a debtor cannot pay.
Corporate insolvency
A company can be wound up under the Companies Act 2017, administered by the Securities and Exchange Commission of Pakistan (SECP). Grounds for winding up sit in s.301, including inability to pay debts (clause (f)); a company is deemed unable to pay its debts under s.302 if a creditor owed more than Rs 100,000 goes unpaid, unsecured or uncompounded 30 days after a written demand at the registered office, or if execution on a decree returns unsatisfied, or if the court is satisfied on the evidence. Once a winding-up order is made, s.390 sets the ranked order of preferential payments, ahead of the general unsecured pool and floating-charge debenture-holders: federal, provincial and local-authority revenues due in the prior year; employees' wages and salary; accrued holiday remuneration; statutory insurance contributions; Workmen's Compensation Act 1923 amounts; provident, pension, gratuity and welfare-fund sums; and certain statutory-investigation costs. These ranks abate pro rata among themselves if assets are short, and any surplus after paying creditors is distributed to members. Watch item: SECP has proposed 183 amendments to the Companies Act 2017, still under government review and not yet enacted; no source ties the proposal to the winding-up or creditor-priority sections above, which remain current law.
In winding up an insolvent company, the same rules on secured and unsecured creditor rights, provable debts, and the valuation of contingent or future liabilities apply as under the general law of insolvency (Companies Act 2017 s.389).
Individual insolvency
Individual insolvency in Pakistan splits by region: the Insolvency (Karachi Division) Act 1909 applies in the former Karachi Division (Sindh), and the Provincial Insolvency Act 1920 applies elsewhere. A creditor can petition where the debt is at least Rs 500 and the debtor has committed an act of insolvency within the previous three months. On adjudication, the debtor's property vests in the Official Assignee, who realises and distributes it among creditors; discharge can be absolute, suspended or conditional, and is refused where the debtor committed an offence under the Act.
What this means for creditors
Once a debtor enters either process, individual enforcement action against them generally stops, and creditors must instead file a proof of claim within the process and wait for a distribution. Filing early, and keeping the contract, invoices and any written acknowledgement of the debt in order, improves the chance of a timely and accurate distribution once the estate is realised.
Fees, interest and who pays what in Pakistan
- Our fee: success-based, No Cure, No Pay (see pricing).
- Court & enforcement fees: only if the case escalates to legal action. Pakistani courts charge an ad valorem court fee, a percentage of the claim value, under the Court Fees Act 1870 s.7(i).
- Statutory debtor items: Pakistani courts have discretion under the Code of Civil Procedure 1908 s.34 to award interest, before, during and after the case, at a rate the court considers reasonable, where it is claimed.
- Who keeps what: recovered principal is yours; statutory court costs and any court-awarded interest follow local rules.
| Statutory cost item | Basis |
|---|---|
| Court fee (money suits) | Ad valorem, a percentage of the claim value (Court Fees Act 1870 s.7(i)); exact current slab varies by province |
| Judgment interest | Discretionary, at a rate the court considers reasonable (Code of Civil Procedure 1908 s.34) |
| Winding-up statutory demand | A creditor owed over Rs 100,000, unpaid 30 days after written demand, can found a winding-up petition (Companies Act 2017 s.302) |
Cross-border debt collection in Pakistan
Pakistan is not a member of the EU and is outside Debitura's European SDCA pricing group, so cross-border recovery here follows Pakistan's own domestic mechanism for foreign judgments rather than an EU instrument.
Under the Code of Civil Procedure 1908, s.44A, a judgment from a court in a country the Federal Government has formally notified as a "reciprocating territory" can be enforced directly in Pakistan by execution proceedings, without bringing a fresh suit. A judgment from a country that is not on that notified list has no such direct route: the creditor must instead sue on the foreign judgment afresh in a Pakistani court, using it as evidence of the underlying debt, subject to the ordinary limitation and procedural rules that apply to any civil claim. Creditors pursuing a debtor in Pakistan from abroad should confirm, before relying on s.44A, whether the judgment's country of origin currently appears on the Federal Government's reciprocating-territory notification.
Find a Local Debt Collection Lawyer
Need court-ready representation? Share your case once and receive up to three proposals from vetted litigation attorneys. Free, fast, and with no commitment.
- Verified specialists
- Quotes in 24 h, no hidden fees
- Fair, pre-negotiated rates
GNS Law Associates is a premier law firm in Karachi offering effective debt collection services in Pakistan, positioned as the go-to partner for debt recovery since 2013, with accolades like the "Best Real Estate Disputes & Procurement Practice 2024" and membership in the Sindh Bar Council.
ASC & Co. is a premier law firm in Lahore offering effective Debt Collection services in Pakistan, positioning itself as the go-to partner for debt recovery since 2013, with a commitment to quality and recognized by multiple awards and memberships.
JA LEGAL is a premier law firm in Lahore offering effective Debt Collection services in Pakistan, positioning itself as the go-to partner for debt recovery since 2020, with a reputation bolstered by industry accolades and esteemed memberships.
Al Fatima Law Associates is a premier law firm in Gujrat offering effective Debt Collection services in Pakistan, positioning the firm as the go-to partner for debt recovery since 2016, with accolades as a top-rated agency and memberships in leading bar councils.
Jurist Panel is a premier law firm in Lahore offering effective Debt Collection services in Pakistan, positioning itself as the go-to partner for debt recovery with a presence in the UK, founded in 2014, and recognized with multiple awards and memberships.
RMC Solutions Pvt Ltd is a premier debt recovery agency in Shah Faisal Colony offering effective Debt Collection services in Pakistan, positioning the firm as a trusted partner since 2023, with global reach and membership in the Pakistan Banks Association.


International Receivable Management Services is a premier debt recovery agency in Karachi offering effective debt collection services in Pakistan, established in 2008, operating on a no-collection, no-commission basis, and serving Europe, America, and Asia with award-winning expertise.
International Credit Information Limited is a premier debt recovery agency in Karachi offering effective Debt Collection services in Pakistan, established in 1998, serving 100 countries, and an ACA International member, ensuring reliable and comprehensive solutions for businesses.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.