Empresa de cobrança de dívidas na França - Sem sucesso, sem honorários.
Stop chasing overdue invoices in France. Your claim goes to Cabinet d'Ormane, France's licensed collection specialist (cabinet de recouvrement de créances), on a No Cure, No Pay basis with zero upfront cost. Submit your claim in minutes and track progress in real time through Debitura's platform.


Obter aconselhamento especializado grátis
Resposta de um especialista em 24 horas.
Por que a Debitura na França
Recuperação de crédito rápida, simples e sem riscos na França.
Debitura connects you to Cabinet d'Ormane, a licensed Paris-based debt collection specialist founded in 1956 and a member of Le SAR (Syndicat des Acteurs du Recouvrement). Cabinet d'Ormane runs your amicable collection in France on a No Cure, No Pay basis, while Debitura's platform keeps you in control of every step.
- Risk-free: pay nothing unless we recover
- Quick setup: submit your claim in minutes
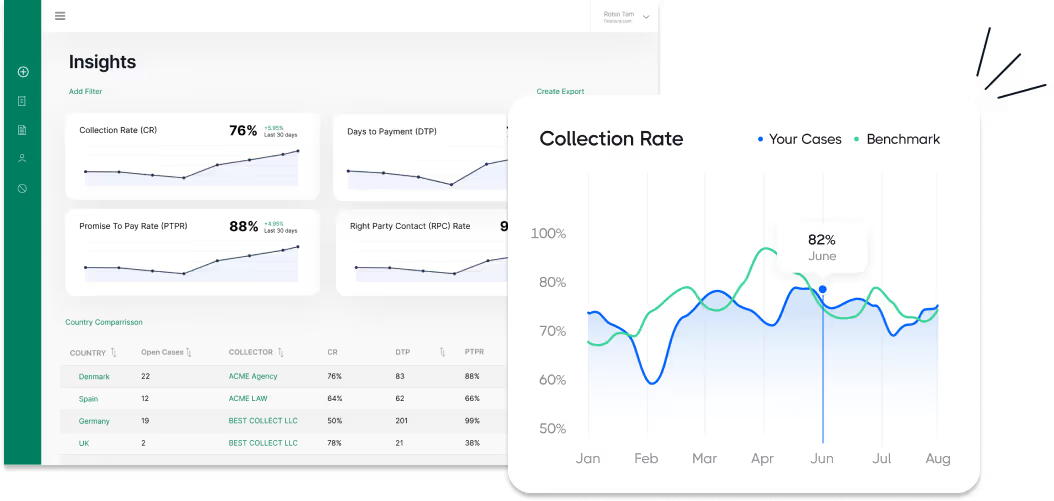
- Real-time tracking: monitor every case from your dashboard
- Local expertise: a licensed partner who knows French debt-collection law
Ready to start? Submit your claim and Cabinet d'Ormane can begin working your France case today.
Comece a recuperar seus processos na França em 2 minutos.
- Submit your claim: upload via dashboard, REST API, or ERP integrations such as Sage, Cegid, and SAP Business One.
- Local collection begins: Cabinet d'Ormane contacts the debtor in French within 48 hours, opening the recouvrement amiable (amicable collection) process.
- Get paid: funds are remitted once recovered. If needed, optional legal escalation follows the injonction de payer (payment order) procedure, always with a fixed-price quote you approve first.

Preços transparentes e baseados no sucesso
Com a Debitura, você só paga se tivermos sucesso. A cobrança pré-judicial funciona no modelo 'sem sucesso, sem honorários': uma Comissão de sucesso é deduzida dos valores recuperados, faturada localmente pelo seu parceiro. As taxas dependem do país do devedor, não do seu.
- Devedores na Europa (UE, Islândia, Liechtenstein, Noruega, Reino Unido e Suíça): Comissões de sucesso a partir de 6%, dependendo do valor do crédito.
- Devedores no resto do mundo: Comissões de sucesso a partir de 7,5%, dependendo do valor do crédito.
- Créditos mais antigos: uma sobretaxa é aplicada para créditos com 12 a 24 meses de atraso e para créditos com mais de 24 meses.
- Ação judicial é opcional: você aprova orçamentos de preço fixo antes de qualquer gasto judicial.
Consulte a página de preços para a tabela completa de taxas, ou obtenha uma estimativa instantânea ao enviar um pedido de cobrança.
Como funciona a recuperação de crédito em França?
Debt collection in France starts with an amicable phase run locally by Cabinet d'Ormane: a payment reminder followed by a formal demand aimed at full payment or a written acknowledgement of the debt. Most undisputed claims resolve at this stage. If the debtor still does not pay, escalation is never automatic. Your partner assesses the legal route and you approve a fixed-price quote before any court step.
- Submit your claim in 2 minutes online
- Local, licensed action from day one
- No Cure, No Pay, you owe nothing until we recover
- You approve every escalation, nothing happens without you
- Get paid directly when funds are recovered
Os quatro passos da fatura não paga ao dinheiro recuperado
- Step 1, Amicable collection: a reminder and a formal demand, handled locally by Cabinet d'Ormane. Most undisputed claims resolve here, without going to court.
- Etapa 2, Título executório: se o devedor ainda não pagar, seu parceiro avalia a via legal para obter um título executório, e você aprova um orçamento de preço fixo antes que qualquer coisa prossiga.
- Step 3, Enforcement: with an enforceable title, the enforcement authority can freeze bank accounts, garnish wages, and seize and sell assets until the claim is recovered.
- Step 4, Insolvency: if the debtor cannot pay, your proof of claim is filed in the collective insolvency procedure, and any distribution is monitored on your behalf.
Cada etapa é acompanhada no seu painel de controlo, e nada avança sem a sua aprovação. Os detalhes legais completos para França seguem no guia abaixo.

Recuperação de crédito em França - o guia completo de 2026
This Debt Collection France guide is built for creditors, in-house counsel and finance teams collecting from debtors in France. It covers the laws and courts, who does what, the amicable phase, the injonction de payer (the payment order procedure) route to an enforceable title, enforcement by the commissaire de justice (the judicial officer), insolvency, and cross-border recovery.
Nesta página:
Por que você pode confiar neste guia
At Debitura, we uphold the highest standards of impartiality and precision to bring you comprehensive guides on international debt collection. Every guide is written from primary legal sources and reviewed by licensed local experts in the jurisdiction it covers.
Perguntas ou feedback? Envie-nos um e-mail para contact@debitura.com , atualizamos este guia com base na sua contribuição.
Debitura em Números:
- 767 licensed partners - collection agencies and law firms in our network
- 180 countries covered - with cases handled in 174 of them
- 5,306 businesses registered with Debitura
- 33 days median time to first payment on European cases
Liderado por especialistas, validado localmente
Escrito por Lars Holdgaard, Fundador da Debitura (+10 anos em recuperação global de dívidas B2B). Cada página é revista por advogados locais de topo para garantir a precisão legal e passos práticos que pode utilizar.
Especialistas locais contribuintes:
Última atualização:

Recuperação de crédito em França - respostas rápidas
Debt Collection France runs on a fast, largely paper-based order-for-payment route, a simplified small-claims track run by the commissaire de justice (the judicial officer, formerly huissier de justice), and EU-based late-payment protection for businesses.
Quanto custa a recuperação de crédito em França?
Pre-legal collection in France is commonly success-based, No Cure, No Pay, and escalating to the injonction de payer costs a fixed 30.23 euro registry fee before the tribunal de commerce (the Commercial Court, or the tribunal des activités économiques in the 12 courts piloting that structure) for a commercial claim; filing is free at the tribunal judiciaire for a civil claim. A court can also order the debtor to bear the creditor's costs, including a contribution to legal fees under article 700 of the Code de procédure civile. For a B2B debt, a fixed 40 euro recovery indemnity is added automatically, and further justified recovery costs above that amount can also be claimed if the creditor can show them. Charging any recovery cost to a consumer debtor, by contrast, is a criminal offense in France.
Quanto tempo leva a cobrança de dívidas na França?
An uncontested injonction de payer is decided on the file without a hearing, and the debtor then has one month from service to lodge opposition. Since a February 2026 reform, the creditor must now serve the order within three months of its date, down from six, or it lapses; if no opposition arrives within two months of service, the creditor can move straight to forced execution. Where the debt is genuinely disputed, an ordinary lawsuit (assignation en paiement) before the tribunal judiciaire takes longer, and a référé-provision can secure an interim payment faster where the debt is not seriously contestable.
Quais são os prazos de prescrição e as regras de juros na França?
The general limitation period for a commercial or civil debt is five years from the date the creditor knew or should have known the facts allowing the claim (Code civil, the Civil Code, article 2224); a professional's claim against a consumer for goods or services supplied is shorter, at two years (Code de la consommation, the Consumer Code, article L218-2). Late-payment interest runs at the statutory rate (taux d'intérêt légal), reset every six months: for the second half of 2026 it is 2.75% for a professional debtor and 6.84% for an individual. Between two businesses, the contract can instead set its own late-payment rate, provided it is at least three times the statutory rate, or the interest defaults to the European Central Bank's main refinancing rate plus 10 points. Contractual payment terms are capped at 30 days from receipt of the goods or services, or 60 days from the invoice date if both parties agree. On top of interest, a business debtor automatically owes a fixed 40 euro recovery indemnity (Code de commerce, article L441-10); this indemnity, like the penalty rate itself, never applies against a consumer debtor.
| Tópico | Regra |
|---|---|
| Prescrição geral | 5 anos a partir da data de vencimento (Code civil art. 2224). |
| Consumer (B2C) limitation | 2 years for a professional's claim against a consumer (Code de la consommation art. L218-2). |
| Late-payment interest, H2 2026 | 2.75% professional debtor / 6.84% individual debtor, reset every six months. |
| Indenização de recuperação B2B | Fixed EUR 40, automatic, B2B/B2G only (Code de commerce art. L441-10). |
| Commercial-route filing fee | EUR 30.23 registry fee (injonction de payer, tribunal de commerce/TAE). |
Quais documentos são necessários para cobrar uma dívida na França?
Keep the contract or purchase order, the invoices and statement of account, proof of delivery or performance, and all correspondence with the debtor. The injonction de payer is started by a written application (requête) supported by this evidence, with no hearing required, so a complete and well-organised file speeds up the decision.
Qual caminho meu Processo deve seguir na França?
A fixed, contractual money debt suits the injonction de payer (the payment order procedure). A claim of no more than 5,000 euro against a consumer or a mixed debtor can instead go through the simplified small-claims recovery run directly by a commissaire de justice, with no judge involved, though this route excludes an invoiced claim between two merchants. Where the debt is not seriously contestable but money is needed quickly, a référé-provision can secure an interim payment after a short hearing. A genuinely disputed claim goes to an ordinary lawsuit (assignation en paiement) before the tribunal judiciaire, and a cross-border EU claim can use the European Payment Order instead.
Quem faz o quê na cobrança de dívidas na França?
A Debt Collection Agency France engagement typically combines amicable recovery, the courts for an enforceable title, and the commissaire de justice (the judicial officer) for enforcement. Debitura connects you to all three stages through Cabinet d'Ormane, a licensed Paris-based partner.
Agências de cobrança na França
Amicable recovery can be run in-house or by a recovery company (société de recouvrement, a debt collection agency), regulated under the Code des procédures civiles d'exécution (the Code of Civil Enforcement Procedures), articles R124-1 to R124-7: mandatory professional-liability insurance, a dedicated client account, a written creditor agreement, and prescribed content in the debtor letter. Agencies are also subject to oversight by the DGCCRF (the consumer-protection and market-oversight authority), which can inspect compliance with these rules and enforces the criminal penalty for billing recovery costs to a consumer debtor. Fees for amicable work stay with the creditor and are never billed to the debtor unless the law or a court allows it. A commissaire de justice can also run amicable recovery and the simplified small-claims track described below.
O commissaire de justice
The commissaire de justice is the single bailiff profession created on 1 July 2022 by merging the former huissier de justice (process server) and commissaire-priseur judiciaire (judicial auctioneer). The commissaire serves court documents, runs the simplified small-claims recovery for debts up to 5,000 euro, and enforces titres exécutoires (enforceable titles) through bank attachment, wage garnishment and asset seizure.
Advogados na França
A lawyer (avocat) is not required to file an injonction de payer. Above a certain claim value, instructing an avocat before the tribunal judiciaire becomes mandatory once the debtor opposes and the case goes to an ordinary hearing; below that threshold, a party can represent itself. Debitura's advantage: Cabinet d'Ormane assesses the dispute and coordinates any required lawyer instruction, so you never have to find and vet French counsel yourself.
Quais leis e tribunais se aplicam à cobrança de dívidas na França?
French debt recovery runs on the Code de procédure civile (the Code of Civil Procedure) and the Code civil (the Civil Code), with a dedicated enforcement code and EU instruments layered on top for cross-border claims.
O sistema judicial civil na França
Money claims go to the tribunal judiciaire (the ordinary civil court), which has handled all first-instance civil and commercial claims nationally since 1 January 2020, when it was created by merging the former tribunal d'instance and tribunal de grande instance. A commercial claim between traders instead goes to the tribunal de commerce (the Commercial Court); in Alsace-Moselle, which has no tribunal de commerce, the commercial chamber of the tribunal judiciaire hears these cases. Twelve courts, including Paris, are piloting a replacement structure, the tribunal des activités économiques, from 2025 to 2028, with jurisdiction extended to agricultural operators, non-regulated liberal professions and civil associations. For a claim of 5,000 euro or less, the juge des contentieux de la protection (the consumer and protection judge) decides with no right of appeal.
Legislação principal na França
- Code de procédure civile (the Code of Civil Procedure): the injonction de payer, articles 1405 to 1425, with the service and forced-execution rules at articles 1411 and 1422 reformed in February 2026.
- Code des procédures civiles d'exécution (the Code of Civil Enforcement Procedures): amicable-collection regulation, articles R124-1 to R124-7, the simplified small-claims recovery, article L125-1, and a new business-to-business streamlined procedure, articles L126-1 to L126-6, enacted April 2026 but not yet operational.
- Code civil (the Civil Code): the general five-year limitation, article 2224.
- Code de la consommation (the Consumer Code): the shorter two-year limitation on a professional's claim against a consumer, article L218-2.
- Code de commerce (the Commercial Code): B2B late-payment penalties, article L441-10, and the insolvency procedures of Book VI.
Conduta e proteção de dados na França
Amicable collection agencies must carry professional-liability insurance and hold client funds in a dedicated account under the Code des procédures civiles d'exécution, and breaching the prescribed debtor-letter rules is punishable by a fifth-class fine. The DGCCRF (the consumer-protection authority) enforces a criminal penalty, up to two years' imprisonment and a 300,000 euro fine, against anyone who bills recovery costs to a consumer debtor outside narrow legal exceptions. A debtor's personal data must be handled under the EU General Data Protection Regulation, supervised in France by the CNIL (the National Commission for Information Technology and Civil Liberties).
Passo 1 - Como funciona a cobrança amigável (pré-judicial) de dívidas na França?
Amicable collection recovers an unpaid invoice without a lawsuit, through a reminder (relance) and, if that fails, a formal demand (mise en demeure). Neither step is legally required before suing, but the mise en demeure formally puts the debtor in default and triggers late-payment interest. The aim is full payment or a written acknowledgement of the debt, which can support a later claim if the debtor does not pay as promised.
| Fase | Ação |
|---|---|
| Lembrete (relance) | Invoice, due date and payment details restated to the debtor. |
| Notificação formal (mise en demeure) | By registered letter, by a commissaire de justice, or as set out in the contract. |
| Negociação | Settlement or an instalment plan, ideally acknowledged by the debtor in writing. |
| Escalação | File an injonction de payer, or a lawsuit if the claim is disputed. |
Como fazer uma notificação formal válida na França
Under the Code civil (the Civil Code), articles 1344 to 1345-3, a mise en demeure can be made in three ways: a sommation served by a commissaire de justice, a registered letter with acknowledgement of receipt (lettre recommandée avec accusé de réception) containing a sufficient formal demand, or a clause written into the contract itself. It puts the debtor formally in default and supports the creditor's claim for late-payment interest from that date.
Who bears the cost, B2B versus B2C
Between two businesses, a fixed 40 euro recovery indemnity applies automatically from day one of late payment, on top of statutory or contractual interest (Code de commerce, article L441-10 and D.441-5); no notice is required and the amount cumulates across invoices. Against a consumer debtor, the position reverses entirely: billing any recovery cost to a consumer is a criminal offense under French law, so amicable costs stay with the creditor except in narrow, legally defined cases.
Quando escalar o caso
Cabinet d'Ormane moves to escalation only with your approval. If the debtor still does not respond within a reasonable period after the mise en demeure, or disputes the debt without paying, the next step is either the injonction de payer for an undisputed fixed debt, or an ordinary lawsuit where the claim is genuinely contested.
Passo 2 - Como se obtém um título executivo na França?
To enforce a debt you need an enforceable title (titre exécutoire). France's fast route is the injonction de payer (the payment order procedure), with a simplified small-claims track and ordinary proceedings as alternatives.
O procedimento de injunção de pagamento (injonction de payer)
The creditor files a written application (requête) with the competent court. The procedure is non-adversarial: there is no hearing, and the judge decides on the file alone. It applies to a fixed claim of contractual or statutory origin, but not to maintenance payments or a bounced cheque. A commercial-route application carries a 30.23 euro registry fee; the civil route at the tribunal judiciaire is free. If granted, the order carries the enforcement formula (formule exécutoire) and becomes an enforceable title once served and unopposed.
Citação e oposição
Since a February 2026 reform, the order must be served on the debtor within three months of its date, down from six previously, or it becomes non avenue (void). The debtor then has one month from service to lodge opposition (opposition), unchanged by the reform, which sends the whole claim to an ordinary hearing. If no opposition is received within two months of service, the creditor can proceed straight to forced execution. A rejected application is not open to appeal, but the creditor can still bring an ordinary lawsuit instead.
Determinar o tribunal competente na França
The competent court is generally the one where the debtor lives or has its registered office. For a civil claim this is the tribunal judiciaire; for a commercial claim between traders, the tribunal de commerce (or, in 12 pilot courts including Paris, the tribunal des activités économiques, piloting a wider commercial-court jurisdiction from 2025 to 2028); in Alsace-Moselle, the commercial chamber of the tribunal judiciaire.
Mais sobre processos judiciais na França
Recuperação simplificada de Julgados de Paz e référé-provision
For a debt of 5,000 euro or less, a commissaire de justice can run the simplified small-claims recovery directly, with no judge involved: the debtor has one month to accept or refuse, silence counts as refusal, and on agreement the commissaire issues an enforceable title straight away (Code des procédures civiles d'exécution, article L125-1). This route excludes an invoiced claim between two merchants. Where money is needed quickly and the debt is not seriously contestable, a référé-provision can instead secure an interim payment after a short hearing.
A new business-to-business route, not yet usable
A 2026 statute (the "procédure de recouvrement des créances commerciales incontestées") creates a dedicated B2B route: a commissaire de justice serves a formal payment demand, and if the debtor neither pays nor contests it, the court clerk appends an enforcement formula after a purely formal check, with all costs shifting to the debtor. Its implementing decree was not yet published at the time of writing, so it is not yet usable.
Passo 3 - Como funciona a Execução de dívidas em França?
Enforcement of a titre exécutoire (an enforceable title) is carried out by a commissaire de justice (the judicial officer, formed from the 2022 merger of the huissier de justice and the commissaire-priseur judiciaire). The creditor chooses the measures that match the debtor's known assets, and the commissaire can be asked to investigate what the debtor owns before enforcement starts.
Formas de executar um crédito em França
- Bank attachment (saisie-attribution): the commissaire de justice seizes funds the debtor holds with a third party such as a bank, above a protected minimum pegged to the RSA (the minimum-income benefit) level; the debtor has one month to contest the seizure before the juge de l'exécution (the enforcement judge), after which the bank releases the funds to the creditor.
- Wage garnishment (saisie des rémunérations): de-judicialised to the commissaire de justice as of 1 July 2025 (previously run by the court); the commissaire notifies the debtor's employer and attaches wages above the legally protected minimum, in monthly instalments.
- Seizure and sale of movables (saisie-vente): the commissaire de justice seizes and sells the debtor's movable property, such as vehicles or equipment, at auction.
- Immovable property (saisie immobilière): for larger claims, real estate can be seized and sold under judicial supervision, a longer and more formal process reserved for significant debts.
O processo de execução em França
The creditor instructs the commissaire de justice with the enforceable title; the commissaire identifies the debtor's assets, chooses and applies the appropriate measure, and collects the funds. Proceeds are applied first to principal, then interest, then recoverable costs, with any surplus returned to the debtor. If a first measure recovers only part of the debt, the creditor can instruct further measures against any other assets the commissaire identifies, until the claim is satisfied or no further assets can be found.
Passo 4 - Como os procedimentos de insolvência afetam a recuperação de dívidas em França?
Where the debtor cannot meet its obligations, a collective insolvency procedure (procédure collective) becomes the route, and individual enforcement generally stops once it opens. France has three: sauvegarde (safeguard, opened before the debtor stops paying its debts, aimed at reorganising while still solvent), redressement judiciaire (judicial reorganisation, once the debtor is in cessation des paiements but recovery is still considered possible), and liquidation judiciaire (judicial liquidation, where recovery is no longer possible and the business winds up and its assets are sold).
When insolvency opens
Cessation des paiements (the French insolvency trigger, Code de commerce article L631-1) means the debtor's available assets, cash, bank balances, sight instruments and undrawn credit lines, can no longer cover its due and payable liabilities. There is no minimum debt threshold: it is a liquidity test, not a debt-size floor, unlike common-law statutory-demand systems. A debtor must file for redressement or liquidation judiciaire within 45 days of reaching this point (Code de commerce, article L631-4); filing late can expose the debtor's managers to personal liability. Traders and artisans file with the tribunal de commerce, or, in the 12 courts piloting the tribunal des activités économiques from 2025 to 2028, that court instead; the pilot also extends to agricultural operators, non-regulated liberal professions and civil associations, a wider pool than the traditional trader/artisan base.
Filing your proof of claim
An unsecured creditor must file a proof of claim (déclaration de créance) with the court-appointed mandataire judiciaire (the insolvency practitioner representing creditors) within two months of the opening judgment being published in the BODACC (the official register of commercial announcements), extended to four months for a creditor based outside mainland France. The claim should state the amount owed, its legal basis, and attach supporting documents.
Perder o prazo
A creditor who misses the filing deadline is barred (forclos) from the distribution and goes unpaid, unless not at fault: a request to be relieved from the bar (relevé de forclusion) can be filed with the juge-commissaire (the supervising judge) within six months of the BODACC publication, with the claim itself then declared within one month of a favourable decision.
Priority and likely outcomes
Employees' wages are guaranteed and paid first through the AGS wage-guarantee scheme, ahead of procedure costs and other creditors; secured creditors and the state generally rank ahead of ordinary unsecured trade creditors, who are often paid only pro rata from whatever remains once higher-ranked claims are satisfied. Lodge your claim on time, with the contract, invoices and statement of account, and monitor the verification of claims through your partner and the mandataire judiciaire.
Taxas, juros e quem paga o quê em França
- A nossa taxa: baseada no sucesso, sem recuperação, sem pagamento (ver preços).
- Court and enforcement fees: statutory court and enforcement fees, such as the 30.23 euro injonction de payer registry fee on the commercial route and the commissaire de justice's enforcement costs, apply only if the case escalates to legal action, and are generally recoverable from the debtor if you win, including a contribution to legal costs under article 700 of the Code de procédure civile.
- Statutory debtor items: for a business debt, late-payment interest runs at the statutory rate (taux d'intérêt légal, reset every six months; 2.75% for a professional debtor in the second half of 2026), or at a contractual rate if one is agreed and it is at least three times the statutory rate. On top of interest, a fixed 40 euro recovery indemnity applies automatically from the day after the due date (Code de commerce, article L441-10), and further justified recovery costs above 40 euro can also be claimed if the creditor documents them. None of these B2B costs can be billed to a consumer debtor.
- Who keeps what: the recovered principal is yours; interest and statutory costs follow the contract, the statute and the court's order.
Cobrança de dívidas transfronteiriça em França
France is a founding European Union member state, so for a claim against a debtor in another EU country, three EU instruments apply directly, without extra formalities. The European Payment Order (Regulation EC 1896/2006) gives a uniform order-for-payment route for an uncontested cross-border claim: filed on a standard form, it is typically decided within 30 days, and the debtor then has 30 days to oppose it before it becomes automatically enforceable. The European Small Claims Procedure (Regulation EC 861/2007) is a simplified written procedure for a cross-border claim of no more than 5,000 euro, available in every EU state except Denmark, and is open to a French creditor pursuing a debtor elsewhere in the EU or vice versa. A French judgment is recognised and enforced in another EU member state under the Brussels I Recast Regulation (EU 1215/2012): exequatur is abolished, so no separate declaration of enforceability is needed, only a standard certificate.
Encontre um Advogado de Recuperação de Crédito Local
Precisa de representação judicial? Compartilhe seu Processo uma vez e receba até três propostas de advogados litigantes verificados. Gratuito, rápido e sem compromisso.
- Especialistas verificados
- Orçamentos em 24 horas, sem taxas ocultas
- Taxas justas e pré-negociadas
A MERCURE Finances é uma empresa de cobrança de dívidas de primeira linha em Montrouge, que oferece serviços eficazes de cobrança de dívidas em França, fundada em 2003, operando com um modelo de honorários baseado no sucesso e reconhecida com prémios e filiações, incluindo a FENCA, servindo mais de 104 países.

O Cabinet FRANC é um escritório de advogados de primeira linha em Paris, que oferece serviços eficazes de cobrança de dívidas em França, estabelecido em 1991, com experiência internacional em toda a Europa e América do Norte, e membro do Barreau de Paris e do Barreau de Bruxelles.


O Cabinet d'Ormane é uma empresa de cobrança de dívidas de primeira linha em França, que oferece serviços eficazes de cobrança de dívidas sem risco, estabelecida em 1956, e conhecida pelo seu modelo Sem recuperação sem honorários; como parceiro exclusivo da Debitura, serve clientes em toda a França e internacionalmente.
A Gayssot Recouvrement é uma agência de recuperação de crédito de destaque em Lyon, que oferece serviços eficazes de cobrança de dívidas na França, posicionando-se como o parceiro ideal para a recuperação de crédito desde 2014, com foco em transparência e eficiência, e membro do Pacto Global das Nações Unidas.
Perguntas Frequentes
Explore nossas FAQs mais comuns abaixo, ou entre em contato diretamente em contact@debitura.com se precisar de ajuda com um Processo específico.