Debt Collection Agency in Czechia - No Win, No Fee
Your trusted Debt Collection Agency in Czechia. Submit your claim for quick, secure recovery. No initial cost! Gain insight from our comprehensive local debt collection practices guide.


Get free expert advice
Response from a specialist within 24 hours.
Why Choose Debitura for Debt Collection in Czechia
Fast, simple and risk-free debt collection in Czechia
Debitura connects you with FClegal (JUDr. Filip Cerny, Ph.D., advokat), a Prague-based collection partner licensed since 2013 (Ceska advokatni komora, Reg. 14944) and a member of the Czech Bar Association.
- Risk-free: Pay only when we recover your money.
- Quick setup: Submit invoices in a few clicks.
- Real-time tracking: Monitor progress live in one portal.
- Vetted partner: FClegal is licensed and performance-tracked by Debitura.
Start recovering your claims in Czechia in minutes
- Submit your claim: Upload your unpaid invoice through the Debitura dashboard, the REST API, or a plug-and-play ERP integration such as Xero or QuickBooks. Add supporting documents in a few clicks, with no paperwork and no setup fees.
- Local collection begins: Your case is assigned to FClegal (JUDr. Filip Cerny, Ph.D., advokat), who starts amicable contact with the debtor on your behalf. If court action is ever needed later, you choose from fixed-price legal quotes before anything proceeds, so nothing is spent without your consent.
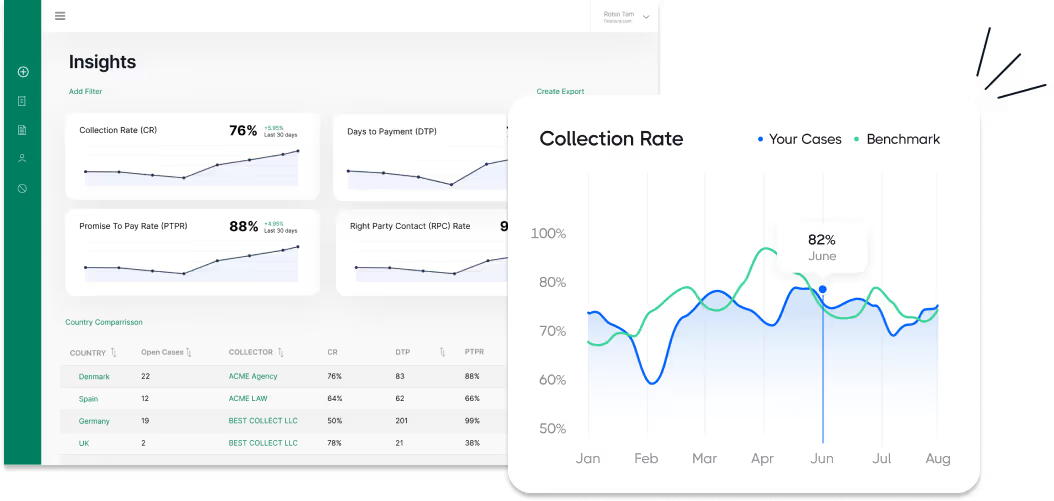
- Track and get paid: Follow every update in real time on your dashboard, from the first reminder to the final payment, with a notification at each milestone. Recovered funds are remitted to you as soon as they clear, and you only pay on success.

Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12–24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve fixed-price quotes before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Czechia?
Debt collection in Czechia starts with an amicable phase handled by a local, licensed partner: reminders and a formal payment demand, aimed at full payment or a written instalment agreement. Most straightforward claims are resolved at this stage. If the debtor still does not pay, escalation to court is a separate, approved step - never automatic.
The four steps from unpaid invoice to recovered cash
- Step 1 - Amicable collection: reminders, a formal payment demand and negotiation, handled locally by a local, licensed partner. Most undisputed claims are resolved in this phase, without going to court.
- Step 2 - Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title and you approve a fixed-price quote before anything proceeds.
- Step 3 - Enforcement: with a legal title, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Step 4 - Insolvency: if the debtor turns out to be insolvent, your proof of claim is filed and any distributions are monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Czechia - timelines, costs, courts and enforcement - follows in the guide below.

Debt collection in Czechia - the complete 2026 guide
This guide covers Debt Collection Czechia end to end: the amicable phase, obtaining an enforceable title, enforcement through a soudní exekutor (a private court-appointed bailiff), and insolvency, with the applicable law, timelines and costs at each step. Enforcement is regulated nationally by the Exekutorská komora (the Chamber of Executors), the professional body for soudní exekutoři.
On this page:
Why you can trust this guide
At Debitura, we uphold the highest standards of impartiality and precision to bring you comprehensive guides on international debt collection. Every guide is written from primary legal sources and reviewed by licensed local experts in the jurisdiction it covers.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 767 licensed partners - collection agencies and law firms in our network
- 180 countries covered - with cases handled in 174 of them
- 5,306 businesses registered with Debitura
- 33 days median time to first payment on European cases
Expert-led, locally validated
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery). Every page is reviewed by top local attorneys to ensure legal accuracy and practical steps you can use.
Contributing local experts:
Last updated:

Debt collection in Czechia - quick answers
How much does it cost to collect a debt in Czechia?
Debt Collection Czechia costs depend on the route used. Court fees are a flat CZK 1,000 for claims up to CZK 20,000, then 5% of the amount above that under the ordinary civil track (Act No. 549/1991 Coll. on Court Fees), capped at CZK 2,000,000. The electronic payment order (elektronický platební rozkaz) carries a lower court fee, 4% of the claim above CZK 20,000. Fees are payable by bank transfer, or by revenue stamp up to CZK 5,000 (not available for the electronic payment order); a lawyer's own fee, where one is engaged, carries standard Czech VAT. This CZK 2,000,000 cap on percentage-based court fees follows Section 6a(7) of the Court Fees Act, unless a specific fee-schedule item sets a different limit.
How long does a debt collection case take in Czechia?
An electronic payment order gives the debtor 15 days to pay or appeal after it is issued and becomes final and enforceable like a judgment if unopposed; a timely appeal cancels it and the case proceeds to an ordinary hearing instead. Ordinary civil proceedings at district courts averaged around 251 days nationally in 2023, ranging from about 180 days in South Bohemia to 304 days in Prague.
What is the limitation period for debt claims in Czechia?
The general limitation period for private-law claims, both consumer and business, is 3 years, subjective, from when the right could first be exercised (Section 629(1) of the občanský zákoník, the Civil Code), with a 10-year objective long-stop from maturity regardless of the creditor's awareness (Section 629(2)). Parties may contractually vary this period within statutory limits, up to a ceiling of around 15 years. Czechia has no separate B2B/B2C limitation split: before the 2014 recodification, the now-repealed Commercial Code gave business claims a longer 4-year period, but the unification of private law under the občanský zákoník (Act No. 89/2012 Coll., in force since 1 January 2014) erased that distinction, so consumer and business monetary claims now share this same framework.
What interest can I charge on a late payment in Czechia?
Where no interest rate is agreed in the contract, statutory default interest (úrok z prodlení) equals the Czech National Bank's (ČNB) 2-week repo rate valid on the first day of the calendar half-year in which the default began, plus 8 percentage points (Section 1970 of the občanský zákoník; formula set by Government Regulation No. 351/2013 Coll., Section 2). The ČNB's 2-week repo rate stood at 3.75% as of 19 June 2026, which puts statutory default interest at approximately 11.75% p.a. for defaults beginning in the second half of 2026; once fixed for a given default, this rate does not change even if the ČNB's repo rate later moves.
What documents do I need to collect a debt in Czechia?
A civil claim must state the parties' identifying details, the decisive facts, the evidence relied on, and the relief sought, with supporting documents attached in paper or electronic form. Companies, lawyers, and other specified professionals must generally file through their mandatory data box (datová schránka), while individuals may also file by certified electronic signature or by post.
Which legal route should I use to collect a debt in Czechia?
Czech law offers two routes to an enforceable title: the ordinary payment order (platební rozkaz) or full civil proceedings at the district court with jurisdiction over the debtor's registered office, and the electronic payment order, a simplified, form-based procedure filed via the ePodatelna portal. The electronic payment order previously carried a CZK 1,000,000 claim-value ceiling; Act No. 180/2024 Coll. removed that ceiling with effect from 1 July 2024, so it is now available for claims of any value, at a court fee of 4% of the claim above CZK 20,000 rather than the standard 5%. Legal representation is not mandatory for either route. Neither route is available where the defendant's residence is unknown, service would need to take place abroad, or the defendant lacks full legal capacity; such claims must proceed as ordinary civil litigation instead.
| Item | Ordinary claim | Electronic payment order |
|---|---|---|
| Court fee | CZK 1,000 flat up to CZK 20,000, then 5% | 4% of claim above CZK 20,000 (vs 5% standard) |
| Claim value limit | No cap | No cap (ceiling removed by Act No. 180/2024 Coll., effective 1 July 2024) |
| Debtor's response deadline | Set by court schedule | 15 days to pay or appeal |
Who does what in Czechia debt collection?
Three types of actors handle debt collection in Czechia: collection agencies for the amicable phase, soudní exekutoři (private, court-appointed bailiffs) for enforcement, and lawyers (advokáti) once a case reaches court.
Debt collection agencies
Collection agencies handle the pre-legal phase: sending reminders, making calls and negotiating repayment with the debtor. There is no dedicated licensing regime for ordinary commercial or consumer debt collection in Czechia; agencies operate under the general trade-licensing law (živnostenský zákon). A narrower activity is separately regulated: servicing or purchasing non-performing loans originated by a bank or credit institution requires a Czech National Bank (ČNB) licence under Act No. 84/2024 Coll. on the market with non-performing loans, in force since 1 May 2024 and transposing EU Directive 2021/2167. This licence applies only to bank-originated non-performing debt, not to general commercial debt collection.
Bailiffs (soudní exekutoři)
Enforcement is carried out by soudní exekutoři, private, state-authorised bailiffs who act only once a creditor holds an enforceable title. They locate and seize the debtor's assets, including wages and bank funds, under the exekuční řád (the Enforcement Code, Act No. 120/2001 Coll.). Bailiffs are professionally organised under the Exekutorská komora (the Chamber of Executors), the profession's own regulatory body.
Lawyers (advokáti)
Lawyers become involved once a case moves to court: drafting the claim, representing the creditor, and advising on the choice between the ordinary payment order, the electronic payment order, or full civil proceedings. Legal representation is not mandatory in Czech civil proceedings, but it becomes more common once a case is contested.
Which laws and courts apply to debt collection in Czechia?
Debt collection in Czechia runs through a three-tier civil court system, under the občanský zákoník and the Civil Procedure Code, with separate legislation covering consumer protection, insolvency and enforcement.
Civil court system
Okresní soudy (district courts) are the first-instance court for most civil and debt claims, including the ordinary and electronic payment order. Krajské soudy (regional courts) hear appeals from district-court decisions and act as first instance for larger commercial disputes. The Nejvyšší soud (Supreme Court, in Brno) rules on extraordinary remedies such as dovolání, an appeal on a point of law. The Supreme Administrative Court and the Constitutional Court sit separately from this civil hierarchy and are not part of ordinary debt-collection litigation.
Key legislation
- Občanský zákoník (Act No. 89/2012 Coll.): in force since 1 January 2014, it sets out contractual obligations, limitation periods and default interest, and unified the former Civil Code and Commercial Code into one private-law framework, so consumer and business monetary claims now follow the same rules rather than the separate, longer business limitation period that existed before 2014.
- Consumer protection legislation: aligned with EU Directive 2005/29/EC on unfair commercial practices, it restricts aggressive or deceptive collection conduct and allows fines of up to CZK 5 million for violations.
- Insolvenční zákon (the Insolvency Act, Act No. 182/2006 Coll.): governs reorganisation and liquidation once a debtor cannot pay, including the fixed order in which creditors are repaid.
Civil procedure and court fees
Civil litigation procedure, including the payment-order routes described later in this guide, is set out in the Code of Civil Procedure (občanský soudní řád, Act No. 99/1963 Coll.). Court fees follow the zákon o soudních poplatcích (the Act on Court Fees, Act No. 549/1991 Coll.); percentage-based fees generally cap at CZK 2,000,000 unless a specific fee-schedule item sets a different limit (Section 6a(7)). Fees up to CZK 5,000 may be paid by revenue stamp (kolek) instead of bank transfer, except for the electronic payment order fee, which cannot be paid this way (Section 8).
Licensing note
Ordinary commercial and consumer debt collection has no dedicated licence in Czechia; it operates under general trade-licensing law. Servicing or purchasing non-performing loans originated by a bank is separately licensed by the ČNB under Act No. 84/2024 Coll. (see who does what, above).
Step 1 - How does amicable (pre-legal) debt collection work in Czechia?
Amicable collection in Czechia starts with payment reminders and a formal written demand, aimed at securing full payment or an agreed instalment plan without going to court. Most undisputed claims are resolved at this stage.
The pre-action demand letter
Sending a payment demand at least 7 days before filing a claim preserves the creditor's right to recover litigation costs if the case later goes to court (Section 142a of the Civil Procedure Code). Skipping this step can mean the creditor bears its own legal costs even after winning.
The demand should be addressed to the debtor's address for service or, absent one, their last known address, since Section 142a requires proof that a compliant demand was sent before the claim was filed.
What amicable collection covers
Typical amicable steps include identifying the debtor and the exact amount owed, sending reminders and a formal demand, and negotiating a repayment schedule where the debtor disputes ability to pay rather than liability. Statutory default interest and reasonable, evidenced collection costs can be added to the amount claimed where Czech law allows. Interest accrues under Section 1970 of the občanský zákoník from the due date, at the government-set rate absent contractual agreement: the Czech National Bank's 2-week repo rate on the first day of the calendar half-year in which the default began, plus 8 percentage points (Government Regulation No. 351/2013 Coll., Section 2).
When to escalate
Escalation to court is appropriate when the debtor does not respond, repeatedly breaks payment promises, or disputes the debt without engaging further. Escalation is a separate, deliberate step: it requires assessing the applicable route, an ordinary or electronic payment order, or full civil proceedings, before a claim is filed (see Step 2 below). If the debtor's residence is unknown, only ordinary proceedings are available, not a payment order.
Step 2 - How do you obtain an enforceable title in Czechia?
Czech law gives creditors two main routes to an enforceable title: a payment order for straightforward, well-documented claims, or ordinary civil proceedings for disputed or complex claims.
Ordinary payment order (platební rozkaz)
Under Sections 172-174 of the Civil Procedure Code, a district court can issue a platební rozkaz without a hearing where the claim is based on clearly stated facts. The debtor has 15 days to pay or lodge an odpor (opposition). A timely odpor from any one defendant cancels the payment order entirely and the case proceeds to an ordinary hearing; if no odpor is lodged, the order becomes final with the effect of a judgment. A payment order is not available where the defendant's residence is unknown, service would need to take place abroad, or the defendant lacks full legal capacity; such claims proceed as ordinary civil litigation instead.
Electronic payment order (elektronický platební rozkaz)
Under Section 174a of the Civil Procedure Code, the electronic payment order is a simplified, form-based procedure filed via the ePodatelna portal, on the same 15-day pay-or-appeal timeline. Act No. 180/2024 Coll. removed the previous CZK 1,000,000 claim-value ceiling with effect from 1 July 2024, so it is now available for claims of any value, at a lower court fee, 4% of the claim above CZK 20,000, against 5% for the ordinary track.
Ordinary civil proceedings
Where the claim is disputed, or a payment order is not appropriate, the case proceeds as ordinary civil litigation at the district court with jurisdiction over the debtor's registered office. Legal representation is not mandatory, though it is common once a case is contested. Ordinary proceedings take materially longer than an unopposed payment order; see the quick answers above for average timelines.
More on court proceedings in Czechia
Choosing between the two payment-order routes
Creditors with an undisputed, well-evidenced claim generally choose whichever payment order suits their filing channel; since the July 2024 reform, claim value alone no longer rules out the electronic route. Claims likely to be contested, or needing more evidence than a payment order allows, are better filed as ordinary proceedings from the outset.
Enforceable title in practice
An unopposed payment order, or a final judgment from ordinary proceedings, is the enforceable title a soudní exekutor needs to begin enforcement (see Step 3 below). Creditors should keep the original title and proof of service, since the bailiff's application relies on them.
Step 3 - How does debt enforcement work in Czechia?
Once a creditor holds an enforceable title, an unopposed payment order or a final judgment, enforcement in Czechia is carried out by a soudní exekutor: a private, state-authorised bailiff appointed under the exekuční řád (the Enforcement Code, Act No. 120/2001 Coll.).
How enforcement is initiated
The creditor files the enforceable title with a soudní exekutor of their choice. The exekutor applies to the court for authorisation to proceed, which the court decides within 15 days. Once authorised, the exekutor locates the debtor's assets and issues an enforcement order.
Notification and asset freeze
The debtor is notified of the enforcement order and, from that point, is placed under a general freeze on assets and bank accounts, which prevents disposals that would defeat the creditor's claim. Exceptions to this freeze exist for the debtor's basic living needs and for continuing an ongoing business, so day-to-day operations are not entirely halted.
Forced collection
If the debtor does not settle or successfully challenge the enforcement order, forced collection, such as wage garnishment, bank account attachment, or seizure and sale of other assets, follows after approximately 30 days. The exekutor's own fee follows its own statutory tariff, in addition to the court and legal costs already incurred in obtaining the title. Czech law terms these methods srážky ze mzdy (wage deductions), přikázání pohledávky (attachment of a receivable, such as a bank account), and seizure or sale of movable or immovable property.
Acknowledgement of debt and limitation
An acknowledgement of debt (uznání dluhu) restarts the limitation clock with a fresh 10-year period (Section 639 of the občanský zákoník); a court-recognised debt likewise carries its own 10-year limitation period running from the due date set in the decision (Section 640), giving creditors a longer window to pursue enforcement once a title exists.
Costs
Enforcement costs typically include the exekutor's statutory fee, the court fees already paid to obtain the title, and any legal representation costs, generally recoverable from the debtor under the loser-pays principle once enforcement succeeds.
The case closes once the debt is fully satisfied, at which point the exekutor notifies the relevant registries and institutions that enforcement has ended. This tariff, known as the odměna exekutora, is fixed by separate implementing regulation rather than by the court that issued the underlying title.
Step 4 - How do insolvency procedures affect debt recovery in Czechia?
Insolvency in Czechia is governed by the insolvenční zákon (the Insolvency Act, Act No. 182/2006 Coll.). Proceedings can be opened by the debtor or by a creditor, and become relevant to debt recovery when a debtor's assets are insufficient for enforcement to succeed on its own.
Filing threshold
Under Section 3, insolvency can be declared where the debtor has more than one creditor, obligations more than 30 days overdue, and is unable to pay them. Proceedings are published in the insolvency register, with set deadlines for creditors to lodge their claims.
Indicators of platební neschopnost (inability to pay) under Section 3 include the debtor having stopped paying a substantial part of its debts, being more than 3 months overdue on its obligations, a creditor's enforcement against the debtor having failed to recover the amount owed, or the debtor's failure to comply with a court-ordered financial-disclosure requirement.
Other grounds for insolvency
Legal entities and entrepreneurs can also be in úpadek through předlužení (over-indebtedness), where liabilities exceed the value of their assets, taking into account the prospect of continued operation (Section 3). Separately, hrozící úpadek (imminent insolvency) lets a debtor file earlier, before payments are missed, where it can reasonably be foreseen that they will be unable to meet a substantial part of their obligations on time.
Priority of claims (Sections 167-172)
Distributions follow a fixed order: secured claims are satisfied first from their collateral; then claims against the estate, such as administration costs, paid in full whenever funds allow; then a group of estate-ranked claims paid pari passu, covering employee wages, health-damage claims and spousal support; then ordinary unsecured claims, paid pro rata from what remains; and subordinated claims last, only if funds remain after every other category. Section 170 also excludes certain claims from satisfaction altogether: interest accruing after proceedings opened, contractual penalties, and gift obligations.
Personal insolvency discharge (oddlužení)
For individual debtors, the personal discharge track (oddlužení) was shortened from 5 to 3 years by a reform effective 1 October 2024. The discharge outcome depends on a satisfaction rate the court sets in advance for the debtor's case, and the track can be extended by up to 12 months for a serious breach of its conditions. Repeat discharges within a period of a prior oddlužení are restricted, though the exact waiting period is not stated here.
What this means for creditors
Creditors should lodge their claim within the deadline set by the insolvency court to secure their place in the relevant priority category above. In an oddlužení case, the debtor's repayments to unsecured creditors run against the court-set predicted satisfaction rate for the 3-year, or extended, track, rather than against the full original claim.
Fees, interest and who pays what in Czechia
- Our fee: success-based - No Cure, No Pay (see pricing).
- Court & enforcement fees: state fees apply only if the case escalates to legal action.
- Statutory debtor items: late-payment interest and recoverable collection costs are added to the debt where the law allows.
- Who keeps what: recovered principal is yours; statutory costs and interest follow local rules.
Court fees and cost recovery
Where a case escalates, court fees follow Act No. 549/1991 Coll.: CZK 1,000 flat up to CZK 20,000, then 5% above under the ordinary track, or 4% above CZK 20,000 via the electronic payment order (elektronický platební rozkaz). Under the loser-pays principle (Section 142 of the Civil Procedure Code), a creditor who succeeds in full is normally reimbursed these costs by the debtor; partial success is reimbursed proportionally. Sending a payment demand at least 7 days before filing preserves this cost-recovery right (Section 142a).
Statutory default interest
Where no rate is agreed, statutory default interest (úrok z prodlení) equals the Czech National Bank's 2-week repo rate on the first day of the half-year in which default began, plus 8 percentage points (Section 1970 of the občanský zákoník; Government Regulation No. 351/2013 Coll., Section 2). The repo rate was 3.75% as of 19 June 2026, putting default interest at roughly 11.75% per year currently.
Cross-border debt collection in Czechia
As an EU member state, Czechia gives creditors access to three EU cross-border recovery instruments alongside its domestic procedures (see Step 2 above for the domestic routes).
Brussels I recast (Regulation (EU) No. 1215/2012)
A judgment obtained in another EU member state is recognised and enforceable in Czechia without an exequatur, a separate declaration of enforceability, which simplifies cross-border enforcement of EU judgments.
European Payment Order (Regulation (EC) No. 1896/2006)
For uncontested cross-border claims, the European Payment Order procedure is available with no cap on claim value, offering a standardised alternative to a national payment order when the debtor is in another EU country.
European Small Claims Procedure (Regulation (EC) No. 861/2007, as amended)
For cross-border claims, contested or uncontested, the European Small Claims Procedure (ESCP) offers a simplified, largely form-based process. The claim-value ceiling was raised from EUR 2,000 to EUR 5,000 in 2017. The procedure applies only to cross-border cases, not to domestic Czech disputes.
Find a Local Debt Collection Lawyer
Need court-ready representation? Share your case once and receive up to three proposals from vetted litigation attorneys. Free, fast, and with no commitment.
- Verified specialists
- Quotes in 24 h, no hidden fees
- Fair, pre-negotiated rates
GHS Legal, s.r.o. is a premier law firm in Bratislava offering effective Debt Collection services in Slovakia, positioning itself as the go-to partner with a foundation in 2011, accolades in public procurement, and services extending to the Czech Republic and Austria.


JUDr. Filip Černý, Ph.D., Advokát / FClegal is a premier law firm in the Czech Republic offering effective risk-free Debt Collection services; founded in 2013, the firm is an exclusive Debitura partner, providing No Cure No Pay collections based on Debitura's risk-free standard terms and pricing.
ModerniPravnik.cz is a premier law firm in Praha offering effective Debt Collection services in the Czech Republic, positioning itself as the go-to partner for debt recovery with transparent pricing, a satisfaction guarantee, and membership in the Czech Bar Association.
MACEK.LEGAL s.r.o., advokatni kancelar is a premier law firm in Praha offering effective Debt Collection services in the Czech Republic, established in 2007, known for transparent pricing and memberships in prestigious organizations, serving the EU and beyond.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.