Debt Collection Agency in Indonesia - No Win, No Fee
Your claims are handled exclusively by Hendarman Law Firm, our PERADI-licensed partner law firm for debt collection (penagihan utang) in Indonesia. Submit your claim in minutes, track progress in real time, and pay only when your money is recovered.


Get free expert advice
Response from a specialist within 24 hours.
Why Choose Debitura for Debt Collection in Indonesia
Risk-free debt collection in Indonesia
Debitura recovers unpaid invoices from debtors in Indonesia through our platform: submit your claim, track it in real time, and pay only when money comes in. Debitura is the platform; the regulated work in Indonesia is performed by our exclusive local partner, Hendarman Law Firm, a Jakarta law firm established in 2011 with a team of 16 legal professionals and more than five litigation partners, licensed by PERADI.
- Risk-free: Pay only when we recover your money.
- Quick setup: Submit invoices in a few clicks.
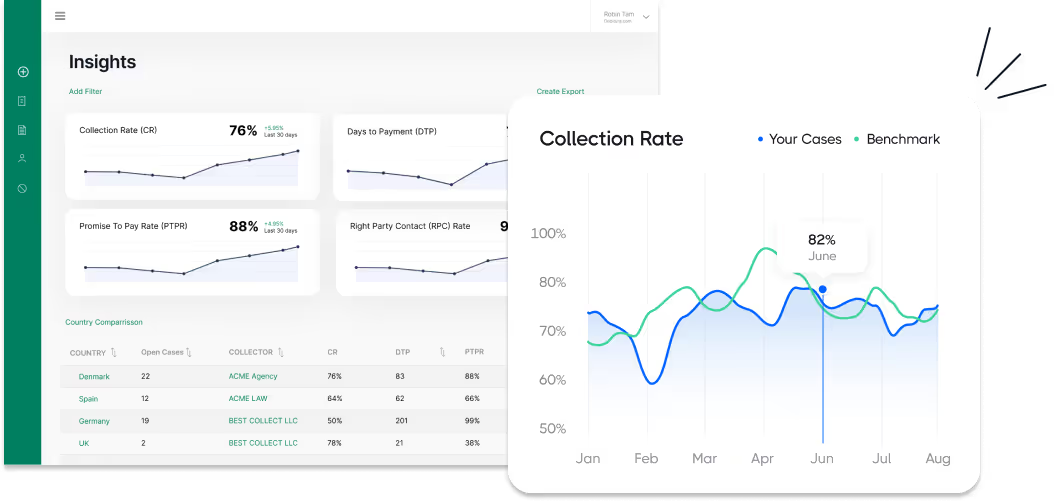
- Real-time tracking: Monitor progress live in one portal.
- Local expertise: PERADI-licensed Indonesian advocates handle the somasi and any court step.
Getting started with debt collection in Indonesia
- Upload your claim: Submit your invoice and debtor details through Debitura's secure dashboard in just 2 minutes.
- Hendarman Law Firm takes action: Our Indonesian partner begins amicable collection (penagihan secara kekeluargaan), sending formal demand letters (somasi) under Indonesian Civil Code.
- Track and recover: Follow real-time updates in your dashboard. You pay only when funds are recovered.
Already using an ERP or accounting system? Connect via API or use our one-click integrations to sync claims automatically.

Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12–24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve fixed-price quotes before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Indonesia?
Debt collection in Indonesia starts with an amicable phase handled locally by Hendarman Law Firm: reminders and a formal payment demand, aimed at full payment or a written instalment agreement. Most straightforward claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic - your partner assesses the legal route and you approve a quote before any court step.
The four steps from unpaid invoice to recovered cash
- Step 1 - Amicable collection: reminders, a formal payment demand and negotiation, handled locally by Hendarman Law Firm. Most undisputed claims are resolved in this phase, without going to court.
- Step 2 - Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title and you approve a fixed-price quote before anything proceeds.
- Step 3 - Enforcement: with a legal title, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Step 4 - Insolvency: if the debtor turns out to be insolvent, your proof of claim is filed and any distributions are monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Indonesia - timelines, costs, courts and enforcement - follows in the guide below.

Debt collection in Indonesia - the complete 2026 guide
Written for creditors, in-house counsel and finance teams recovering money from a debtor in Indonesia, this guide sets out how debt collection in Indonesia works end to end: the governing statutes and courts, who does what, the limitation and interest rules, the Gugatan Sederhana small-claims route and ordinary litigation, enforcement by the juru sita, and insolvency before the Pengadilan Niaga.
On this page:
Why you can trust this guide
At Debitura, we uphold the highest standards of impartiality and precision to bring you comprehensive guides on international debt collection. Every guide is written from primary legal sources and reviewed by licensed local experts in the jurisdiction it covers.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 767 licensed partners - collection agencies and law firms in our network
- 180 countries covered - with cases handled in 174 of them
- 5,306 businesses registered with Debitura
- 33 days median time to first payment on European cases
Expert-led, locally validated
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery). Every page is reviewed by top local attorneys to ensure legal accuracy and practical steps you can use.
Contributing local experts:
Last updated:

Debt collection in Indonesia - quick answers
Debt collection in Indonesia is shaped by an unusually long limitation period and by a small-claims procedure with a hard time limit. The headline rules are below.
What is the limitation period for a debt in Indonesia, and does it differ for consumers?
The general limitation period is 30 years under article 1967 of the Kitab Undang-Undang Hukum Perdata (KUHPerdata, the Indonesian Civil Code), and it applies to both commercial and consumer claims. All personal and real civil actions are extinguished by lapse of time (daluwarsa) after 30 years, after which the debt survives only as a natural obligation the debtor may still pay voluntarily. Indonesian law draws no general business-versus-consumer distinction for debt-collection limitation. The Consumer Protection Law's only limitation-adjacent provision, article 27(e) of Undang-Undang No. 8 Tahun 1999 (UUPK), is a 4-year product-liability defence running from purchase of the goods, not a general consumer-debt limitation period, and it must not be conflated with ordinary debt collection. Shorter periods of 1 to 5 years do exist under KUHPerdata articles 1968 to 1971, but they key off the type of claim (for example 5 years for a shopkeeper's claim for goods delivered), so the same period applies whether the buyer was a company or a private consumer. Limitation is interrupted by a written acknowledgement of the debt or by formal interruption under articles 1979 to 1980.
How much does debt collection cost in Indonesia?
Court fees in Indonesia are not a single national figure: each Pengadilan Negeri (district court) sets its own panjar biaya perkara (advance court-fee deposit) by the chief judge's decree, banded into distance radius zones, because much of the fee funds bailiff travel for summonses. At Pengadilan Negeri Depok, Radius I (0 to 30 km), an ordinary civil lawsuit (gugatan biasa) carries a total advance deposit of Rp 916,000, while the equivalent Gugatan Sederhana deposit at the same radius is Rp 616,000, lower because the small-claims procedure needs fewer court summonses and no separate mediation stage. Under article 181(1) of the HIR (Herzien Inlandsch Reglement, the civil procedure code for Java and Madura), the losing party is ordered to pay the costs of the case, though this covers administrative items such as court fees, witness costs and stamp duty, not automatically the winning party's own lawyer's fees.
How long does debt collection take in Indonesia?
Gugatan Sederhana must be resolved within a maximum of 25 days from the first hearing day, under Peraturan Mahkamah Agung (Perma, Supreme Court Regulation) No. 2 of 2015 as amended by Perma No. 4 of 2019. A party dissatisfied with the small-claims judgment has 7 days from pronouncement or notification to file a keberatan (objection) to a panel of judges at the same court, and that ruling is final: no appeal, cassation or judicial review follows. For ordinary district-court litigation (gugatan biasa), Surat Edaran Mahkamah Agung No. 2 of 2014 sets a court-administration target of a maximum of 5 months at first instance.
| Topic | Rule |
|---|---|
| Limitation (commercial and consumer) | 30 years (KUHPerdata art. 1967). No consumer-specific period. |
| Claim-type exceptions | 1 to 5 years for specific claim types (arts. 1968 to 1971), by claim type not debtor type. |
| Gugatan Sederhana (small claims) | Up to Rp 500,000,000; 25 days from first hearing; 7-day keberatan, then final. |
| Gugatan biasa (ordinary litigation) | No ceiling; 5-month first-instance target (SEMA No. 2 of 2014). |
| Statutory interest | 6% per annum where the contract is silent; a contractual rate may be agreed in writing. |
What documents do I need to collect a debt in Indonesia?
Unless the contract fixes an automatic-default deadline, the creditor must first issue a somasi, a written demand notice declaring the debtor in default, before a claim for costs, losses and interest can proceed; the somasi does not need to be a notarised deed. Gugatan Sederhana is limited to claims arising from wanprestasi (breach of contract) or perbuatan melawan hukum (unlawful act), so the file must evidence the underlying contract or transaction and the breach, under simplified evidentiary rules relative to ordinary litigation.
Which legal route should I use to collect a debt in Indonesia?
Gugatan Sederhana is available for a civil claim for wanprestasi or perbuatan melawan hukum with a material value of at most Rp 500,000,000, raised from an original Rp 200,000,000 ceiling by the 2019 amendment. It is limited to one plaintiff against one defendant, subject to a shared-interest exception, and its judgment is subject only to the 7-day keberatan described above. Gugatan biasa (ordinary district-court litigation) applies where the claim exceeds that ceiling, the dispute does not fit the small-claims categories, or the creditor otherwise chooses full civil procedure, with the ordinary rights of appeal, cassation and judicial review available.
Who does what in Indonesia debt collection?
Recovery in Indonesia involves a collection firm or law firm for the amicable phase, advocates for court proceedings, and the court's own juru sita for enforcement. Debitura is the platform that routes and tracks your claim; the regulated work in Indonesia is performed by our licensed local partner, Hendarman Law Firm.
Collection agencies in Indonesia
A collection agency (agen penagihan utang) manages the amicable phase: contacting the debtor, negotiating a payment plan, and preparing the file for escalation. There is no general debt-collector licensing statute, but where the creditor is a licensed financial-services provider (PUJK), the Otoritas Jasa Keuangan's conduct rules bind the collection activity and the PUJK stays liable for its third-party collectors, who must themselves be a licensed legal entity with certified staff.
Advocates in Indonesia
An advocate is needed for ordinary litigation, for insolvency petitions before the Pengadilan Niaga, and in practice for any contested claim, since Indonesian civil procedure runs on documentary evidence and formal pleadings. Gugatan Sederhana is designed to be usable without counsel, but a foreign creditor will still need local representation to file and to hold a valid power of attorney.
The juru sita and the courts in Indonesia
Enforcement is carried out by the juru sita (court bailiff) under the supervision of the chairperson of the Pengadilan Negeri, not by private enforcement agents. The juru sita serves the aanmaning (execution warning), carries out sita eksekusi (execution seizure), and organises the sale of seized assets. Insolvency sits with a separate court, the Pengadilan Niaga (Commercial Court), which has exclusive jurisdiction over bankruptcy and PKPU.
Which laws and courts apply to debt collection in Indonesia?
Indonesian debt recovery runs on a Dutch-derived civil-law system: a codified Civil Code for the substance, colonial-era procedural regulations still in force for procedure, and modern Supreme Court regulations layered on top.
The civil court system in Indonesia
Civil claims start at the Pengadilan Negeri (District Court), with the Pengadilan Tinggi (High Court) hearing appeals and the Mahkamah Agung (Supreme Court) hearing cassation. Two specialised tracks matter for debt: Gugatan Sederhana, the small-claims procedure run inside the Pengadilan Negeri by a single judge for claims up to Rp 500,000,000, which is final after the 7-day keberatan and has no route to appeal or cassation; and the Pengadilan Niaga (Commercial Court), which has exclusive jurisdiction over bankruptcy (kepailitan) and PKPU.
Key legislation in Indonesia
- Kitab Undang-Undang Hukum Perdata (KUHPerdata), the Indonesian Civil Code: contract, default, limitation (article 1967) and statutory interest.
- HIR (Herzien Inlandsch Reglement) and RBg: civil procedure, including costs (HIR article 181(1)) and execution.
- Perma No. 2 of 2015 as amended by Perma No. 4 of 2019: the Gugatan Sederhana small-claims procedure.
- Undang-Undang No. 8 Tahun 1999 (UUPK), the Consumer Protection Law.
- Undang-Undang No. 37 Tahun 2004: bankruptcy (kepailitan) and PKPU.
- Peraturan OJK No. 22 Tahun 2023: financial-sector consumer protection, including collection conduct.
Debt-collection conduct rules in Indonesia
Where the creditor is a licensed financial-services provider (PUJK), article 62 of Peraturan Otoritas Jasa Keuangan (POJK) No. 22 of 2023 sets binding limits on how a debt may be collected. Collection must not involve threats, violence or humiliation, or physical or verbal pressure; it must be directed at the consumer and not at third parties; it must not be continuous or harassing; and it may take place only at the agreed address or the consumer's domicile. Contact is permitted only Monday to Saturday, excluding national holidays, between 08:00 and 20:00 local time, and outside those hours only with the consumer's prior consent. A third-party collector must be a licensed legal entity with certified staff, and the PUJK remains liable for its conduct. Outside the OJK-regulated sector there is no equivalent statutory code, but these rules are the practical benchmark for what an Indonesian court will regard as acceptable collection conduct.
Step 1 - How does amicable (pre-legal) debt collection work in Indonesia?
Pre-legal collection in Indonesia recovers an unpaid invoice without going to court, and it has a formal step that is easy to miss: the somasi. Unless the contract fixes a due date after which default arises automatically, the creditor must issue a somasi, a written demand notice declaring the debtor in default (wanprestasi), before a claim for costs, losses and interest can proceed. The somasi does not need to be a notarised deed, but without it the later court claim is weaker. A written acknowledgement of the debt also interrupts the limitation period.
| Stage | Action |
|---|---|
| Reminder | Invoice, due date and payment details. |
| Somasi | Written demand declaring the debtor in default. Usually issued more than once in practice. |
| Negotiation | Settlement or instalment plan, ideally acknowledged in writing. |
| Escalation | Gugatan Sederhana where the claim is at most Rp 500,000,000, otherwise gugatan biasa. |
Conduct rules in the amicable phase in Indonesia
Where the creditor is a licensed financial-services provider (PUJK), article 62 of POJK No. 22 of 2023 governs how the debt may be collected: no threats, violence or humiliation, no physical or verbal pressure, contact with the consumer only and not with third parties, nothing continuous or harassing, and contact only at the agreed address or the consumer's domicile. Contact is confined to Monday to Saturday, excluding national holidays, 08:00 to 20:00 local time unless the consumer has consented otherwise, and a third-party collector must be a licensed legal entity with certified staff while the PUJK stays liable for its conduct. Outside the OJK-regulated sector there is no equivalent statutory code, but these are the standards Indonesian courts and counterparties measure conduct against.
When to escalate to court in Indonesia
Escalate when the somasi lapses or the debtor disputes without substance. The 30-year limitation period means time pressure is rarely the trigger in Indonesia, unlike most jurisdictions; the real trigger is asset risk, since a debtor who is dissipating assets or heading for insolvency is far harder to recover from once the Pengadilan Niaga is involved.
Step 2 - How do you obtain an enforceable title in Indonesia?
Indonesia offers a genuinely fast small-claims route with a hard statutory deadline, and ordinary district-court litigation for everything above it. Which one applies is decided by the claim's value and its legal basis.
Gugatan Sederhana (the small-claims procedure)
Gugatan Sederhana is available for a civil claim founded on wanprestasi (breach of contract) or perbuatan melawan hukum (unlawful act) with a material value of at most Rp 500,000,000, raised from an original Rp 200,000,000 ceiling by the 2019 amendment. It is governed by Peraturan Mahkamah Agung (Perma) No. 2 of 2015 as amended by Perma No. 4 of 2019, heard by a single judge, and limited to one plaintiff against one defendant, subject to a shared-interest exception. It must be resolved within 25 days of the first hearing day. If the defendant does not appear after a second proper summons the court may give a default judgment (verstek), against which the defendant can file verzet within 7 days of notice. The losing party has 7 days from pronouncement or notification to file a keberatan (objection) to a panel of judges at the same court, and that ruling is final: no appeal, cassation or judicial review follows.
Gugatan biasa (ordinary litigation)
Ordinary district-court litigation applies where the claim exceeds the small-claims ceiling, does not fit the wanprestasi or perbuatan-melawan-hukum categories, or where the creditor prefers full civil procedure. Surat Edaran Mahkamah Agung No. 2 of 2014 sets a court-administration target of a maximum of 5 months at first instance, and the ordinary rights of appeal to the Pengadilan Tinggi, cassation to the Mahkamah Agung and judicial review all apply. Indonesia has no common-law style summary judgment, so a genuinely disputed claim goes to a full hearing on the documents.
Determining the appropriate court in Indonesia
Ordinary money claims are filed at the Pengadilan Negeri (District Court), including Gugatan Sederhana, which runs inside it as a simplified track. Bankruptcy and PKPU are different: they belong exclusively to the Pengadilan Niaga (Commercial Court). During a small-claims case the judge may also order sita jaminan (conservatory attachment), which is worth asking for where there is any risk that assets will move before judgment.
Step 3 - How does debt enforcement work in Indonesia?
Enforcement (eksekusi) in Indonesia is carried out by the court's own juru sita (bailiff) under the supervision of the chairperson of the Pengadilan Negeri. There is no private bailiff profession, so the pace of enforcement is the pace of the court, and everything runs on the creditor's application.
The enforcement sequence in Indonesia
Once the judgment is final, the creditor applies to the court for execution. The chairperson of the court issues an aanmaning, an execution warning giving the debtor a short window to comply voluntarily; in the Gugatan Sederhana route the warning is issued within 7 days of the execution request. If the debtor still does not pay, the court proceeds to sita eksekusi (execution seizure) of the debtor's assets, followed by sale, with the proceeds applied to the judgment sum and costs.
Ways to secure and enforce a claim in Indonesia
- Sita jaminan (conservatory attachment): available on the judge's order during proceedings, including in Gugatan Sederhana. It freezes assets before judgment and is the single most useful protective step where the debtor may dissipate assets.
- Sita eksekusi (execution seizure): post-judgment seizure of movable and immovable property under the HIR and RBg framework, executed by the juru sita.
- Public auction: seized assets are sold and the proceeds applied to the claim.
- Secured assets: where you hold fiducia security, a mortgage or a hipotek, you are a kreditor separatis and can generally realise the security largely as if bankruptcy had not occurred, which is a far stronger position than an unsecured judgment.
The practical lesson is that enforcement effort in Indonesia is front-loaded: identifying and freezing assets during the case, through sita jaminan, does more for recovery than any step taken after judgment.
Step 4 - How do insolvency procedures affect debt recovery in Indonesia?
Where a debtor cannot pay, individual enforcement gives way to a collective procedure before the Pengadilan Niaga (Commercial Court), which has exclusive jurisdiction. Undang-Undang No. 37 Tahun 2004 governs both routes: kepailitan (bankruptcy), which liquidates, and PKPU (Penundaan Kewajiban Pembayaran Utang, suspension of debt payment obligations), which restructures.
The threshold for bankruptcy in Indonesia
Indonesia's bankruptcy threshold is unusually low and this matters to creditors. Under article 2(1) of Undang-Undang No. 37 Tahun 2004, a debtor can be declared bankrupt where there are two or more creditors and at least one debt that is due and collectible. There is no minimum debt size and no balance-sheet insolvency test, so a bankruptcy petition is a real lever against a solvent but unwilling corporate debtor, and equally a real risk if your debtor's other creditors move first. The petition may be filed by the debtor or by a creditor.
Priority and what a trade creditor can expect
Creditors fall into three classes. Kreditor separatis (secured creditors holding fiducia security, a mortgage or a hipotek) rank first and may generally realise their security largely as if the bankruptcy had not occurred, under article 55(1). Kreditor preferen (preferential or privileged creditors, per KUHPerdata article 1134) rank next. Kreditor konkuren (ordinary unsecured creditors) rank last and are paid pro rata from whatever remains of the estate. An ordinary trade creditor is a kreditor konkuren, which is the practical argument for taking security where the relationship allows it, and for acting while sita jaminan and execution are still available.
The creditor process in Indonesia
A court-appointed curator administers the estate in a bankruptcy, and creditors register their claims with the curator for verification. In a PKPU, creditors vote on the debtor's composition plan, so an unsecured creditor's leverage is procedural rather than proprietary: turning up, verifying the claim and voting is what determines the outcome.
Fees, interest and who pays what in Indonesia
- Our fee: success-based, No Cure, No Pay (see pricing).
- Court fees: a panjar biaya perkara (advance court-fee deposit) applies only if the case escalates. Each Pengadilan Negeri sets its own, banded by distance radius, so the figure depends on the court and the route: at Pengadilan Negeri Depok, Radius I, an ordinary suit carries a Rp 916,000 deposit against Rp 616,000 for Gugatan Sederhana.
- Statutory debtor items: where the contract is silent, moratory interest runs at 6% per annum; costs, losses and interest (biaya, rugi dan bunga) become claimable once the debtor is in default.
- Who keeps what: recovered principal is yours; interest and costs follow the contract, the Civil Code and the court's order.
Interest and costs on an Indonesian debt
Where a contract fixes no interest rate, the statutory (moratory) rate is 6% per annum, a figure that traces to Staatsblad 1848 No. 22 and is still applied. The parties may agree a different rate in writing under KUHPerdata article 1767, and a contractual rate is the practical way to make late payment expensive in a jurisdiction whose statutory rate is low. On costs, article 181(1) of the HIR orders the losing party to pay the costs of the case, but that covers administrative items such as court fees, witness costs and stamp duty, not automatically the winner's own lawyer's fees, so each side commonly carries its own legal spend. Interest and damages are claimable only once the debtor has been put in default, which is what the somasi is for.
Cross-border debt collection in Indonesia
A foreign court judgment is not directly enforceable in Indonesia. Indonesia has not ratified the Hague convention on foreign judgments and has no general reciprocal-enforcement treaty regime, and article 436 of the Reglement op de Rechtsvordering (Rv), a colonial-era procedural instrument still cited in current Indonesian practice, is the source of that position. A creditor holding a foreign judgment must therefore bring a fresh domestic lawsuit in Indonesia (re-litigasi) on the underlying debt; the foreign judgment can carry persuasive evidential weight in that action but does not decide it. Foreign arbitral awards are treated differently and are the reason many cross-border supply contracts with Indonesian counterparties choose arbitration. The practical consequence for a creditor is straightforward: if your debtor's assets are in Indonesia, litigating at home first usually buys you nothing, and the claim is better brought in Indonesia from the start, through Gugatan Sederhana where it fits the ceiling.
Find a Local Debt Collection Lawyer
Need court-ready representation? Share your case once and receive up to three proposals from vetted litigation attorneys. Free, fast, and with no commitment.
- Verified specialists
- Quotes in 24 h, no hidden fees
- Fair, pre-negotiated rates
Debt Recovery Indonesia is a premier law firm in Jakarta Selatan offering effective Debt Collection services in Indonesia, established in 2005, renowned for its flexible fee arrangements and accolades such as The Best Litigation Law Firm 2025, serving over 450 clients nationwide.
Sarvasuksma Attorneys at Law is a premier law firm in Jakarta Selatan offering effective Debt Collection services in Indonesia, recognized as an ALB Indonesia Firm to Watch 2023 and finalist for Dispute Resolution Boutique Law Firm of the Year 2022, founded in 2021.
Prayogo Advocaten Law Firm is a premier law firm in Jakarta Timur offering effective Debt Collection services in Indonesia, established in 2014, with accolades in maritime law and memberships in PERADI and HKHPM, serving clients in ten countries.
Law Office of Amir Hamzah & Rekan is a premier law firm in Bekasi offering effective Debt Collection services in Indonesia, established in 2017 and recognized for its membership in the Worldwide Independent Lawyers League and Perhimpunan Advokat Indonesia (PERADI).
Lawyerindo Legal and Business Support Center is a premier debt recovery agency in Jakarta Pusat offering effective Debt Collection services in Indonesia, established in 2014 with a transparent operational fee/success fee model, enhancing trust and maximizing recovery outcomes.


Makarim & Taira S. is a premier law firm in Jakarta offering effective Debt Collection services in Indonesia, established in 1980 and recognized with accolades such as the Asialaw Awards 2024, positioning the firm as a trusted partner in debt recovery.
DHP Law Firm is a premier law firm in Jakarta Pusat offering effective Debt Collection services in Indonesia, established in 1995 and recognized among the Top 100 Indonesian Law Firms 2023, with memberships in PERADI and Mitra Hukumonline.
Soengkar & Partners is a premier law firm in Jakarta Selatan offering effective Debt Collection services in Indonesia, positioning the firm as the go-to partner for debt recovery since 1995, with memberships in PERADI, LowPartners, and the Debitura Partner Network.
RSBP & Co. Law Firm is a premier law firm in Jakarta Selatan offering effective Debt Collection services in Indonesia, positioning itself as the go-to partner for debt recovery with a foundation in 2022, award-winning recognition, and esteemed memberships in Peradi, HKHPM, and AKPI.
Rajamada & Partners is a premier law firm in Jakarta offering effective Debt Collection services in Indonesia, recognized by The Legal 500 and Asia Law since 2016, serving Southeast Asian markets and the Americas with tailored, transparent solutions.
Yunaelish & Associates Law Firm is a premier law firm in Denpasar offering effective Debt Collection services in Indonesia, positioning itself as the go-to partner for debt recovery with a foundation in 2017, accolades, and memberships in PERADI and ASAHI.

Hendarman Law Firm is a premier law firm in Indonesia offering effective risk-free Debt Collection services. Established in 2011, the firm is the go-to partner for debt recovery, recognized for its accolades and memberships, and serves as an exclusive Debitura partner in Indonesia, providing No Cure No Pay debt collection based on Debitura's risk-free standard terms and pricing.
Legalinfo Lawyers is a premier law firm in Jakarta Selatan offering effective Debt Collection services in Indonesia, positioning itself as the go-to partner for debt recovery since 2025 with a team of experienced attorneys and multiple industry accolades.

MSD Law Firm is a premier law firm in Badung offering effective Debt Collection services in Indonesia, positioning itself as the go-to partner for debt recovery since 2019, with memberships in PERADI SAI, HKPI, and ASAHI.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.