
Debt Collection Agency in Mexico: No Win, No Fee
Stop chasing overdue invoices in Mexico. Your claims are handled by ATIVO, our local debt collection agency (agencia de cobranza), working under the Código de Comercio, with zero upfront costs. Submit claims in minutes, track real-time updates, and only pay if your money is recovered.


Questions about your case?
Write to us, we reply by email.

Why choose Debitura for debt collection in Mexico
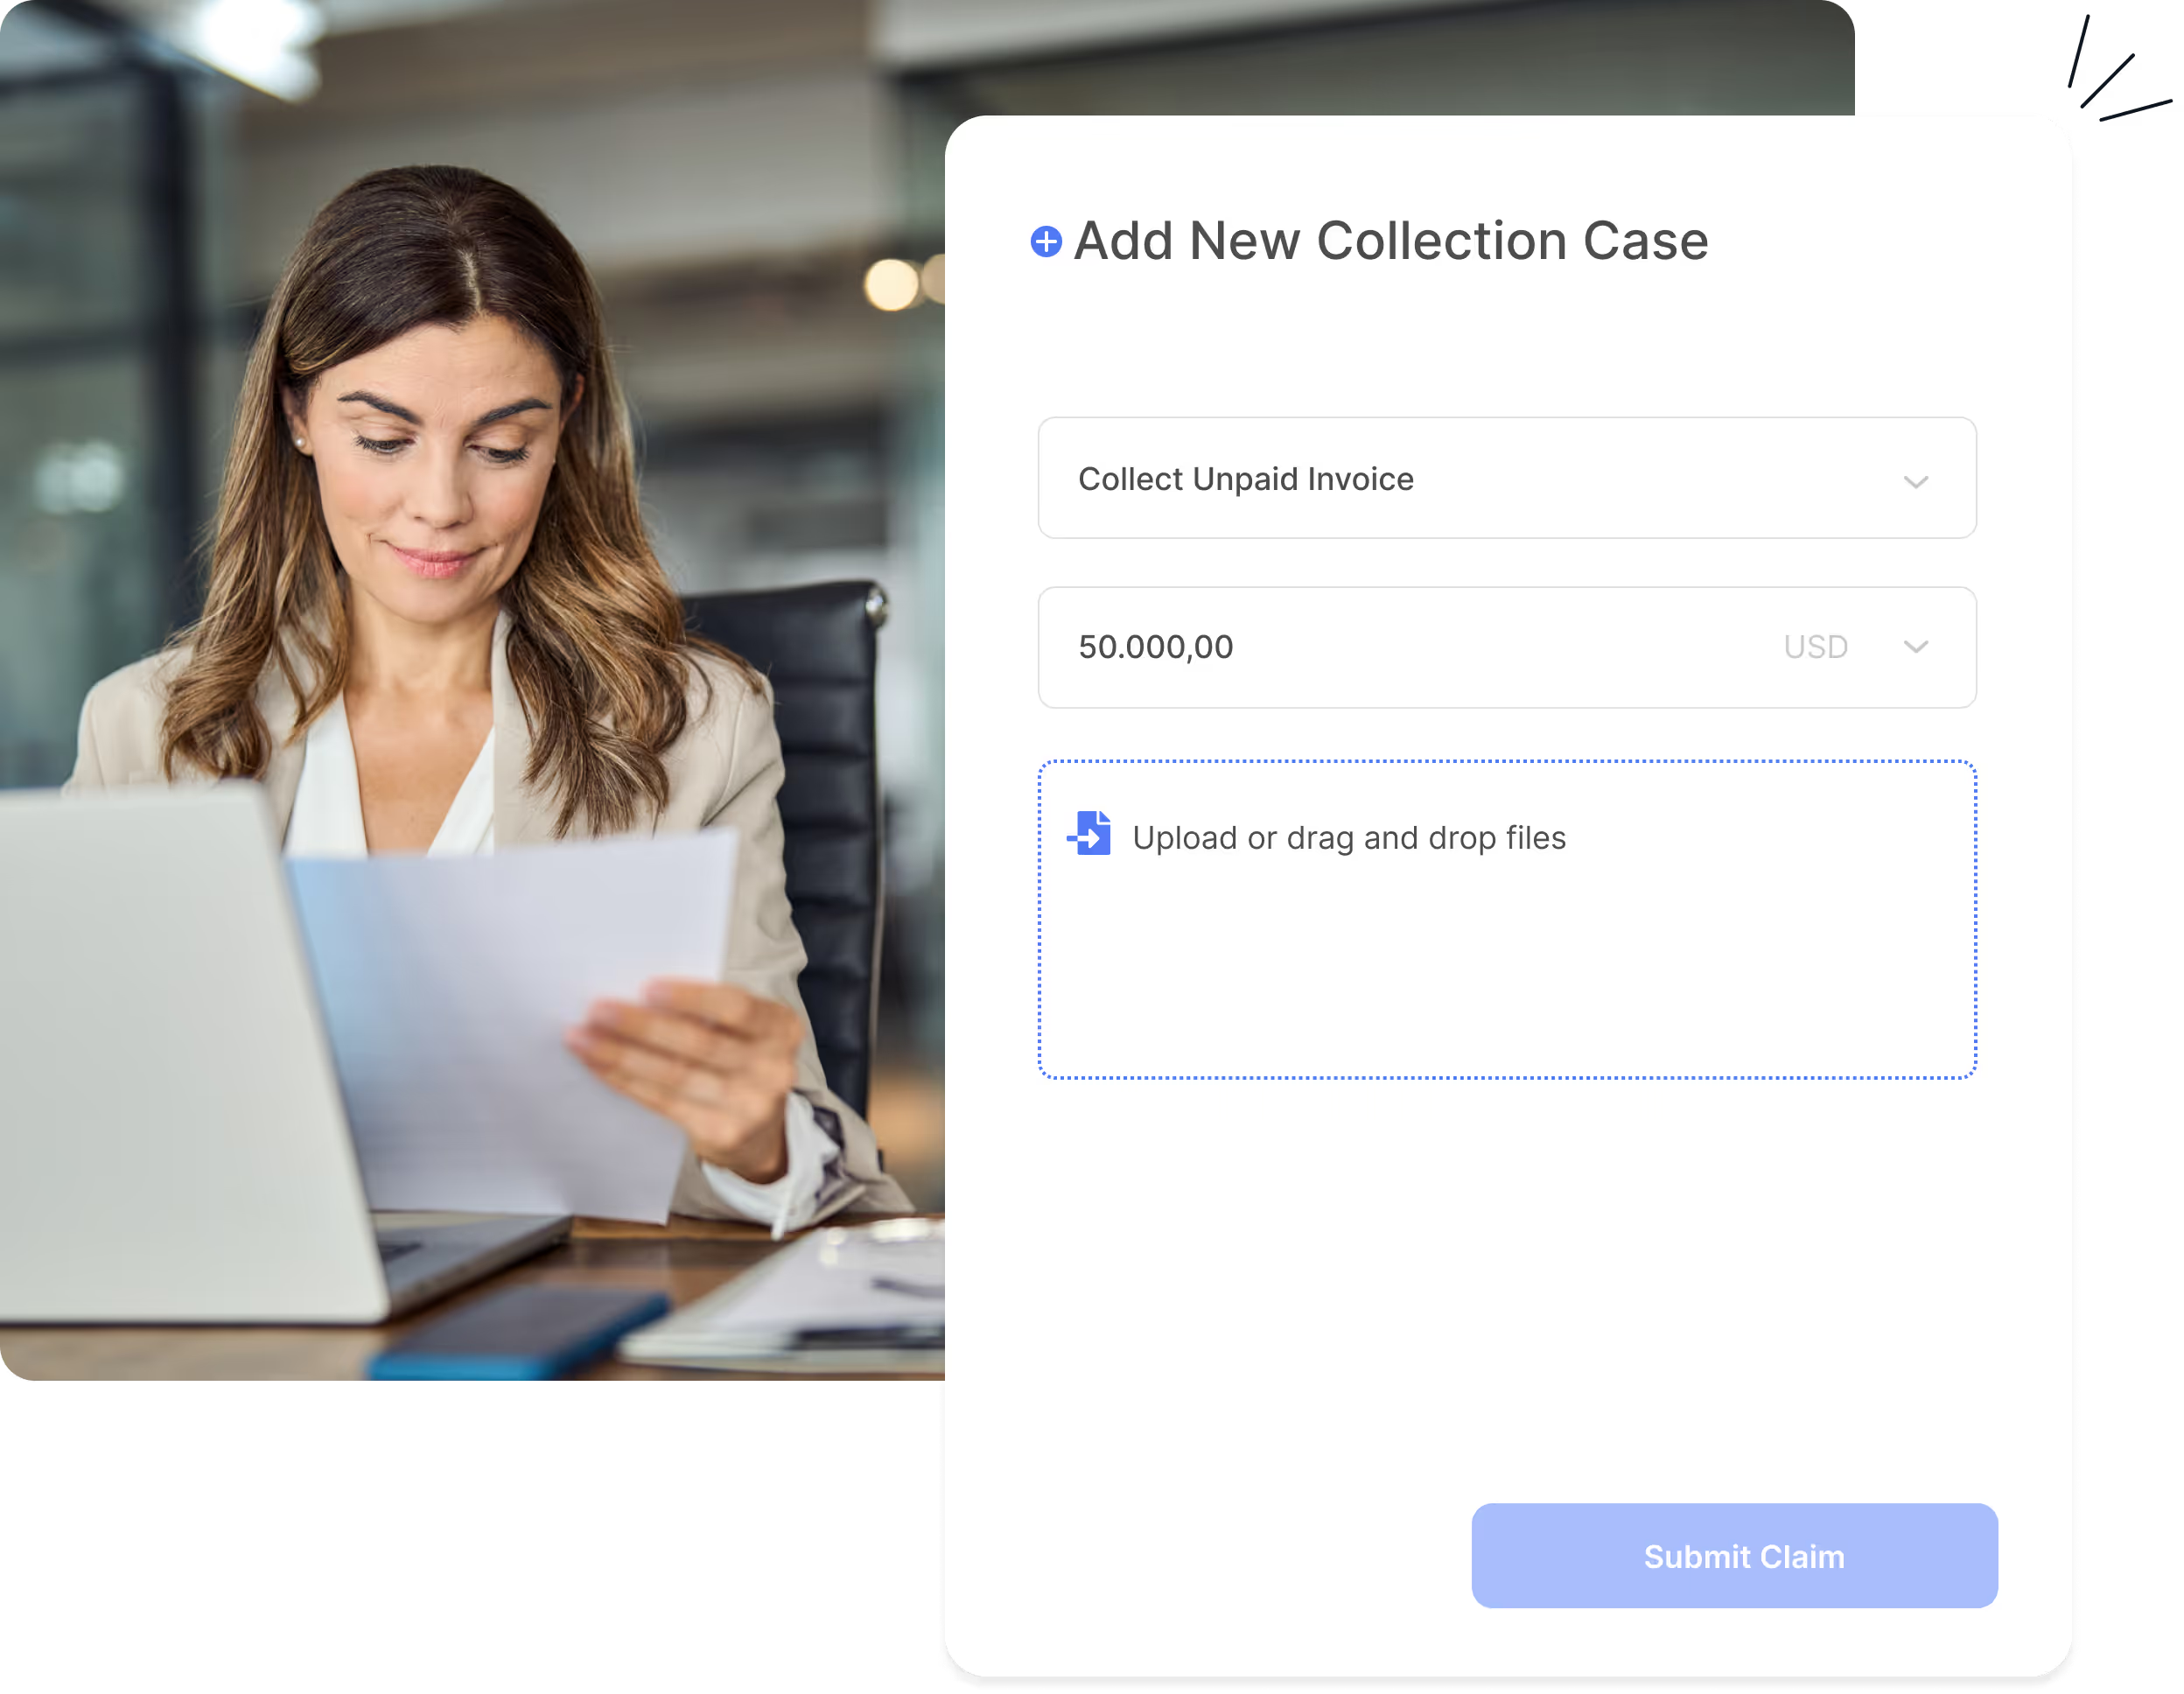
Start recovering your claims in Mexico in minutes
- Submit your claim: Upload your unpaid invoice in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server. Add supporting documents in a few clicks, with no paperwork and no setup fees.
- Local collection begins: Your case is assigned to ATIVO, who starts amicable contact with the debtor on your behalf. If court action is ever needed later, you approve a legal quote before anything proceeds, so nothing is spent without your consent.
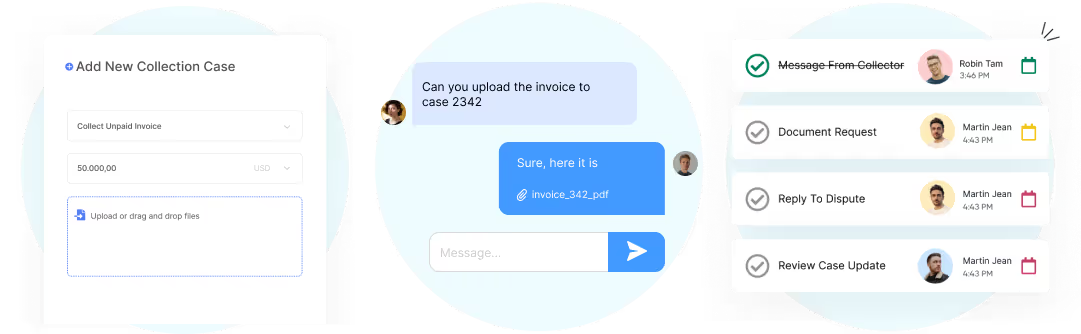
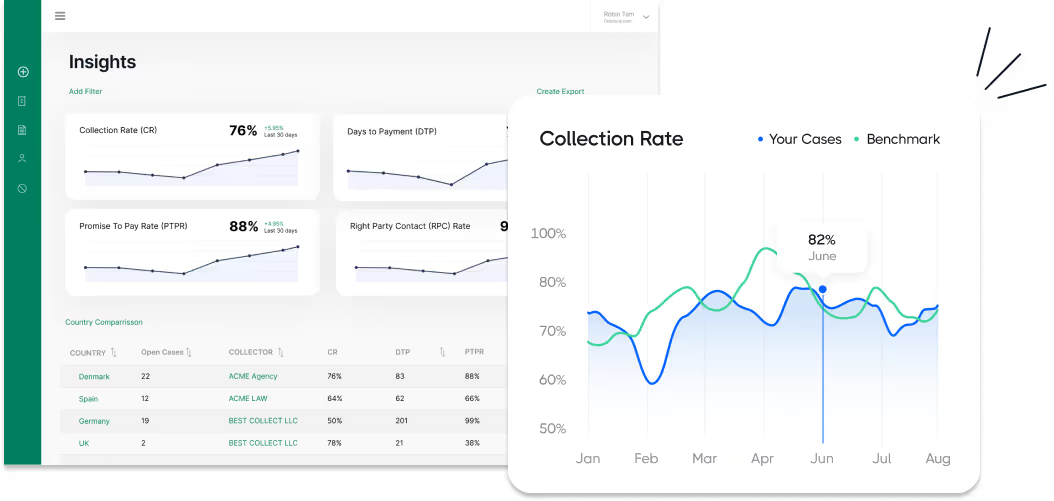
- Track and get paid: Follow every update in real time on your dashboard, from the first reminder to the final payment, with a notification at each milestone. Your partner pays out your share within 30 business days, with a statement, and you only pay on success.
Transparent, success-based pricing
With Debitura you pay a success fee only when money is recovered. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Mexico?
In the video below, Eduardo Valero, COO of ATIVO in Mexico City, our partner in Mexico, explains how debt collection works in Mexico, from the first contact with your debtor to court, enforcement and interest.
The four steps from unpaid invoice to recovered cash
- Amicable collection: reminders, a formal payment demand and negotiation, handled locally by ATIVO. Most undisputed claims are resolved in this phase, without going to court.
- Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a legal title, the competent enforcement authority can attach wages, bank funds and other assets until the claim is recovered.
- Insolvency: if the debtor turns out to be insolvent, recovery depends on the local insolvency proceedings and is often uncertain. Any step in those proceedings is quoted separately and only starts if you accept.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Mexico - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in Mexico - the complete 2026 guide
Learn how debt collection works in Mexico - procedures, timelines, creditor rights, and enforcement - and how Debitura helps global creditors recover overdue payments efficiently, with no upfront cost.
On this page:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).

Contributing local experts:
Last updated:

Debt collection in Mexico - quick answers
How much does debt collection cost in Mexico?
Debitura's fee is success-based (No Cure, No Pay, see pricing). Collection-agency fees during the amicable phase are typically contingency-based, so you pay from what is recovered, not upfront. If a case escalates to court, lawyer fees are agreed with the lawyer and quoted to you first, and a Mexican court can order the losing party to pay costas (partial cost reimbursement) under the Código de Comercio, assessed case by case under local tariffs and not guaranteed; Mexican civil/commercial filings carry no state filing fee (Código de Comercio art. 1081).
How long does debt collection take in Mexico?
According to our partner ATIVO, the amicable phase runs for up to about 90 days: first contact within 24 hours, two to three weeks of intensive contact attempts, a recommendation by week five if the debtor has not engaged, and at least 60 more days of collection before you are asked how to proceed. In our partner's experience, an executive trial (juicio ejecutivo mercantil) takes six months to two years and an oral or ordinary commercial trial one to two and a half years, before enforcement, where bank-account garnishments move fastest. Appeals and amparo proceedings can extend either route.
What documents do I need to start a claim in Mexico?
An executable instrument, such as a signed pagaré (promissory note), a letra de cambio (bill of exchange), or a reconocimiento notarial (notarized acknowledgment of debt), qualifies a claim for the fast-track juicio ejecutivo mercantil. Without one of these instruments, a claim for a set amount, such as an unpaid invoice, proceeds as juicio oral mercantil, which requires fuller evidentiary documentation of the underlying debt: the contract or purchase orders, invoices, proof of delivery and correspondence.
What are the limitation period and interest rules in Mexico?
Contract and commercial debts generally prescribe after 10 years in Mexico: the Código Civil Federal (the Federal Civil Code, art. 1159) sets a 10-year period for civil obligations absent a shorter special rule, and the Código de Comercio (the Commercial Code, arts. 1040 and 1047) applies the same 10-year default to commercial claims, counted from the day the claim could first be brought in court. Shorter periods apply to specific claims, such as one year for credit sales by retail sellers (art. 1043). A pagaré (promissory note) must be enforced within 3 years of its maturity, and a pagaré with no due date is payable on sight and must be presented for payment within 6 months of its date (Ley General de Títulos y Operaciones de Crédito, arts. 128, 165 and 171). Filing a court claim served on the debtor, or the debtor's own acknowledgment of the debt, interrupts the period and restarts the clock (CCF arts. 1168-1169, 1175; CCom arts. 1041-1042). Statutory interest runs at 9% per year on civil debts (CCF art. 2395) and 6% per year on commercial debts where no rate was agreed (CCom art. 362).
| Item | Rate/period | Basis |
|---|---|---|
| Civil limitation | 10 years | Código Civil Federal art. 1159 |
| Commercial limitation | 10 years (shorter for some claims, e.g. 1 year for retail credit sales) | Código de Comercio arts. 1043, 1047 |
| Pagaré (promissory note) | 3 years from maturity | LGTOC art. 165 |
| Civil statutory interest | 9% per year | CCF art. 2395 |
| Commercial statutory interest | 6% per year | CCom art. 362 |
When do I need a lawyer for debt collection in Mexico?
The Código de Comercio does not strictly require a lawyer in commercial trials (art. 1083), but anyone who represents a party with broad powers must be a licensed lawyer (art. 1069), so in practice a foreign creditor acts through a Mexican lawyer holding a power of attorney. A claim without an executable instrument goes to the juicio oral mercantil (oral commercial trial) whatever its amount (Código de Comercio art. 1390 Bis), and an appeal is barred below a periodically indexed threshold, currently MXN $924,300.58 (art. 1340, 2026 figure).
Which route recovers a Mexican debt fastest?
Amicable collection through an agencia de cobranza such as ATIVO comes first and is the fastest way to get paid where the debtor engages. Where the debtor does not respond, the fast-track juicio ejecutivo mercantil is next if you hold an executable instrument; otherwise the claim goes to the juicio oral mercantil, and the written juicio ordinario mercantil is left for claims of undetermined amount.
| Route | When it applies |
|---|---|
| Amicable (agencia de cobranza) | Always the first step; our partner contacts the debtor within 24 hours. |
| Juicio ejecutivo mercantil | You hold an executable instrument (pagaré, letra, or reconocimiento notarial); oral for principal between MXN $924,300.58 and MXN $4,000,000, written otherwise. |
| Juicio oral mercantil | No executable instrument and a set amount, such as an unpaid invoice; no value ceiling. |
| Juicio ordinario mercantil | Claims of undetermined amount and matters without their own procedure. |
| Enforcement (ejecución) | After judgment, via embargo, bank-account seizure, or judicial auction; bank accounts move fastest. |
Who does what in Mexico debt collection?
Mexico's process involves three core players - collection agencies (agencias de cobranza) for amicable recovery, lawyers (abogados mercantiles) for executive and oral-trial litigation, and court officials (actuarios/jueces ejecutores) who execute seizures, garnishments, and auctions.
Collection agencies in Mexico
- Role: Manage pre-legal recovery (gestión amistosa), contacting debtors to negotiate voluntary payment or an instalment plan.
- Scope: Issue formal notices, demand letters (cartas de cobranza), and arrange settlements before court escalation.
- Licensing: No specific licence or registration is required to collect business-to-business debts in Mexico. Agencies that collect for banks and other financial entities are registered by those entities in CONDUSEF's register of collection agencies (REDECO) and follow its conduct rules (LTOSF arts. 17 Bis 1-4).
- Fees: Contingency-based arrangements are standard practice for the amicable phase.
- Debitura's partner: ATIVO is a B2B collection agency in Mexico City whose collectors are attorneys; it makes first contact within 24 hours and aims to protect the commercial relationship where it can.
Lawyers in Mexico
- Role: Represent creditors in the juicio ejecutivo mercantil (the fast-track executive trial), the juicio oral mercantil (the oral commercial trial for claims of a set amount without an executable instrument, with no value ceiling) and the written juicio ordinario mercantil (claims of undetermined amount).
- Scope: Draft legal claims, obtain embargo (asset-seizure) orders, represent clients in hearings, appeals, and amparo proceedings.
- Court access: The Código de Comercio does not strictly require a lawyer (art. 1083), but a representative with broad powers must be a licensed lawyer (art. 1069), so a foreign creditor in practice acts through a Mexican lawyer; an appeal is barred below MXN $924,300.58 (Código de Comercio art. 1340, 2026 figure).
- Fees: Agreed with the lawyer; courts may order the losing party to pay costas, assessed under local tariffs.
- Debitura's partner: ATIVO does not litigate itself. Its legal project manager coordinates partner lawyers in the debtor's state, because court practice differs between states, and you approve a quote before anything starts.
Court officials and bailiffs in Mexico
- Role: Enforce judgments and executive-trial orders through official seizure, garnishment, and auction procedures.
- Scope: Execute embargo (asset seizure), bank garnishments, and judicial auctions; ensure due process and documentation.
- Supervision: Operate under court authority; cannot act independently or outside judicial orders.
- In practice: according to our partner, for a foreign creditor a bank-account garnishment usually turns into money far more easily than seized property, machinery or vehicles.
Which laws and courts apply to debt collection in Mexico?
Mexico is a federal republic: commercial law is federal, but civil procedure has historically been state-by-state, and a new national procedure code is now rolling out. Clear but multi-layered rules blend federal codes with this state-by-state practice, from the fast-track juicio ejecutivo mercantil to strict consumer-protection conduct.
The civil court system in Mexico
- Juicio ejecutivo mercantil: fast-track route if you hold an executable instrument (pagaré, letra, reconocimiento notarial); the court orders payment and, on default, an immediate embargo (Código de Comercio arts. 1391-1392). It runs as an oral trial for principal between MXN $924,300.58 and MXN $4,000,000 (art. 1390 Ter), and in writing otherwise.
- Juicio oral mercantil: the commercial trial for claims of a set amount without an executable instrument; since the 2017 reform took full effect in 2020 it has no monetary ceiling (art. 1390 Bis).
- Juicio ordinario mercantil: the written trial that remains for claims of undetermined amount and matters without their own procedure.
- Concurrent jurisdiction: commercial matters can fall to state or federal courts (Constitución art. 104 fr. I-A, Código de Comercio art. 1100).
- Enforcement (ejecución): via embargo, bank/account seizures, and judicial auctions.
Key legislation in Mexico
- Código Civil Federal (the Federal Civil Code) and Código de Comercio (the Commercial Code): govern civil/commercial obligations, evidence, and limitation (prescripción).
- Ley General de Títulos y Operaciones de Crédito (LGTOC): governs pagarés and other negotiable instruments, including their 3-year limitation period.
- Código Nacional de Procedimientos Civiles y Familiares (CNPCF), Mexico's new national civil/family procedure code: published 7 June 2023, rolling out toward full nationwide effect by 1 April 2027, replacing the old state-by-state civil procedure codes.
- Ley de Concursos Mercantiles (the Business Insolvency Law): governs conciliación and quiebra/liquidation for merchant debtors.
- Ley para la Transparencia y Ordenamiento de los Servicios Financieros (LTOSF) and the Ley Federal de Protección al Consumidor (LFPC): give CONDUSEF and PROFECO conduct-oversight and sanctioning power over collection practices, particularly for financial-sector debts.
Consumer protection in Mexico
- PROFECO rules: no harassment, clear identification, accurate debt details, respectful contact hours; PROFECO holds sanctioning power under LFPC arts. 62 fr. VI and 128.
- CONDUSEF oversight for financial-services collections.
- Mandatory disclosures: amount, origin, legal basis, rights to dispute/rectify.
- Data handling aligned with privacy law; documented, traceable communications required.
- Breaches risk fines and can jeopardize enforcement.
Step 1 - How does amicable (pre-legal) debt collection work in Mexico?
Amicable collection in Mexico is handled by an agencia de cobranza such as ATIVO, our partner: the agency verifies the debt and the debtor, contacts the debtor by phone and with a formal payment demand, and negotiates a voluntary payment or a written instalment plan. Every notice should state the amount, origin and basis of the debt, and communications stay documented and traceable throughout.
How our partner runs the amicable phase in Mexico
According to ATIVO, every new case is first checked by one person, who reviews the documents and contact details and fills any gaps from public sources and the internet: in Mexico a company's legal name often differs from its trading name, and the address registered with the tax authority is not always where the business operates. The case then goes to a collector, who is an attorney.
| When | What happens (our partner's practice) |
|---|---|
| Within 24 hours | First contact with the debtor, by phone or as a formal payment demand by email. |
| Weeks 1 to 3 | Intensive contact attempts and further research on the debtor; where the debtor engages, the reasons for non-payment and its capacity to pay are assessed and a payment proposal goes to you. |
| Week 4 | If the debtor still cannot be reached, an optional address verification by site visit or formal letter, quoted first, with a result within a week. |
| Week 5 | A recommendation on whether a legal route is worth assessing. |
| Up to about day 90 | If you take no other step, collection continues for at least 60 more days, after which you are asked how to proceed. |
Address verification is an optional extra outside the No Cure, No Pay scope. A debtor who cannot pay in full is asked for evidence of its payment capacity, and an instalment plan backed by that evidence is often better than a lawsuit, because winning a case and collecting the money are not the same. A debtor who says it does not owe the money has to give a reason backed by documents, such as photos of damaged goods or an expert report; a plain "no" is not treated as a formal dispute.
Escalation to court is never automatic: your partner first checks whether you hold an executable instrument (pagaré, letra, or reconocimiento notarial), and you approve a legal quote before any legal step begins.
Step 2 - How do you obtain an enforceable title in Mexico?
If amicable collection fails, your lawyer determines whether your claim qualifies for juicio ejecutivo mercantil (the fast-track executive trial) or goes to the juicio oral mercantil (the oral commercial trial), based on whether you hold an executable instrument.
Juicio ejecutivo mercantil (fast-track)
Juicio ejecutivo mercantil is available when the creditor holds an executable instrument, such as a signed pagaré (promissory note), a letra de cambio (bill of exchange), a judicial confession, or a reconocimiento notarial (notarized acknowledgment of debt). When the claim is admitted, the court orders the debtor to pay and, if the debtor does not, the seizure (embargo) of assets to secure the claim (Código de Comercio arts. 1391-1392); the debtor then has 8 days to pay or raise defences (art. 1396), which is what makes this route faster than the standard trial. For principal between MXN $924,300.58 and MXN $4,000,000 the executive trial runs orally (art. 1390 Ter); outside that band it is written.
Juicio oral mercantil (the oral commercial trial)
Juicio oral mercantil applies to a claim of a set amount, such as an unpaid invoice, when no executable instrument exists. Since the 2017 reform took full effect in January 2020 it has no monetary ceiling (Código de Comercio art. 1390 Bis), and it follows the full evidentiary process under the Código de Comercio. The written juicio ordinario mercantil remains for claims of undetermined amount and matters without their own procedure. A national procedure code, the Código Nacional de Procedimientos Civiles y Familiares (CNPCF), published 7 June 2023, is rolling out toward full nationwide effect by 1 April 2027. In our partner's experience, an executive trial takes six months to two years and an oral or ordinary trial one to two and a half years; appeals and amparo proceedings can extend the timeline.
Determining the competent court in Mexico
Unless the parties validly agreed on a court, a commercial claim in Mexico is filed, in this order, where the debtor was designated to pay, at the place of performance named in the contract, or at the debtor's domicile (Código de Comercio art. 1104); an agreed court can only be one at either party's domicile, the place of performance or where the property is (art. 1093). Jurisdiction can be concurrente (concurrent) between state and federal courts for certain commercial matters (Constitución art. 104 fr. I-A, Código de Comercio art. 1100). An appeal is barred below a periodically indexed threshold, currently MXN $924,300.58 (art. 1340, 2026 figure).
Legal costs in Mexico
Lawyer fees are agreed with the lawyer, and through Debitura you receive a quote before any legal step. A Mexican court can order the losing party to pay costas (partial cost reimbursement), assessed under local tariffs, though this is case-by-case and not guaranteed; there is no state filing fee for judicial acts (Código de Comercio art. 1081). Once a judgment is secured, enforcement (ejecución) through embargo, bank or account seizure, or a judicial auction is carried out under the supervision of court officials (actuarios/jueces ejecutores), who act only under judicial authority.
Step 3 - How does debt enforcement work in Mexico?
Enforcement in Mexico follows directly from the fast-track juicio ejecutivo mercantil: once the court confirms the creditor holds an executable instrument (a pagaré, a letra de cambio, a judicial confession, or a judicially recognised invoice or contract), it orders payment and, on default, orders an immediate embargo (asset seizure) to secure the claim (Código de Comercio arts. 1391-1392). The debtor then has 8 days to pay or raise defences before the case proceeds (art. 1396). Because this route already includes an early embargo before final judgment, creditors holding a qualifying instrument can secure assets well before the case concludes; in the juicio oral mercantil enforcement usually waits for judgment, although precautionary measures such as the retention of assets can be requested in any commercial case (art. 1168 and following).
Ways to enforce a claim in Mexico
- Embargo (asset seizure): court officials (actuarios) seize identified assets, bank balances or receivables to secure or satisfy the judgment.
- Judicial auction: seized assets are sold at auction and proceeds applied to the debt, interest and costas.
- Account measures: enforcement can reach identified bank accounts within the seizure order's scope.
The enforcement process in Mexico
- Confirm the title: the court verifies the executable instrument or judgment before ordering embargo.
- Locate assets: the creditor's counsel identifies bank accounts, receivables or property to target.
- Embargo and, where needed, auction: actuarios/jueces ejecutores carry out the seizure under court supervision; defences raised in the 8-day window can delay the process.
- Distribution: proceeds are applied to principal, statutory interest and any court-awarded costas; any surplus returns to the debtor.
Practical points for foreign creditors in Mexico
According to our partner, a foreign creditor does best by aiming at the debtor's bank accounts: being first in line to garnish an account that holds enough money is the strongest position, while property, machinery or vehicles are hard to turn into cash from abroad. A seizure noted against real estate in the property register also has to be kept alive: under the Federal Civil Code and the Mexico City Civil Code, such a note lapses after three years unless it is extended in time (art. 3035), and the rules vary by state, which adds cost to a property-based strategy.
Enforcement officials (actuarios/jueces ejecutores) act only under judicial authority; they cannot seize assets or garnish accounts without a court order. Enforcement timelines typically run from a few months to well over a year, depending on asset type and whether the debtor raises defences or appeals.
Step 4 - How do insolvency procedures affect debt recovery in Mexico?
A Mexican merchant debtor (comerciante) enters concurso mercantil (business insolvency) when it meets a two-part test: 35% or more of its obligations are 30 or more days overdue, and its liquid assets cover less than 80% of that overdue amount (Ley de Concursos Mercantiles art. 10). Concurso mercantil applies only to comerciantes; individual, non-merchant insolvency is a separate, state-level Civil Code matter.
Types of insolvency and likely outcomes in Mexico
- Conciliación: the first stage, aimed at a court-supervised restructuring agreement between the debtor and its creditors; runs up to 185 days, extendable to a maximum of 365 days in total (LCM arts. 2-3, 145).
- Quiebra (liquidation): opens if conciliación fails or is not viable; the debtor's assets are realised and distributed to creditors by statutory priority.
- Who can file: the debtor itself, any creditor, or the Public Prosecutor (Ministerio Público) can petition for concurso mercantil.
Creditor priority in a Mexican concurso mercantil
Distributions follow a fixed order: singularly-privileged claims first, then secured (real-guarantee) creditors, then special-privilege claims, then common creditors pro rata, then subordinated claims last (LCM arts. 217-224). Labour and tax claims, and the costs of administering the estate, are prioritised within or ahead of this order.
| Priority rank | Creditor class |
|---|---|
| 1 | Singularly-privileged claims |
| 2 | Secured (real-guarantee) creditors |
| 3 | Special-privilege claims |
| 4 | Common creditors (pro rata) |
| 5 | Subordinated claims |
The insolvency process for creditors in Mexico
- Detect and verify: identify the proceeding (conciliación or quiebra), the court, and the appointed conciliador/síndico.
- Stop individual action: concurso mercantil generally pauses individual enforcement against the debtor's assets.
- File a proof of claim: submit supporting documentation (contract, invoices, statement of account) within the court-set deadlines.
- Participate: attend creditors' meetings and monitor the conciliación timetable; active participation improves standing under the priority rules.
- Track distributions: in quiebra, recovery follows the statutory priority order above; unsecured, common creditors are typically paid last and often recover only a share of their claim.
Fees, interest and who pays what in Mexico
- Our fee: success-based, No Cure, No Pay (see pricing).
- Court & enforcement fees: lawyer fees are agreed with the lawyer and quoted to you first, and court execution costs such as an embargo or a judicial auction arise only if the case escalates to a juicio ejecutivo mercantil or a juicio oral mercantil; a Mexican court can order the losing party to pay costas (partial cost reimbursement) under the Código de Comercio, assessed under local tariffs and decided case by case. There is no state filing fee for Mexican civil/commercial judicial acts (art. 1081).
- Statutory debtor items: where no contractual rate is agreed, a commercial debt accrues statutory default interest at 6% per year (Código de Comercio art. 362), and a civil debt accrues interest at 9% per year (Código Civil Federal art. 2395), both from the day after the due date. An agreed rate can be reduced by a court if it is usurious (Supreme Court case law of 2014 on pagarés, 1a./J. 46/2014 and 47/2014). Interest and any court-awarded costas can be added to the claim.
- Who keeps what: recovered principal is yours; interest and costs follow the contract, the statute and the court's order.
Cross-border debt collection in Mexico
A judgment from another country is not enforced in Mexico automatically. It first has to be recognised by a Mexican court in a homologación procedure (Código de Comercio art. 1347-A; Código Federal de Procedimientos Civiles arts. 569-577, which the new national procedure code replaces with arts. 1181-1191). Among other conditions, the foreign court must have had jurisdiction, the debtor must have been served personally, the judgment must be final and must not conflict with Mexican public order, and its authenticity must be proved; a Mexican court may refuse recognition where the other country does not enforce Mexican judgments. Mexico is a party to the Hague Apostille Convention (in force since 14 August 1995) and to the 1979 Inter-American Convention on the Extraterritorial Validity of Foreign Judgments and Arbitral Awards, but not to the Hague 2019 Judgments Convention. Our partner points out that recognition brings its own costs, such as apostilles and certified translations, so for a debtor whose assets are in Mexico it is often simpler to bring the claim in Mexico from the start.
A clause in your contract or pagaré can choose the competent court, but only one at either party's domicile, the place of performance or where the property is (Código de Comercio art. 1093). Without such a clause, the claim is filed where the debtor was to pay or is domiciled. Mexico is a large federal country with local rules in every state, so our partner's advice to foreign sellers is to check a Mexican buyer carefully before selling on credit.
Partners in our network
These firms are partners in our network for this country. Open a profile to learn more about each one. If court action is needed on your case, your partner sends a quote on the platform; nothing starts until you accept it.
- Verified specialists
- Nothing starts until you accept the quote
- Fair, pre-negotiated rates
De Hoyos Aviles is a premier law firm in Mexico City offering effective Debt Collection services in Mexico, established in 1964, renowned for its Martindale-Hubbell Peer AV Preeminent Rating, and serving clients across the United States, Canada, and Europe.


DCS Mexico is a premier debt recovery agency in Torreon offering effective Debt Collection services in Mexico, positioned as the go-to partner with a foundation since 2009, ranked 8th among Top 10 Proveedores, and a member of APCOB.
ATIVO is a B2B debt collection agency in Mexico City that has collected unpaid commercial invoices since 2008. As Debitura's partner in Mexico, it handles pre-legal collection on No Cure, No Pay terms and coordinates court action through partner lawyers when you approve a quote.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.






