
Debt Collection Agency in the UK: No Win, No Fee
If a UK business customer has not paid an invoice, Debitura routes eligible claims to Miller James Limited in Belfast or Oriel Collections Limited in Cheltenham. See the pre-legal fee before you proceed and track the case online.


Questions about your case?
Write to us, we reply by email.

Why choose Debitura for debt collection in UK
Getting started with UK debt collection
- Check which UK business placed the order. Compare the legal name and billing address on the signed order with the name on the invoice. If a Manchester buyer uses a trading name in emails, record both names and attach the order or correspondence that connects them. If the records name two companies, flag the difference for review.
- Check that each invoice represents a separate balance. For example, if you sent a pro forma before shipping and a final invoice afterward, identify the final invoice and explain what the earlier document was for. If you reissued an invoice, note which version replaced the original. Include the due date, currency, unpaid amount and any credit notes.
- Submit one clear file for review. Upload the invoice and available supporting documents in the Debitura dashboard for the collection partner to review. If you receive a quote, check that it covers the live invoice and the correct buyer. Follow updates and requests for information in the case.
Already using accounting software or an ERP? Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
Transparent, success-based pricing
With Debitura you pay a success fee only when money is recovered. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in the United Kingdom?
Debt collection in the United Kingdom starts with an amicable phase handled locally by your assigned partner, Miller James Limited or Oriel Collections Limited: reminders and a formal demand for payment, aimed at full payment or a written acknowledgement of the debt. Most undisputed claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic; your partner assesses the legal route, and you approve a legal quote before any court step.
- 70-85% of commercial debts resolve at the amicable stage (industry estimate)
- Typical amicable phase: 30-90 days
- Legal action available if debtor disputes or ignores
- Multiple enforcement routes: bailiffs, HCEOs, charging orders
The four steps from unpaid invoice to recovered cash
- Amicable collection: reminders, a formal demand and negotiation, handled locally by your assigned partner, Miller James Limited or Oriel Collections Limited. Most undisputed claims are resolved here, without going to court.
- Enforceable title: if the debtor still does not pay, your partner assesses the legal route to obtain an enforceable title, and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a title, the enforcement authorities can attach and sell assets, freeze bank accounts and garnish income, and take other measures until the claim is recovered.
- Insolvency: if the debtor turns out to be insolvent, recovery depends on the local insolvency proceedings and is often uncertain. Any step in those proceedings is quoted separately and only starts if you accept.
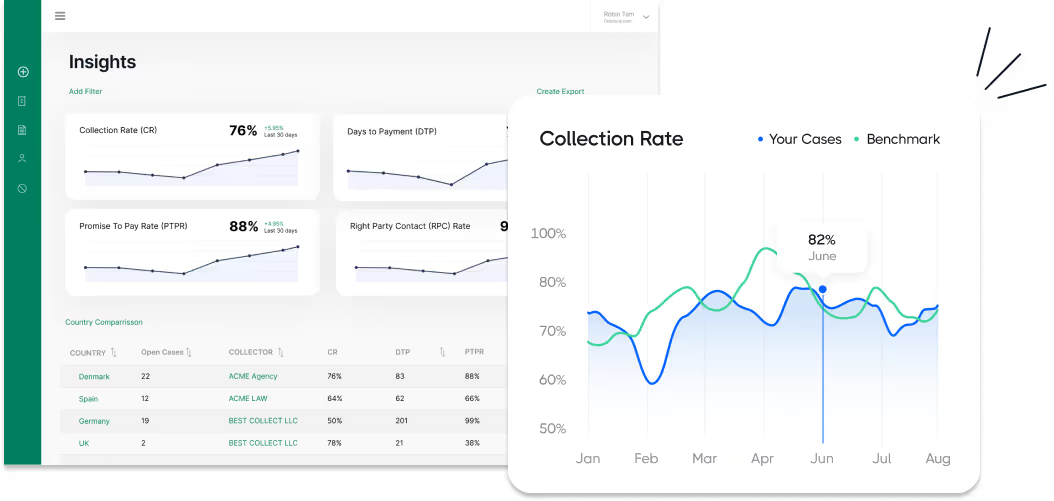
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for the United Kingdom follows in the guide below.
Business and commercial debt recovery in the UK
When a UK company does not pay your invoice, the unpaid amount is a commercial debt, and UK law gives you tools beyond a reminder. You can add statutory interest and a fixed sum to the claim, and a letter before action comes before any court claim. Business debt recovery in the UK through Debitura works on the same terms as in every other country we cover: your claim is handled by one of our two exclusive UK partners, Miller James Limited (Belfast) or Oriel Collections Limited (Cheltenham), both FCA-authorized debt collection firms, and you pay a success fee only when money is recovered.
Statutory interest under the Late Payment Act
Between businesses, the Late Payment of Commercial Debts (Interest) Act 1998 gives you statutory interest of 8% a year above the Bank of England base rate, unless your contract sets a different rate. On top of the interest you can claim a fixed sum for each invoice: £40 for a debt under £1,000, £70 for £1,000 up to £9,999.99 and £100 for £10,000 or more. Work out what you can add with our late payment interest calculator.
The letter before action
Before a court claim against a company, the Practice Direction on Pre-Action Conduct and Protocols expects a letter before action that sets out the claim and gives your customer a reasonable time to reply, which is 14 days in a straightforward case. If your customer is a sole trader, the Pre-Action Protocol for Debt Claims applies instead and gives 30 days. Our demand letter guide has a UK letter before action template for claims from one company to another.
When to use a debt recovery agency
Commercial debt recovery is worth handing to a debt recovery agency once your own reminders and letters have not worked. For commercial debt collection in the UK, your assigned partner (Miller James Limited or Oriel Collections Limited) contacts your customer and negotiates payment. If the customer still does not pay, you receive a legal quote, with court costs stated separately, and nothing goes to court unless you accept it. See how our commercial collection agency service works for claims in the UK and abroad.
Debt collection in the United Kingdom - the complete 2026 guide
Built for overseas and domestic creditors, in-house counsel and finance teams, this guide sets out how debt collection in the UK (England and Wales, with Scotland and Northern Ireland noted) works end to end: the legal framework and courts, who does what, the limitation and late-payment interest rules, the Pre-Action Protocol and the County Court claim to a judgment, enforcement after a CCJ, and insolvency.
On this page:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).

Contributing local experts:
Last updated:

Debt collection in the United Kingdom - quick answers
The UK runs a structured pre-action protocol, an online money-claim system and a range of post-judgment enforcement options, with statutory late-payment protection for businesses.
How much does debt collection cost in the UK?
Pre-legal collection is commonly success-based (No Cure, No Pay). Issuing a court claim carries a scaled fee, from £35 for the smallest claims up to 5% of the value for claims between £10,000 and £200,000. On a B2B debt the supplier can also add fixed recovery compensation and interest to the sum claimed.
How long does debt collection take in the UK?
The Pre-Action Protocol for Debt Claims gives the debtor 30 days to respond to a Letter of Claim before proceedings start. If a claim is issued and no defence is filed, the creditor can request judgment in default (a County Court Judgment, or CCJ), which is usually quick; a defended claim is allocated to a track and takes longer.
What are the limitation periods and interest rules in the UK?
For a simple contract debt in England and Wales the limitation period is six years from the date the cause of action accrued (Limitation Act 1980, section 5); Scotland and Northern Ireland have their own periods. On a late commercial (B2B) payment, statutory interest is 8% above the Bank of England base rate (Late Payment of Commercial Debts (Interest) Act 1998), plus fixed recovery compensation of £40, £70 or £100 depending on the size of the debt.
| Topic | Rule |
|---|---|
| Limitation (simple contract, E&W) | 6 years (Limitation Act 1980, s.5). |
| B2B statutory interest | 8% above the Bank of England base rate (1998 Act). |
| Fixed recovery compensation | £40 / £70 / £100 by debt size. |
| Enforceable title, main route | County Court claim, then default judgment (CCJ) if undefended. |
What documents do I need to collect a debt in the UK?
The Letter of Claim must set out the amount of the debt, whether interest and charges are continuing, and the agreement details, and must enclose an up-to-date statement of account plus the Information Sheet, Reply Form and Financial Statement form. Keep the contract, invoices and correspondence to support the claim.
Which route should my claim take in the UK?
A specified money claim is issued through Money Claim Online (up to £99,999.99) or on paper. On allocation it goes to a track: the small claims track up to £10,000, the fast track to £25,000, the intermediate track to £100,000, and the multi-track above that or for the most complex claims.
Who does what in the United Kingdom debt collection?
Recovery in the UK involves FCA-regulated collection firms for the amicable phase, solicitors for litigation, and enforcement agents after judgment. Debitura supports you across all stages through its two exclusive UK partners, Miller James Limited and Oriel Collections Limited.
Collection firms in the United Kingdom
Debt collecting is a regulated credit-related activity: a firm carrying it on must hold the appropriate FCA permission and follow the Consumer Credit sourcebook (CONC), in particular CONC 7 on arrears, default and recovery. Many firms also follow the Credit Services Association Code of Practice.
Solicitors in the United Kingdom
Solicitors, regulated by the Solicitors Regulation Authority, conduct litigation and higher-value or disputed recovery, and advise on High Court enforcement.
Enforcement agents in the United Kingdom
County Court enforcement is by County Court bailiffs under a warrant of control; High Court enforcement is by High Court Enforcement Officers under a writ of control. Both take control of goods under Schedule 12 of the Tribunals, Courts and Enforcement Act 2007, with independent oversight from the Enforcement Conduct Board.
Which laws and courts apply to debt collection in the United Kingdom?
UK debt recovery (England and Wales) runs on the Civil Procedure Rules and a set of statutes, with separate systems in Scotland and Northern Ireland.
The civil court system in the United Kingdom
Money claims start in the County Court, or the High Court for higher-value or complex claims, and are allocated to the small claims, fast, intermediate or multi-track. In Scotland, debt actions run in the Sheriff Court, with Simple Procedure for claims up to £5,000; Northern Ireland has its own separate court system.
Key legislation in the United Kingdom
- Civil Procedure Rules and the Pre-Action Protocol for Debt Claims: how a claim is prepared and run.
- Limitation Act 1980: the six-year limitation period for simple contract debts.
- Late Payment of Commercial Debts (Interest) Act 1998: B2B statutory interest and recovery compensation.
- Tribunals, Courts and Enforcement Act 2007: taking control of goods (Schedule 12); Insolvency Act 1986: corporate and personal insolvency.
Conduct and data protection in the United Kingdom
Collection conduct is supervised by the FCA under CONC, and debtor data is protected by the UK GDPR and the Data Protection Act 2018, regulated by the Information Commissioner's Office.
Step 1 - How does amicable (pre-legal) debt collection work in the United Kingdom?
Pre-legal collection recovers an unpaid invoice without a full court claim. Where a business is claiming from an individual or a sole trader, the Pre-Action Protocol for Debt Claims applies, and the creditor must send a Letter of Claim before starting proceedings. The aim is full payment or an agreed payment arrangement.
| Protocol step | Effect |
|---|---|
| Letter of Claim | Sets out the debt and encloses the Information Sheet, Reply Form and Financial Statement. |
| 30-day response | The debtor has 30 days from the date on the letter to reply before proceedings may start. |
| Disclosure | A requested document must be provided within 30 days, or the reason given. |
| Taking stock | At least 14 days' notice of intention to issue proceedings where no agreement is reached. |
When to escalate to court in the United Kingdom
Escalate once the protocol steps are exhausted and the debt is unpaid. Complying with the protocol matters, because the court takes non-compliance into account when giving directions and awarding costs.
Step 2 - How do you obtain an enforceable title in the United Kingdom?
To enforce a debt you need a court judgment. In England and Wales the main route is a specified money claim in the County Court, resulting in a County Court Judgment (CCJ).
Issuing the claim
The creditor issues a specified money claim through Money Claim Online (up to £99,999.99) or on paper. If the defendant files no defence or acknowledgement in time, the creditor can request judgment in default. Court issue fees are scaled by value, from £35 for the smallest claims to 5% of the value between £10,000 and £200,000.
The judgment and the register
An undefended claim produces a default CCJ; a defended claim is allocated to a track and decided at a hearing. A judgment is normally entered on the Register of Judgments, Orders and Fines, where most entries remain for six years unless the debt is paid within one month.
Determining the appropriate court in the United Kingdom
Money claims start in the County Court; the High Court is used for higher-value or complex claims. In Scotland the Sheriff Court applies (Simple Procedure up to £5,000), and Northern Ireland has its own procedure.
More on court proceedings in the United Kingdom
Tracks and hearing fees
On allocation a claim goes to the small claims track (up to £10,000, with restricted cost recovery), the fast track (to £25,000), the intermediate track (to £100,000) or the multi-track. Hearing fees range from £27 on the small claims track to £1,334 on the intermediate or multi-track.
Step 3 - How does debt enforcement work in the United Kingdom?
With a CCJ that the debtor still does not pay, the creditor chooses an enforcement method to match the debtor's circumstances. A judgment cannot be enforced while the debtor has Breathing Space protection under the Debt Respite Scheme.
Ways to enforce a judgment in the United Kingdom
- Warrant or writ of control: County Court bailiffs (warrant) or High Court Enforcement Officers (writ) take control of goods; for a debt between £600 and £5,000 the creditor can choose the county court or the High Court.
- Attachment of earnings order: the court orders deductions from the debtor's wages.
- Third-party debt order: money in the debtor's bank or business account is frozen and paid to the creditor.
- Charging order: the debt is secured against the debtor's land or property, with a possible later order for sale.
The enforcement process in the United Kingdom
The creditor applies on the relevant court form (for example a warrant of control, or an order to obtain information where the debtor's means are unclear), and the chosen measure is carried out under Schedule 12 of the Tribunals, Courts and Enforcement Act 2007. Proceeds are applied to the judgment debt, interest and costs.
Step 4 - How do insolvency procedures affect debt recovery in the United Kingdom?
Where the debtor cannot pay, insolvency under the Insolvency Act 1986 becomes the collective route, and enforcement generally gives way to the insolvency process. A statutory demand often precedes a petition.
Corporate insolvency
A creditor can serve a statutory demand on a company for a debt exceeding £750; if it is unpaid after 21 days the company is deemed unable to pay its debts and the creditor may present a winding-up petition (court fee £343 plus the official receiver's deposit). Companies may also enter administration, a company voluntary arrangement or liquidation.
Personal insolvency
To petition to bankrupt an individual, the creditor must be owed at least £5,000 (petition fee £343 plus deposit). Individuals may also use an Individual Voluntary Arrangement or a Debt Relief Order. A petition cannot proceed while the debtor is in Breathing Space.
The insolvency process for creditors in the United Kingdom
Submit your proof of debt to the appointed officeholder with the contract, invoices and statement of account, and monitor distributions; secured and preferential claims rank ahead of unsecured trade creditors, who often recover only part of the debt.
Fees, interest and who pays what in the United Kingdom
- Our fee: success-based, No Cure, No Pay (see pricing).
- Court & enforcement fees: statutory court and enforcement fees apply only if the case escalates to legal action, and are generally recoverable from the debtor if you win.
- Statutory debtor items: on a B2B debt, statutory interest of 8% above the Bank of England base rate, fixed recovery compensation of £40, £70 or £100 by debt size, and reasonable further recovery costs (Late Payment of Commercial Debts (Interest) Act 1998) can be added to the claim.
- Who keeps what: recovered principal is yours; interest and costs follow the contract, the statute and the court's order.
Cross-border debt collection in the United Kingdom
Since Brexit, the European Payment Order and the European Small Claims Procedure are no longer available for UK claims, and the Brussels I recast Regulation no longer applies to UK proceedings started after 31 December 2020. The UK is instead a party in its own right to the Hague Convention on Choice of Court Agreements (2005), which supports exclusive jurisdiction clauses, and to the Hague 2019 Judgments Convention, which broadens the recognition and enforcement of civil and commercial judgments between contracting states. Where no convention applies, recognition and enforcement fall back on common-law rules, so cross-border claims are best assessed case by case. Our guide on how to enforce a judgment abroad sets out each route.
Partners in our network
These firms are partners in our network for this country. Open a profile to learn more about each one. If court action is needed on your case, your partner sends a quote on the platform; nothing starts until you accept it.
- Verified specialists
- Nothing starts until you accept the quote
- Fair, pre-negotiated rates
OneLaw Chambers is a premier law firm in London offering effective Debt Collection services in the United Kingdom, established in 2019, renowned for winning the Most Trusted Immigration & Civil Litigation Firm 2023 award, and a member of the Solicitors Regulation Authority.


STUDIO LEGALE - LAW FIRM NIEDDU is a premier law firm in Alghero offering effective Debt Collection services in Italy, positioning itself as the go-to partner with over 26 years of experience.
Safe Collections Ltd is a premier debt recovery agency in Leyland offering effective Debt Collection services in the United Kingdom, founded in 1984, operating on a no-collection, no-commission basis, and serving clients globally with a 4.9/5 Trustpilot rating.
Taurus Collections is a premier debt recovery agency in the UK offering effective Debt Collection services, established in 2010, with a no win, no fee model, serving clients worldwide, and is a Debitura partner, adhering to Debitura's No Cure, No Pay standard terms and pricing.
Debt Collection Service Limited is a premier debt recovery agency in Bristol offering effective debt collection services in the United Kingdom, established in 2005, providing cost-effective solutions with memberships in the Federation of Small Businesses and the Information Commissioner’s Office.
Slater Byrne Recoveries is a premier debt recovery agency in Manchester offering effective Debt Collection services in the United Kingdom, operating since 2008 with a "No Win, No Fee" model, over 500 client reviews, and memberships in the IMA and International Trade Council.
Debt Collection Services UK Ltd is a premier debt recovery agency in Wakefield offering effective Debt Collection services in the United Kingdom, founded in 2003, operating on a no-win, no-fee basis, and accredited by the FCA and Credit Services Association.
Credit Limits International Ltd is a premier debt recovery agency in Faversham offering effective Debt Collection services in the UK, renowned for its ethical no-win no-fee model, founded in 2009, and a proud member of the TCM Group, which it states serves 135 countries.
Hariharan and Hariharan (UK) Law Offices LLP is a premier law firm in London offering effective Debt Collection services in the United Kingdom, positioning itself as the go-to partner for debt recovery with a foundation in 2023, an hourly rate of USD 650, and memberships in The Legal500 and Advocates for International Development, serving clients across the UK, India, and the European Union.
Miller James Limited is a premier debt recovery agency in the United Kingdom offering effective Debt Collection services, recognized as the go-to partner since 1995 and a Debitura partner in Northern Ireland, providing No Cure No Pay solutions under Debitura's No Cure, No Pay standard terms and pricing, with memberships in the Credit Services Association and Financial Conduct Authority, serving both Northern Ireland and the Republic of Ireland.
Oriel Collections Limited is a premier debt recovery agency in Cheltenham offering effective Debt Collection services in the United Kingdom, established in 2003, regulated by the FCA, and awarded the CSA Merit Award for Working with Vulnerable Customers, serving clients globally.
Redwood Collections is a premier debt recovery agency in Croydon offering effective Debt Collection services in the United Kingdom, established in 2009, operating with transparent fixed fees, FCA regulation, CSA membership, and serving clients worldwide.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.






