Debt Collection Agency in Nevada: No Cure, No Pay
For unpaid invoices from business customers in Nevada: your claim is handled by a licensed local collection partner, matched to your case, under one contract, and you only pay when money is recovered. All actions follow Nevada law, and you track everything in one dashboard. Prefer to learn first? Read our Nevada debt collection guide.


Questions about your case?
Write to us, we reply by email.
Our local debt collection partners
Debitura is a platform, not a single agency: your case is routed to the licensed collection partner best matched to your claim type, debtor profile and industry. After that, we follow their results on our platform: how much they collect, how fast they respond and how clients rate them.
- Verified specialists
- Fee shown before you submit
- Fair, pre-negotiated rates
Direct Recovery Associates, Inc. is a premier debt recovery agency in Agoura Hills offering effective Debt Collection services in the United States, founded in 1992, with a global reach and performance-based billing, ensuring client satisfaction.
See full partner profile


Aaron Bryant Stewart & Cross is a premier debt recovery agency in the United States offering effective No Cure No Pay Debt Collection services, established in 2006 and serving North America and select international markets, as a Debitura partner in the U.S., providing collections based on Debitura's No Cure, No Pay standard terms and pricing, and is a member of ACA International.
See full partner profile
Debt Recovery Resources is a premier debt recovery agency in the United States offering effective debt collection services, a member of the CLLA, partnering with Debitura for No Cure No Pay solutions.
See full partner profileWhy choose Debitura for debt collection in Nevada?
Debt collection in Nevada, matched to a local partner
Debitura recovers unpaid invoices from debtors in Nevada through our platform: submit your claim, and we assign it to the best-matching licensed partner working on a No Cure, No Pay basis while you track progress in real time. Your Nevada panel includes Direct Recovery Associates, licensed by the California Department of Financial Protection and Innovation (DFPI Lic. #10186-99) and collecting commercial debt since 1992, alongside Debt Recovery Resources, registered with the Texas Secretary of State (Reg. #0802087763).
- No Cure, No Pay: Pay only when money is recovered.
- Quick setup: Submit invoices in a few clicks.
- Real-time tracking: Monitor progress live in one portal.
- Local compliance: Collection follows Nevada's Collection Agencies Act (NRS Chapter 649) and the FDCPA.
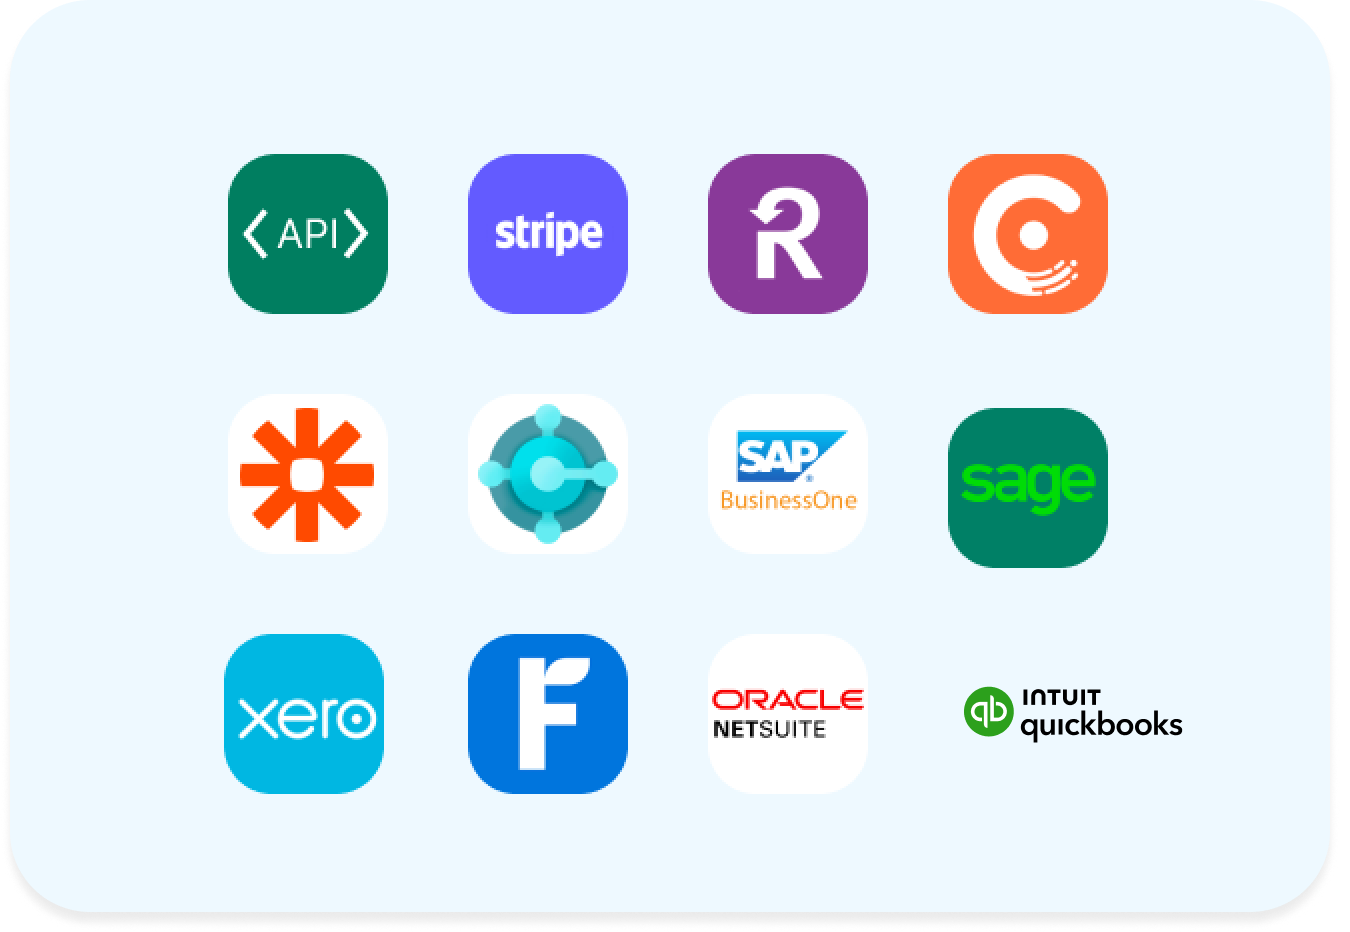
Start recovering your Nevada claims in 2 minutes
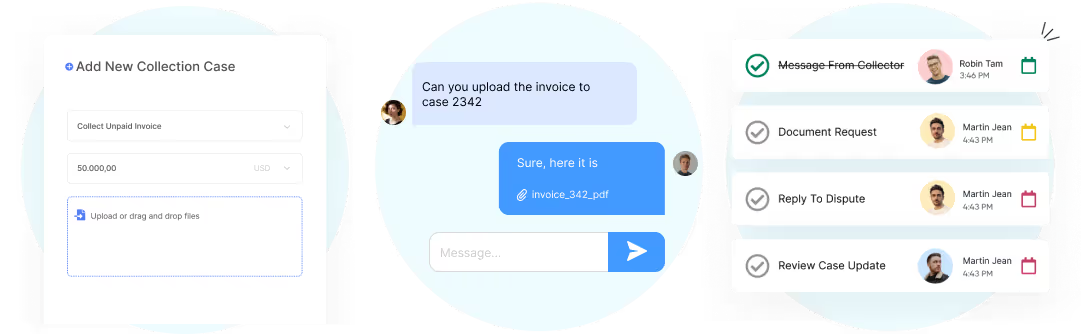
- Submit your claim: upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- Local collection begins: your Nevada panel partner starts amicable recovery; if escalation is needed, Nevada's Justice Courts hear claims up to $10,000 (Nev. Rev. Stat. §73.010(1)).
- Get paid: recovered funds are remitted to you, with our fee deducted on success only.
Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size. On a $10,000 invoice to a US business, under 12 months overdue, the success fee is 15% ($1,500), shown before you submit. Minimum claim: $500. No fee if nothing is recovered.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Nevada?
Debt collection in Nevada starts with an amicable phase: your case is handled by your assigned partner, which issues demands and pursues payment or a written acknowledgment of the debt. Most undisputed commercial claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic; your partner assesses the legal route (typically Justice Court for claims up to $10,000, or District Court above), and you approve a legal quote before any court step.
- Submit in 2 minutes: upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- No Cure, No Pay: pre-legal collection is success-based, with no setup fees or subscriptions.
- You stay in control: legal escalation only happens after you approve a legal quote.
- Get paid: recovered funds are remitted to you; fees are deducted on success only.
The four steps from unpaid invoice to recovered cash
- Amicable collection: demands and negotiation handled by your Nevada panel partner. Most undisputed claims resolve here, without going to court.
- Enforceable title: if the debtor does not pay, your partner assesses the legal route, and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a judgment, creditors can use writs of execution and post-judgment writs of garnishment reaching both earnings and bank accounts (NRS Chapters 21 and 31); Nevada caps wage garnishment at the lesser of 18-25% of disposable earnings or the amount above 50 times the federal minimum wage (Nev. Rev. Stat. §31.295(2)).
- Insolvency: if the debtor turns out to be insolvent, recovery depends on the local insolvency proceedings and is often uncertain. Any step in those proceedings is quoted separately and only starts if you accept.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Nevada - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in Nevada - the complete 2026 guide
For in-house counsel, finance teams and out-of-state creditors, this Nevada guide covers 2026 debt recovery end-to-end - licensing, limitation and interest, court routes, garnishment and post-judgment enforcement - plus step-by-step tools and compact tables to act correctly, fast.
What we will cover:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).
Contributing local experts:
Last updated:

Debt collection in Nevada - quick answers
| Question | Answer |
|---|---|
| Main route | Demand letter → amicable collection → Justice Court (claims up to $10,000) or District Court → post-judgment enforcement |
| Statute of limitations | 6 years for written contracts and judgments; 4 years for oral contracts and open accounts (Nev. Rev. Stat. §11.190) |
| Late-payment interest | Prime rate at the largest Nevada bank plus 2% when no rate is agreed - 8.75% as of January 1, 2026 (Nev. Rev. Stat. §99.040(1), rate published by the Nevada FID) |
| Small claims | Justice Court hears claims up to $10,000 (Nev. Rev. Stat. §73.010(1)); filing fees range about $66 to $196 depending on the claim amount |
| Wage garnishment | Capped at the lesser of 18% (wages of $770/week or less) or 25% (wages above $770/week) of disposable earnings, or the amount above 50x the federal minimum wage (Nev. Rev. Stat. §31.295(2)) |
| Court & enforcement fees | State fees apply only if the case escalates to legal |
| Our fee | Success fee only - No Cure, No Pay |
How much does debt collection cost in Nevada?
With Debitura you pay a success fee only on amounts actually recovered, with no upfront or monthly costs; the exact rate depends on your claim, see our pricing. Court fees apply only if the case escalates to legal: Nevada Justice Court filing fees run from about $66 to $196 depending on the claim amount (North Las Vegas Township fee schedule, Nev. Rev. Stat. Chapter 73), and enforcement writ costs vary by county. These state fees are advanced by the creditor and can generally be recovered as court costs if you prevail.
How long does debt collection take in Nevada?
Most undisputed commercial claims are resolved in the amicable phase without court involvement. If escalation is needed, Justice Court is the fastest judicial route for claims up to $10,000, while contested District Court cases take substantially longer. Enforcement timing depends on locating non-exempt assets and the debtor's earnings or bank accounts reachable by a post-judgment writ of garnishment.
What are the limitation and interest rules in Nevada?
The statute of limitations is 6 years for written contracts and judgments, and 4 years for oral contracts and open accounts (Nev. Rev. Stat. §11.190). A partial payment restarts the clock (§11.200(1)), but a new promise only restarts it if made in a signed writing (§11.390). Without an agreed rate, interest runs at the prime rate at the largest Nevada bank plus 2% - 8.75% as of January 1, 2026 per the Nevada Financial Institutions Division's published rate table - readjusted every January 1 and July 1 (Nev. Rev. Stat. §99.040(1)). Contracts may set any agreed rate in writing (§99.050(1)); there is no general usury cap on ordinary commercial contracts.
What documents do I need to start debt collection in Nevada?
Start with the unpaid invoice or contract, proof of delivery or performance, and any correspondence showing the debtor acknowledged the debt. A written acknowledgment or partial-payment record is especially useful, since it can restart Nevada's limitation period under Nev. Rev. Stat. §11.200(1).
What is the court route for debt collection in Nevada?
Claims up to $10,000 go through a Nevada Justice Court under the small-claims procedure of NRS Chapter 73; larger or contested claims proceed in Nevada District Court. Corporate creditors may be represented in Justice Court by a director, officer or employee without an attorney (Nev. Rev. Stat. §73.012).
Who does what in Nevada debt collection?
Collection agencies
Nevada requires a collection agency to hold a license from the Commissioner of Financial Institutions before doing business in the state (Nev. Rev. Stat. §649.075(1)); this also reaches out-of-state agencies collecting from Nevada debtors or on behalf of Nevada creditors (§649.075(2)). Licensees must also post a surety bond, starting at $35,000 and rising to $60,000 based on the licensee's average trust-account balance (Nev. Rev. Stat. §649.105). Debt buyers - businesses that purchase charged-off claims to collect them - must hold the same collection-agency license (Nev. Rev. Stat. §649.031). Nevada's licensing law is not limited to consumer debt: a claim is defined broadly as any past-due obligation for payment of money (§649.010), so commercial/B2B collection is within scope alongside consumer accounts. You can verify a license on the Nevada Financial Institutions Division's License Look-Up tool.
Courts and enforcement officers
Nevada Justice Courts hear small claims up to $10,000 (Nev. Rev. Stat. §73.010), while Nevada District Courts handle larger and contested claims. Once a judgment is entered, enforcement runs through writs of execution and writs of garnishment issued under NRS Chapters 21 and 31, carried out by the county sheriff or constable.
Attorneys
Attorneys are not required for Justice Court small-claims filings, where a corporate creditor may appear through a director, officer or employee (Nev. Rev. Stat. §73.012), but are typically used for District Court litigation and post-judgment enforcement.
Regulators
The Commissioner of Financial Institutions, through the Nevada Financial Institutions Division (FID) within the Department of Business and Industry, licenses and supervises collection agencies under NRS Chapter 649 (Nev. Rev. Stat. §649.026). The Nevada Attorney General separately enforces the state's general Deceptive Trade Practices Act (Nev. Rev. Stat. §§598.0903-598.0999).
Which laws and courts apply to debt collection in Nevada?
Key legislation
Nevada collection agencies operate under the Collection Agencies Act, NRS Chapter 649, together with the federal Fair Debt Collection Practices Act (FDCPA, 15 U.S.C. §§1692 et seq.) - NRS §649.313 expressly requires agents to comply with the FDCPA, and a violation of it is treated as a state-law violation for licensees (NRS §649.370). In 2023, SB 276 substantially overhauled Chapter 649: it added the debt-buyer licensing requirement (NRS §649.031), new remote-location FDCPA compliance duties (§649.313), and a hospital-claim disclosure requirement confirming that payment does not waive the statute of limitations (§649.332). Industry compliance trackers (Buckley LLP, insideARM, ACA International) also report that SB 276 bars agencies from suing on a debt they know or should know is time-barred; Debitura has not independently verified the operative statutory text of this specific provision, so treat it as reported rather than confirmed.
Civil court system
Nevada Justice Courts (township-level) hear claims up to $10,000 under the small-claims procedure of NRS Chapter 73, and general civil claims within their jurisdictional limits; Nevada District Courts handle larger and contested civil claims and hear appeals from Justice Court.
Consumer protection
Nevada's Deceptive Trade Practices Act (Nev. Rev. Stat. §§598.0903-598.0999) is enforced by the Nevada Attorney General, with civil penalties up to $10,000 per violation, alongside the federal FDCPA.
Step 1 - How does amicable (pre-legal) debt collection work in Nevada?
Your assigned partner sends demands and negotiates payment or a written acknowledgment of the debt. Nevada's limitation period runs from the last transaction or last payment (Nev. Rev. Stat. §11.200(1)) - a partial payment on principal or interest made after the debt is due restarts the clock, but any other new promise or acknowledgment only restarts it if it is in writing and signed by the debtor (§11.390).
When to escalate to court in Nevada
Escalation is never automatic. Your partner recommends legal action when amicable contact fails and the claim remains within the statute of limitations - 6 years for written contracts, 4 years for oral contracts and open accounts (§11.190) - and you approve a legal quote before any court step.
Step 2 - How do you obtain an enforceable title in Nevada?
Small claims (Justice Court)
| Item | Detail |
|---|---|
| Limit | $10,000 (Nev. Rev. Stat. §73.010(1)) |
| Filing fee | About $66 to $196 depending on the claim amount (North Las Vegas Township fee schedule, effective 3/27/2024) |
| Corporate representation | A director, officer or employee may represent the company - no attorney required (Nev. Rev. Stat. §73.012) |
| Attorney's fees | Generally not awarded at trial level, except as provided in NRS 597.860/597.870 (Nev. Rev. Stat. §73.040); capped at $15 on appeal (§73.050) |
No writ of attachment or garnishment may issue before judgment in a small-claims case; execution, including garnishment, is available after judgment as in other Justice Court cases (Nev. Rev. Stat. §73.020).
Ordinary proceedings (District Court)
Claims above the Justice Court limit, or disputed claims, proceed in Nevada District Court under ordinary civil procedure, typically with attorney representation.
Determining the court
Justice Court claims are filed in the township where the defendant resides, does business, or is employed, or - for contract claims - where the obligation was to be performed (Nev. Rev. Stat. §73.010(2)).
Step 3 - How does debt enforcement work in Nevada?
Ways to enforce a Nevada judgment
A judgment creditor can use a writ of execution to seize non-exempt property (NRS Chapter 21) or a post-judgment writ of garnishment to reach a debtor's earnings or funds held by a third party such as a bank (NRS Chapter 31, e.g. §31.249). Wage garnishment is capped at the lesser of 18% of disposable earnings (if the debtor's gross weekly wage was $770 or less when the writ issued), 25% (if it was more than $770), or the amount by which weekly disposable earnings exceed 50 times the federal minimum wage (Nev. Rev. Stat. §31.295(2)); these caps do not apply to court-ordered support, bankruptcy-court orders, or state/federal tax debts (§31.295(3)).
How to collect a Nevada judgment
A Nevada judgment must be enforced within 6 years (Nev. Rev. Stat. §11.190(1)(a)); a judgment creditor can renew it by filing an Affidavit of Renewal with the clerk within 90 days before it expires, and successive renewals are allowed (§17.214). Recording an abstract of judgment with a county recorder creates a lien on the debtor's non-exempt real property in that county for 6 years, renewable each time the judgment is renewed (§17.150). Judgment interest accrues at the prime rate at the largest Nevada bank plus 2% - 8.75% as of January 1, 2026 - from service of the summons and complaint until satisfied (§17.130(2)).
Step 4 - How do insolvency procedures work in Nevada?
Business and consumer insolvency in Nevada, as in every state, proceeds under the federal Bankruptcy Code. Any step in insolvency proceedings is quoted separately and only starts if you accept.
Fees, interest and who pays what in Nevada
Debitura charges a success fee only when your Nevada claim is recovered - no upfront or monthly cost.
Court and enforcement fees
Court and enforcement fees in Nevada apply only if the case escalates to legal: Justice Court filing runs about $66 to $196 depending on the claim amount, and enforcement (execution or garnishment) carries separate county fees. These are typically advanced by the creditor and can generally be recovered as costs if you prevail.
Interest and late fees the debtor owes
Without an agreed rate, Nevada law sets interest at the prime rate at the largest Nevada bank plus 2% - 8.75% as of January 1, 2026, readjusted every January 1 and July 1 (Nev. Rev. Stat. §99.040(1)). Parties may agree to any other rate in writing (§99.050(1)); Nevada has no general usury cap for ordinary commercial contracts - the only statutory rate cap applies to consumer credit for covered service members (36% APR or the Military Lending Act maximum, §99.050(2)-(3)). Nevada has no general statute capping late fees on ordinary commercial invoices; the commonly cited 5% figure is a residential-tenancy rule (NRS §118A.210(4)(b)) and does not apply to B2B claims.
Collecting a Nevada debt from out of state or abroad
Nevada has adopted the Uniform Enforcement of Foreign Judgments Act (Nev. Rev. Stat. §§17.330-17.400): an out-of-state or federal judgment can be filed with a Nevada district court clerk and, once filed, is enforced the same as a Nevada judgment, though execution cannot issue until 30 days after the debtor is given notice (§17.360). Nevada's licensing law also reaches collectors located out of state who pursue a Nevada debtor or collect for a Nevada creditor (Nev. Rev. Stat. §649.075(2)). Wherever your debtor is based, your case is routed to the best-matching partner across Debitura's network of 180 countries.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.

Need debt recovery beyond Nevada?
Explore our North America debt-collection hub for country-by-country playbooks. For coast-to-coast coverage in the US, see the U.S. debt-collection overview.
Neighboring states: California · Arizona