Debt Collection Agency in Maine: No Cure, No Pay
For unpaid invoices from business customers in Maine: your claim is handled by a licensed local collection partner, matched to your case, under one contract, and you only pay when money is recovered. All actions follow Maine law, and you track everything in one dashboard. Prefer to learn first? Read our Maine debt collection guide.


Questions about your case?
Write to us, we reply by email.
Our local debt collection partners
Debitura is a platform, not a single agency: your case is routed to the licensed collection partner best matched to your claim type, debtor profile and industry. After that, we follow their results on our platform: how much they collect, how fast they respond and how clients rate them.
- Verified specialists
- Fee shown before you submit
- Fair, pre-negotiated rates
Direct Recovery Associates, Inc. is a premier debt recovery agency in Agoura Hills offering effective Debt Collection services in the United States, founded in 1992, with a global reach and performance-based billing, ensuring client satisfaction.
See full partner profile


Aaron Bryant Stewart & Cross is a premier debt recovery agency in the United States offering effective No Cure No Pay Debt Collection services, established in 2006 and serving North America and select international markets, as a Debitura partner in the U.S., providing collections based on Debitura's No Cure, No Pay standard terms and pricing, and is a member of ACA International.
See full partner profile
Debt Recovery Resources is a premier debt recovery agency in the United States offering effective debt collection services, a member of the CLLA, partnering with Debitura for No Cure No Pay solutions.
See full partner profileWhy choose Debitura for debt collection in Maine?
Debt collection in Maine, matched to a local partner
Debitura recovers unpaid invoices from debtors in Maine through our platform: submit your claim, and we assign it to the best-matching licensed partner working on a No Cure, No Pay basis while you track progress in real time. Your Maine panel includes Debt Recovery Resources, a Southlake-based agency registered with the Texas Secretary of State (Reg. #0802087763) and a member of CLLA and ACA International, alongside Direct Recovery Associates, licensed by the California DFPI (Lic. #10186-99) and collecting commercial debt since 1992.
- No Cure, No Pay: Pay only when money is recovered.
- Quick setup: Submit invoices in a few clicks.
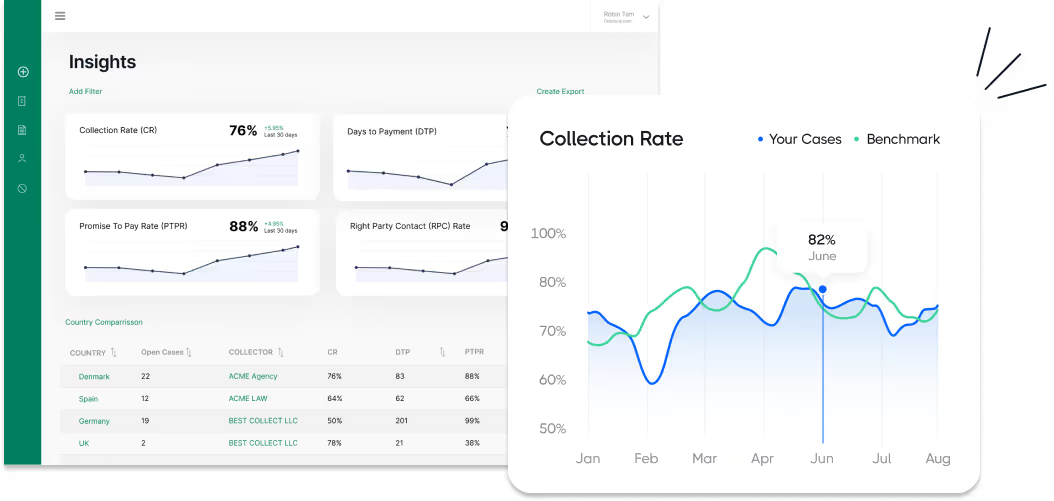
- Real-time tracking: Monitor progress live in one portal.
- Local compliance: Collection follows the Maine Fair Debt Collection Practices Act (32 M.R.S. ch. 109-A) and the FDCPA.
Start recovering your Maine claims in 2 minutes
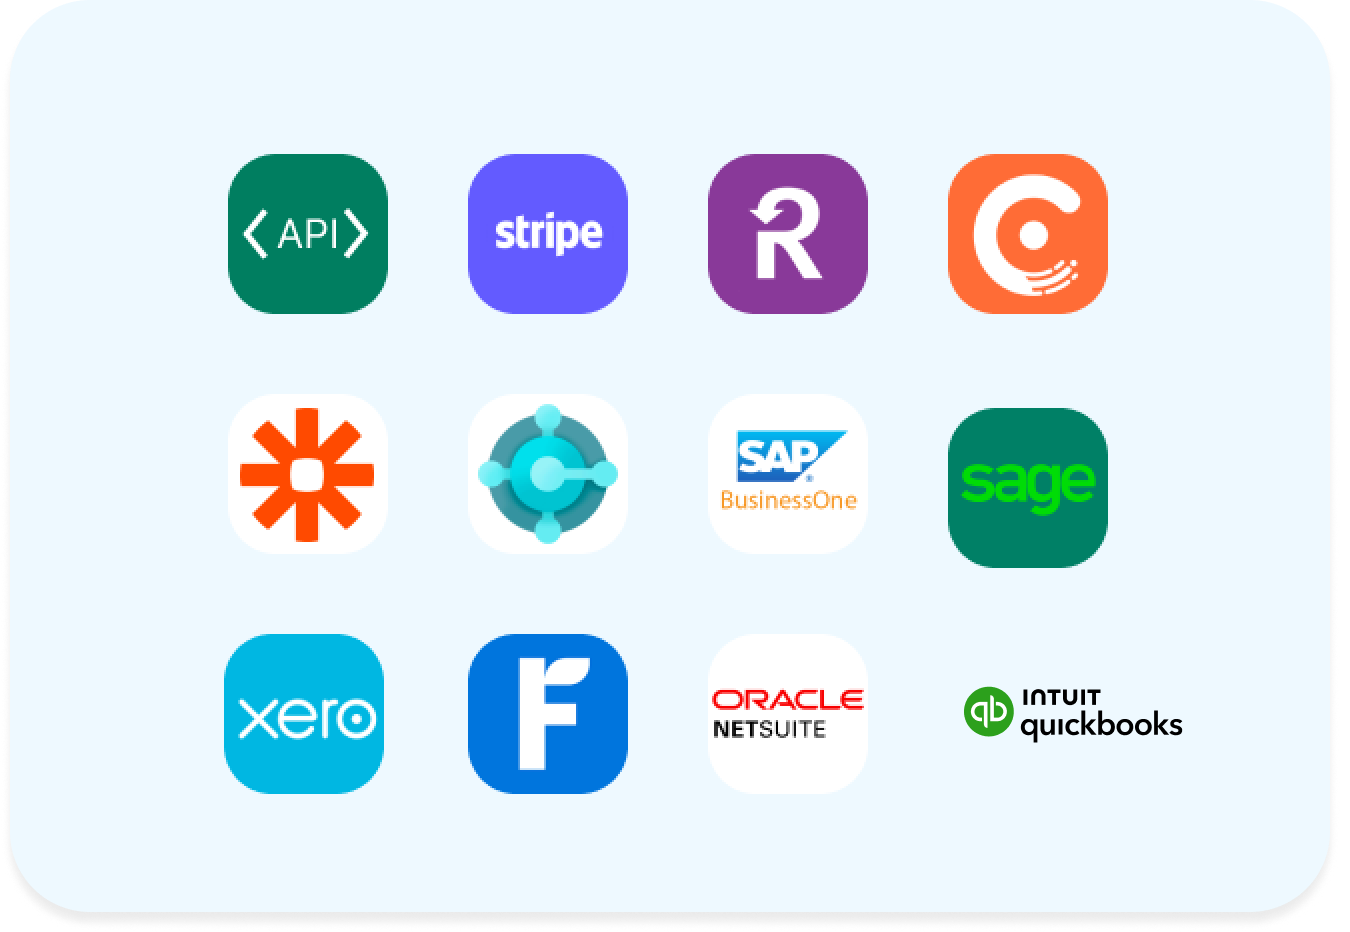
- Submit your claim: Upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- Local collection begins: We assign your case to the best-matching partner on your Maine panel: Debt Recovery Resources, Direct Recovery Associates or Aaron Bryant Stewart & Cross, who opens the amicable phase with your debtor. If court action is required, typically in Maine District Court's Small Claims Division for claims up to $10,000, you approve a legal quote, with court costs stated separately, before anything proceeds.
- Get paid: Funds are remitted on recovery. If escalation is needed, only legal steps you have approved in a quote move forward.
Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size. On a $10,000 invoice to a US business, under 12 months overdue, the success fee is 15% ($1,500), shown before you submit. Minimum claim: $500. No fee if nothing is recovered.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Maine?
Debt collection in Maine starts with an amicable phase: your case is handled by your assigned partner, which issues demands and pursues payment or a written acknowledgment of the debt. Most undisputed commercial claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic; your partner assesses the legal route (typically the District Court's Small Claims Division for claims up to $10,000, or ordinary civil proceedings above), and you approve a legal quote before any court step.
- Submit in 2 minutes: upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- No Cure, No Pay: pre-legal collection is success-based, with no setup fees or subscriptions.
- You stay in control: legal escalation only happens after you approve a legal quote.
- Get paid: recovered funds are remitted to you; fees are deducted on success only.
The four steps from unpaid invoice to recovered cash
- Amicable collection: demands and negotiation handled by your Maine panel partner. Most undisputed claims resolve here, without going to court.
- Enforceable title: if the debtor does not pay, your partner assesses the legal route, and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a judgment, creditors use a disclosure hearing and court-ordered installment payments rather than continuous wage garnishment, plus writs of execution and the trustee process against bank accounts.
- Insolvency: if the debtor turns out to be insolvent, recovery depends on the local insolvency proceedings and is often uncertain. Any step in those proceedings is quoted separately and only starts if you accept.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Maine - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in Maine - the complete 2026 guide
For in-house counsel, finance teams and out-of-state creditors, this Maine guide covers 2026 debt recovery end-to-end - costs, timelines, limitation and interest, court routes, and post-judgment enforcement - plus step-by-step tools and compact tables to act correctly, fast.
What we will cover:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).

Contributing local experts:
Last updated:

Debt collection in Maine - quick answers
| Question | Answer |
|---|---|
| Main route | Demand letter → amicable collection → Maine District Court Small Claims Division (claims up to $10,000) or ordinary civil action → post-judgment enforcement |
| Statute of limitations | 6 years for most contract and invoice debt (14 M.R.S. §752); 20 years for notes signed before an attesting witness, sealed contracts, or bank-issued instruments (14 M.R.S. §751) |
| Late-payment interest | 6% per year absent a written agreement (9-B M.R.S. §432(1)); judgment interest tracks the 1-year US Treasury bill rate plus a statutory margin |
| Small claims | Maine District Court Small Claims Division hears claims up to $10,000 (14 M.R.S. §7482); filing fee $70 |
| Wage garnishment | No continuous wage garnishment for ordinary judgments; Maine instead uses a disclosure hearing and court-ordered installment payments (14 M.R.S. §§3125, 3126-A) |
| Court & enforcement fees | State fees apply only if the case escalates to legal |
| Our fee | Success fee only - No Cure, No Pay |
How much does debt collection cost in Maine?
With Debitura you pay a success fee only on amounts actually recovered, with no upfront or monthly costs; the exact rate depends on your claim, see our pricing. Court fees apply only if the case escalates to legal: the Small Claims Division filing fee is $70, including a $15 mediation fee (Admin. Order JB-05-26). These state fees are advanced by the creditor and can generally be recovered where the court allows costs to the prevailing party.
How long does debt collection take in Maine?
Most undisputed commercial claims are resolved in the amicable phase without court involvement. If escalation is needed, the Small Claims Division offers a simplified, speedy and informal process with mediation typically offered before a hearing, while contested cases in ordinary civil proceedings take substantially longer. Enforcement timing depends on the debtor's disclosed assets and income, since Maine does not use continuous wage garnishment for ordinary debts.
What are the limitation and interest rules in Maine?
The statute of limitations on most contract, invoice and open-account debt is 6 years from accrual (14 M.R.S. §752); notes signed before an attesting witness, sealed contracts, and bank-issued instruments carry a 20-year period (14 M.R.S. §751). For consumer collection, a debt collector may not sue more than 6 years after the consumer's last activity on the debt, and payment or acknowledgment after the period expires does not revive it (32 M.R.S. §11013(8)). Absent a written agreement, statutory interest is 6% per year (9-B M.R.S. §432(1)); judgment interest in non-contract actions tracks the 1-year US Treasury bill rate plus 3 percentage points before judgment and plus 6 percentage points after judgment (14 M.R.S. §§1602-B(3), 1602-C(1)(B)). Contracts for the sale of goods may instead be subject to a shorter 4-year period under the Uniform Commercial Code, cross-referenced in the general limitations statute rather than separately codified (11 M.R.S. §2-725, via 14 M.R.S. §751).
What documents do I need to collect a debt in Maine?
Assemble the contract or purchase order, the invoice(s), delivery or proof-of-service records, an account statement, your demand letters and reminders, and any written acknowledgment or payment agreement. If you are represented, add a power of attorney.
Which route should my claim take?
Claims up to $10,000 belong in the Small Claims Division, where a corporation or other legal entity can appear through an employee or principal without an attorney. Larger or more complex claims go to ordinary civil proceedings in Maine's District or Superior Court, where a corporation must appear by counsel. With Debitura, escalation only happens after you approve a legal quote.
Who does what in Maine debt collection?
Debt collection agencies in Maine
Maine licenses debt collectors under the Maine Fair Debt Collection Practices Act: no person may conduct the business of a debt collector in the state without a license issued by the Superintendent of Consumer Credit Protection (32 M.R.S. §11031(1)), renewed every two years, and licensees must maintain a surety bond in an amount set by the Superintendent (32 M.R.S. §11032). This licensing and bonding regime applies to consumer debt collection, defined as obligations for personal, family or household purposes (32 M.R.S. §11002(3), (5)); it does not reach purely commercial or business-to-business claims, which fall outside the Act's scope and are governed by the contract and Maine's general civil law instead. Debitura collects both consumer (B2C) and commercial (B2B) claims in Maine: for B2C cases, your assigned partner operates within this licensed framework; for B2B cases, collection proceeds under the ordinary contract and civil-procedure rules described throughout this guide. Any collector's license can be verified through the Bureau of Consumer Credit Protection's public Search For A Licensee tool. On the assigned Maine panel, Debt Recovery Resources is registered with the Texas Secretary of State under Reg. #0802087763, and Direct Recovery Associates is licensed by the California DFPI under Lic. #10186-99.
Maine courts and enforcement officers
The District Court's Small Claims Division hears claims up to $10,000 (14 M.R.S. §7482); larger or contested claims go to ordinary civil proceedings in District or Superior Court. After judgment, creditors use a disclosure hearing (14 M.R.S. §3125) and installment payment order (14 M.R.S. §3126-A) to reach a debtor's income and assets, and can record execution liens through the registry of deeds, the Secretary of State, or motor-vehicle title records (14 M.R.S. §4651-A).
Debt-collection attorneys in Maine
Attorneys handle litigation above the Small Claims limit and contested or disputed claims. In the Small Claims Division, a corporation or other legal entity may be represented by an employee or other principal, so no attorney is required for claims within the $10,000 limit; in ordinary civil proceedings, a corporation must appear by counsel.
Regulators
The Bureau of Consumer Credit Protection, within Maine's Department of Professional and Financial Regulation, licenses and supervises debt collectors and enforces the Maine Fair Debt Collection Practices Act; the CFPB and FTC oversee consumer debt collection at the federal level.
Which laws and courts apply to debt collection in Maine?
Key legislation in Maine
Debt collection in Maine is governed by the Maine Fair Debt Collection Practices Act (32 M.R.S. ch. 109-A), which applies alongside the federal Fair Debt Collection Practices Act. Both regulate consumer debt, defined as obligations for personal, family or household purposes (32 M.R.S. §11002(3), (5)); purely business-to-business debt is governed by the contract and Maine's general civil law. Out-of-state debt collectors are covered too: conducting business in Maine includes collecting from a Maine consumer wherever the collector is located (32 M.R.S. §11002(2)).
Recent changes: PL 2023, c. 663 added medical-debt protections, including a bar on interest or fees on known medical debt and litigation limits for lower-income households (32 M.R.S. §11013(3)(O)-(Q)); PL 2025, c. 201, effective September 24, 2025, bars reporting a consumer's medical debt to a consumer reporting agency; and a revised Bureau Rule 300, Debt Collector Operational Requirements, took effect in December 2025.
Civil court system in Maine
The District Court's Small Claims Division hears claims up to $10,000 (14 M.R.S. §7482) in a simplified, speedy and informal process. Larger and more complex civil claims are heard in Maine's District Court or Superior Court, with corporations required to appear by counsel outside Small Claims.
Consumer protection
The Bureau of Consumer Credit Protection enforces the Maine Fair Debt Collection Practices Act. Suing on a debt after the applicable limitations period has expired is a prohibited practice for consumer collections, and payment or acknowledgment after the period expires does not revive it (32 M.R.S. §11013(7)-(8)).
Step 1 - How does amicable (pre-legal) debt collection work in Maine?
Amicable collection in Maine is handled by your assigned panel partner, which contacts the debtor with formal demands and pursues payment, a payment agreement, or a written acknowledgment of the debt. Most undisputed commercial claims resolve in this phase without court involvement. For consumer collection, note that a debt collector may not sue more than 6 years after the consumer's last activity on the debt, and once that period expires, a later payment or acknowledgment does not restart it (32 M.R.S. §11013(8)); commercial claims otherwise follow the general 6-year limitation period for contract and invoice debt (14 M.R.S. §752).
When to escalate to court in Maine
Escalation is never automatic. It becomes relevant when the debtor is unresponsive, disputes the claim without merit, or the claim is approaching its limitation deadline. Your partner assesses the legal route and you approve a legal quote before any court step.
Step 2 - How do you obtain an enforceable title in Maine?
Fast-track option: Small Claims Division
Small claims in Maine are heard in the District Court's Small Claims Division.
| Maine Small Claims Division | |
|---|---|
| Claim limit | $10,000, excluding interest and costs (14 M.R.S. §7482), effective January 1, 2026 |
| Filing fee | $70, including a $15 mediation fee (Admin. Order JB-05-26) |
| Business claimants | A corporation or other legal entity can be represented by an employee or other principal; no attorney required |
| Attorney rules | Allowed, not required |
Ordinary proceedings in Maine
Claims above $10,000, or complex and contested cases, are heard in ordinary civil proceedings in Maine's District Court or Superior Court, where a corporation must appear by counsel. With Debitura, nothing is filed without your approval of a legal quote.
Determining the appropriate court
The route is determined mainly by the amount in controversy and the complexity of the dispute; both the District Court and Superior Court hear general civil actions in Maine.
Step 3 - How does debt enforcement work in Maine?
Ways to enforce a claim in Maine
Maine does not use continuous wage garnishment for ordinary money judgments. Instead, the creditor can subpoena the debtor to a disclosure hearing to testify under oath about income and assets (14 M.R.S. §3125), after which the court can issue an installment payment order (14 M.R.S. §3126-A). The amount subject to an installment order is capped at the least of 25% of disposable earnings plus exempt income, the amount exceeding 40 times the higher of the federal or state minimum wage, or total disposable earnings, and no order can issue if the debtor's income is entirely exempt. Creditors can also reach a debtor's funds or property held by a third party, such as a bank, through the trustee process (14 M.R.S. ch. 502), and a collector may not falsely threaten garnishment or seizure that is not actually lawful or intended (32 M.R.S. §11013(2)(D)).
How to collect a judgment in Maine
A Maine judgment is presumed paid and satisfied 20 years after the underlying obligation accrued (14 M.R.S. §864). Filing a writ of execution creates a lien on the debtor's real estate, personal property or motor vehicles, recorded through the registry of deeds, the Secretary of State, or title records, within 3 years of issuance (14 M.R.S. §4651-A(1)-(3)); liens created on or after September 1, 2020 run 10 years and can be renewed once for another 10 years, while older liens run 20 years, renewable once (14 M.R.S. §4651-A(9), (9-A)).
Step 4 - How do insolvency procedures work in Maine?
Business insolvency is governed by the federal Bankruptcy Code, with Chapter 7 liquidation and Chapter 11 reorganization as the main routes. Once a bankruptcy is filed, the automatic stay halts individual collection actions, and recovery runs through the insolvency estate: creditors file a proof of claim in the case and distributions follow the statutory priority order. Any step in insolvency proceedings is quoted separately and only starts if you accept.
Fees, interest and who pays what in Maine
Debitura's pre-legal collection in Maine is success-based - No Cure, No Pay, with no setup fees or subscriptions.
Court and enforcement fees - only if the case escalates to legal
State fees apply only if the case escalates to legal. The Small Claims Division filing fee is $70, including a $15 mediation fee, with optional fees for service of the claim ($15 per party) and disclosure proceedings ($30 per defendant to enter, $20 per party to serve) (Admin. Order JB-05-26). These fees are advanced by the creditor and can generally be recovered where the court allows costs to the prevailing party.
Interest and late fees the debtor owes - from the amicable phase
Absent a written agreement, Maine's statutory interest rate is 6% per year (9-B M.R.S. §432(1)). Pre-judgment interest on a contract or note with its own interest provision runs at that contract rate; in other civil actions it runs at the 1-year US Treasury bill rate plus 3 percentage points, which put the rate at roughly 7% as of July 2026 (1-year Treasury rate of approximately 4.08%, per the US Department of the Treasury's Daily Treasury Par Yield Curve, plus the statutory 3-point margin) (14 M.R.S. §1602-B). Post-judgment interest in non-contract actions runs at the same Treasury rate plus 6 percentage points, or roughly 10% on the same basis (14 M.R.S. §1602-C). For construction contracts specifically, Maine's Construction Contracts Act requires payment within 20 days of the billing period or invoice, with interest at the §1602-C rate from the 21st day and a 1%-per-month penalty on wrongfully withheld sums (10 M.R.S. §§1113, 1118).
Collecting a Maine debt from out of state or abroad
Creditors outside Maine can enforce sister-state judgments in Maine under the Uniform Enforcement of Foreign Judgments Act (14 M.R.S. ch. 740): filing an authenticated foreign judgment with the court clerk gives it the same effect as a Maine judgment (14 M.R.S. §8003), for a $175 filing fee (Admin. Order JB-05-26). Out-of-state and international creditors work through the same Maine panel: your case is routed to the licensed partner best matched to your claim, with the same No Cure, No Pay terms, and cross-border cases draw on Debitura's network across 180 countries.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.

Need debt recovery beyond Maine?
Explore our North America debt-collection hub for country-by-country playbooks.
For coast-to-coast coverage in the US, see the U.S. debt-collection overview.
Neighboring states: New Hampshire · Massachusetts