Debt Collection Agency in Arizona: No Cure, No Pay
Your Arizona claim is handled by a licensed local collection partner, matched to your case and benchmarked on performance. All actions follow Arizona law, and you track everything in one dashboard. Prefer to learn first? Read our Arizona debt collection guide.


Questions about your case?
Write to us, we reply by email.
Our local debt collection partners
Debitura is a platform, not a single agency: your case is routed to the licensed collection partner best matched to your claim type, debtor profile and industry. After that, we follow their results on our platform: how much they collect, how fast they respond and how clients rate them.
- Verified specialists
- Fee shown before you submit
- Fair, pre-negotiated rates
Direct Recovery Associates, Inc. is a premier debt recovery agency in Agoura Hills offering effective Debt Collection services in the United States, founded in 1992, with a global reach and performance-based billing, ensuring client satisfaction.
See full partner profile


Aaron Bryant Stewart & Cross is a premier debt recovery agency in the United States offering effective No Cure No Pay Debt Collection services, established in 2006 and serving North America and select international markets, as a Debitura partner in the U.S., providing collections based on Debitura's No Cure, No Pay standard terms and pricing, and is a member of ACA International.
See full partner profile
Debt Recovery Resources is a premier debt recovery agency in the United States offering effective debt collection services, a member of the CLLA, partnering with Debitura for No Cure No Pay solutions.
See full partner profileWhy choose Debitura for debt collection in Arizona?
Debt collection in Arizona, matched to a local partner
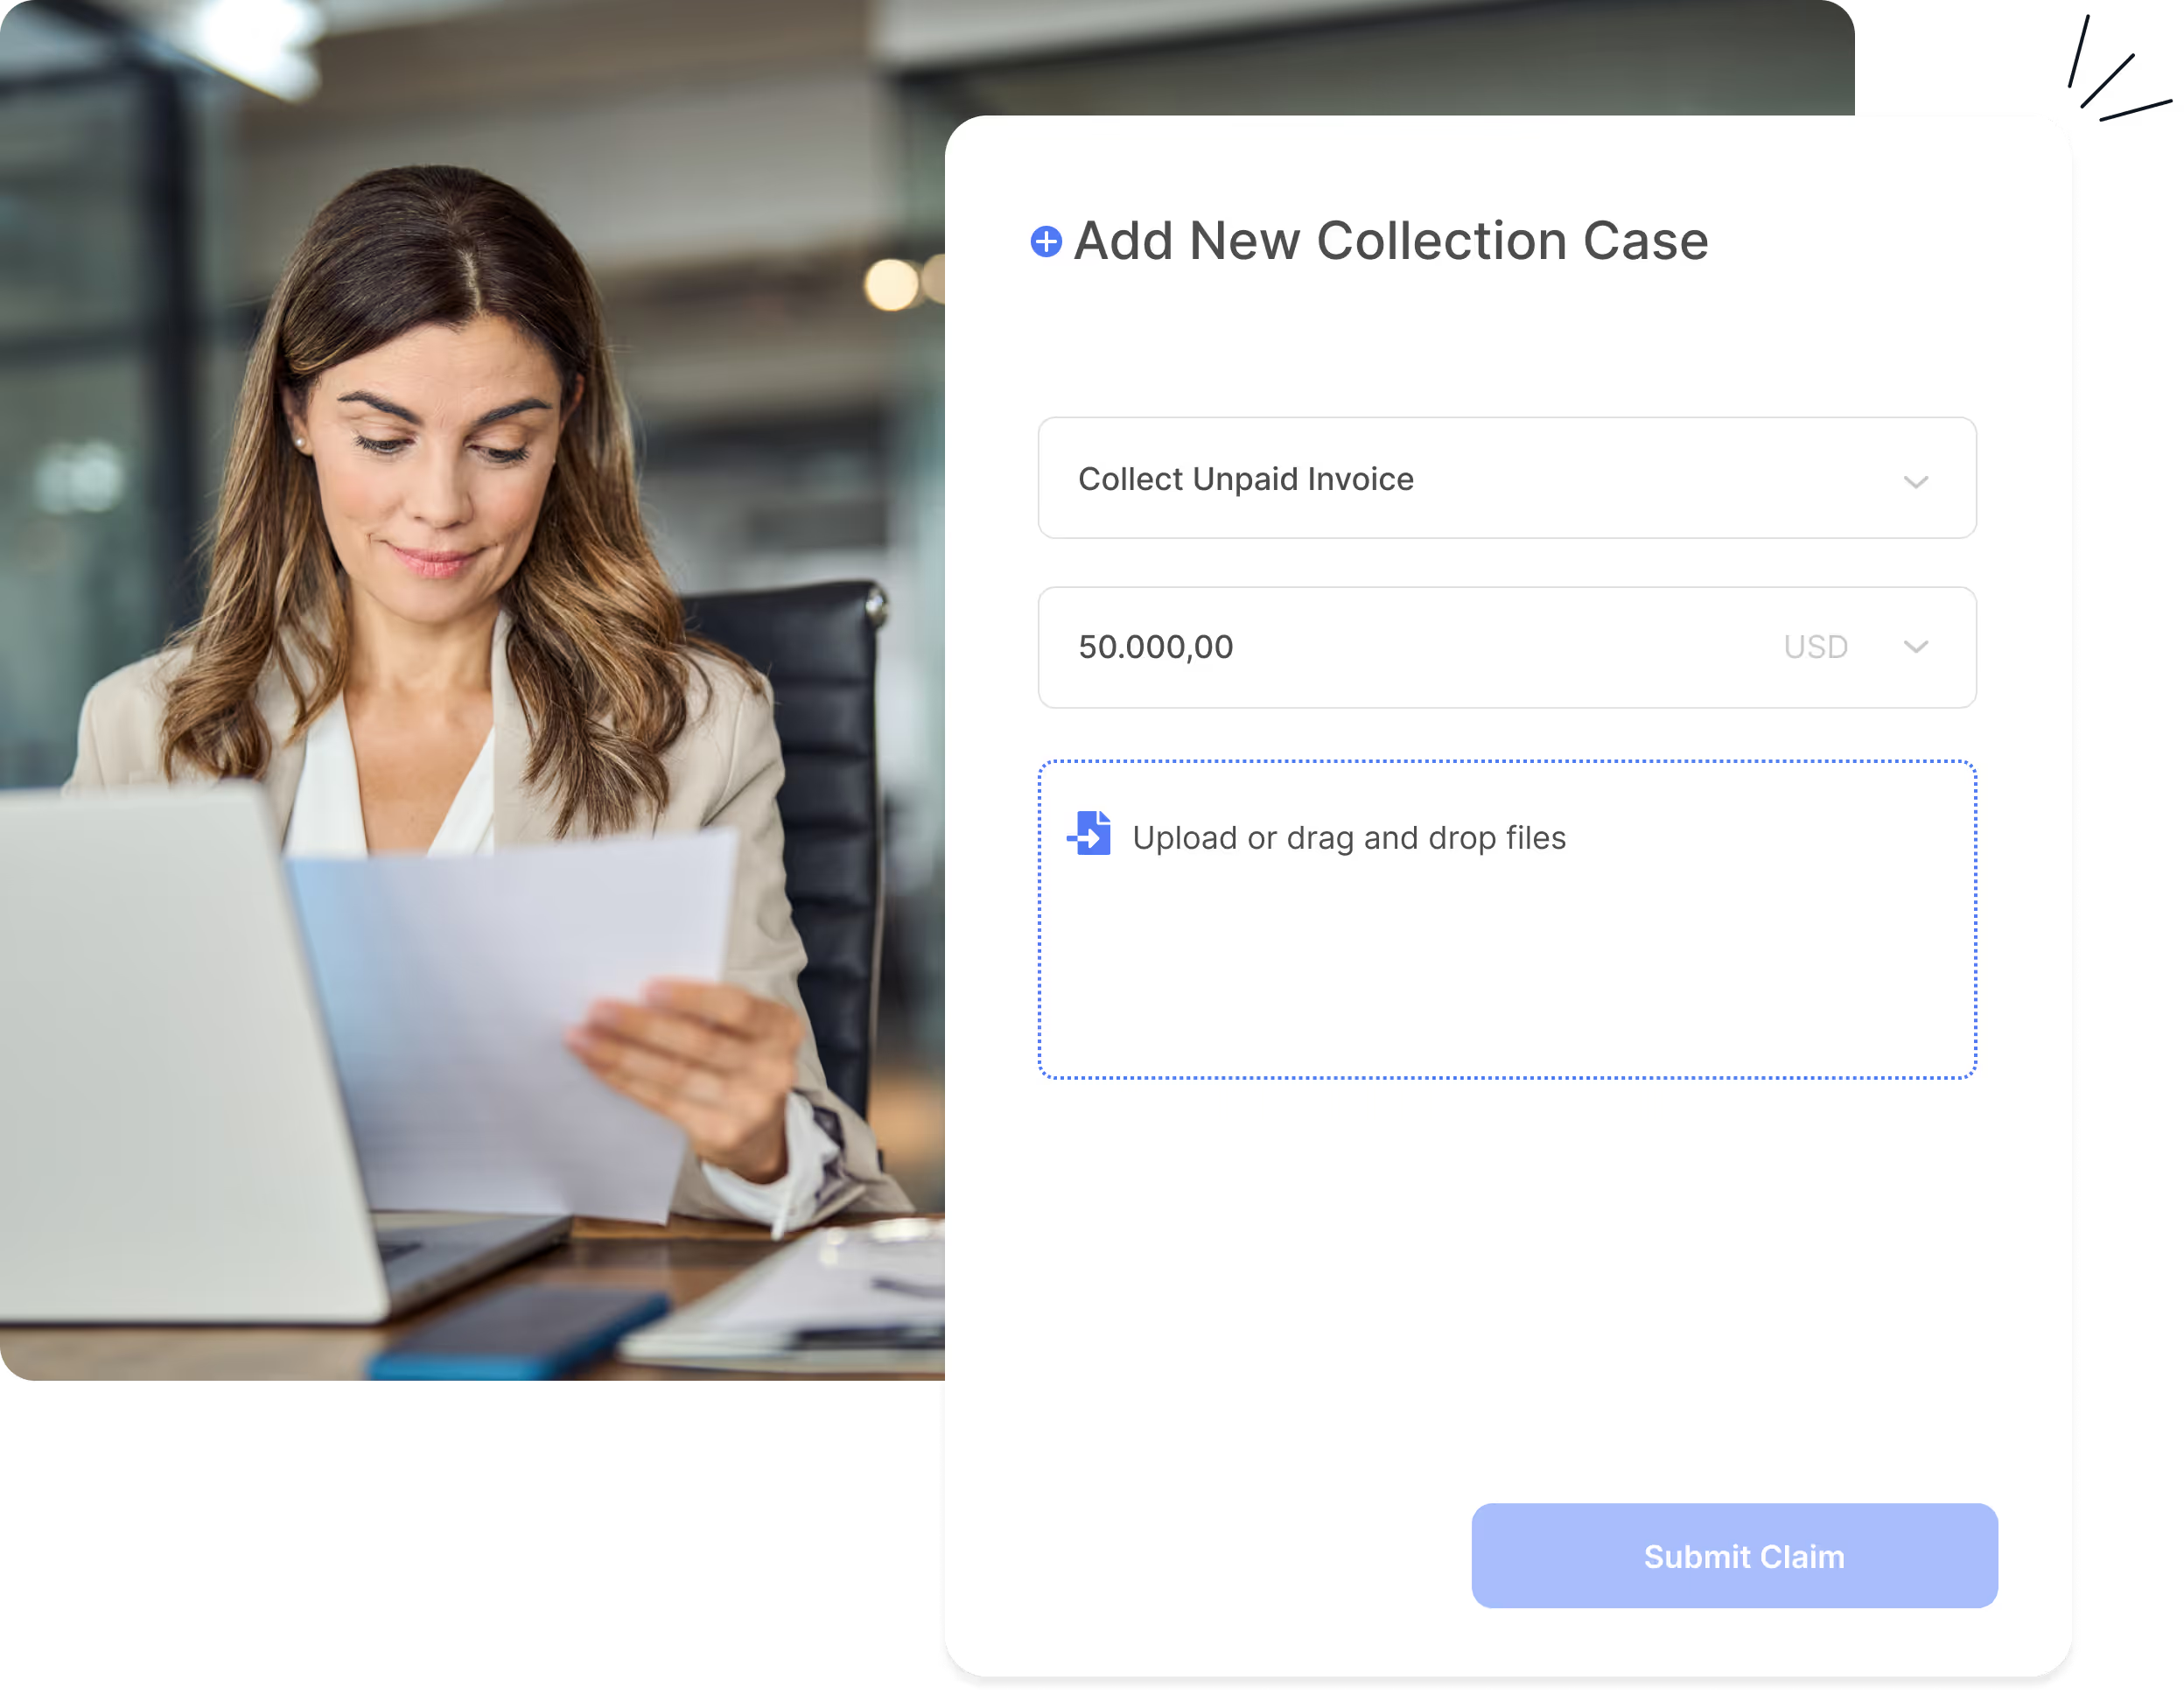
Debitura recovers unpaid invoices from debtors in Arizona through our platform: submit your claim, and we assign it to the best-matching licensed partner working on a No Cure, No Pay basis while you track progress in real time. Your Arizona panel includes Debt Recovery Resources, a Southlake, Texas-based agency registered with the Texas Secretary of State (Reg. #0802087763) and a member of CLLA and ACA International, alongside Direct Recovery Associates, licensed by the California Department of Financial Protection and Innovation and collecting commercial debt since 1992.
- No Cure, No Pay: Pay only when we recover your money.
- Quick setup: Submit invoices in a few clicks.
- Real-time tracking: Monitor progress live in one portal.
- Local compliance: Collection follows the Arizona Collection Agency Act (A.R.S. Title 32, Ch. 9) and the FDCPA.
Start recovering your Arizona claims in 2 minutes
- Submit your claim: Upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- Local collection begins: We assign your case to the best-matching partner on your Arizona panel: Debt Recovery Resources, Direct Recovery Associates or Aaron Bryant Stewart & Cross, who opens the amicable phase with your debtor. If court action is required, typically in the Small Claims Division of the Justice Court for claims up to $5,000, you approve a legal quote, with court costs stated separately, before anything proceeds.
- Get paid: Funds are remitted on recovery. If escalation is needed, only legal steps you have approved in a quote move forward.
Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size. On a $10,000 invoice to a US business, under 12 months overdue, the success fee is 15% ($1,500), shown before you submit. Minimum claim: $500. No fee if nothing is recovered.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in Arizona?
Debt collection in Arizona starts with an amicable phase: your case is handled by your assigned partner, which issues demands and pursues payment or a written acknowledgment of the debt. Most undisputed commercial claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic; your partner assesses the legal route (typically the Small Claims Division for claims up to $5,000, or the regular Justice Court or Superior Court above that), and you approve a legal quote before any court step.
- Submit in 2 minutes: upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- No Cure, No Pay: pre-legal collection is success-based, with no setup fees or subscriptions.
- You stay in control: legal escalation only happens after you approve a legal quote.
- Get paid: recovered funds are remitted to you; fees are deducted on success only.
The four steps from unpaid invoice to recovered cash
- Amicable collection: demands and negotiation handled by your Arizona panel partner. Most undisputed claims resolve here, without going to court.
- Enforceable title: if the debtor does not pay, your partner assesses the legal route, and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a judgment, creditors can use a writ of garnishment against wages, capped at 10% of disposable earnings under Proposition 209, and bank levies subject to a $5,000 per-account exemption.
- Insolvency: if the debtor cannot pay, your proof of claim is filed in the insolvency process and distributions are monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for Arizona - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in Arizona - the complete 2026 guide
For in-house counsel, finance teams and out-of-state creditors, this Arizona guide covers 2026 debt recovery end-to-end - costs, timelines, limitation and interest, court routes, and post-judgment enforcement - plus step-by-step tools and compact tables to act correctly, fast.
What we will cover:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).
Contributing local experts:
Last updated:

Debt collection in Arizona - quick answers
| Question | Answer |
|---|---|
| Main route | Demand letter → amicable collection → Small Claims Division of the Justice Court (claims up to $5,000) or regular Justice Court/Superior Court → post-judgment enforcement |
| Statute of limitations | 6 years for written contracts (A.R.S. §12-548); 3 years for oral agreements and open accounts (§12-543) |
| Late-payment interest | 10% per year where no rate is agreed (A.R.S. §44-1201(A)); no usury ceiling for a rate set in a written agreement |
| Small claims | Small Claims Division of the Justice Court hears claims up to $5,000 (A.R.S. §22-503); attorneys only by consent of all parties |
| Wage garnishment | Capped at 10% of disposable earnings (5% on a hardship showing) under Proposition 209 (A.R.S. §12-1598 et seq.) |
| Court & enforcement fees | State fees apply only if the case escalates to legal |
| Our fee | Success fee only - No Cure, No Pay |
How much does debt collection cost in Arizona?
With Debitura you pay a success fee only on amounts actually recovered, with no upfront or monthly costs; the exact rate depends on your claim, see our pricing. Court fees apply only if the case escalates to legal: the Small Claims Division filing fee is about $39 to $74 depending on the precinct, and enforcement costs vary by county. These state fees are advanced by the creditor and can generally be recovered as court costs if you prevail.
How long does debt collection take in Arizona?
Most undisputed commercial claims are resolved in the amicable phase without court involvement. If escalation is needed, the Small Claims Division is the fastest judicial route for claims up to $5,000 (though its judgments cannot be appealed), while contested Justice Court or Superior Court cases take substantially longer. Enforcement timing depends on locating non-exempt wages, bank funds or property.
What are the limitation and interest rules in Arizona?
The statute of limitations is 6 years for written contracts (A.R.S. §12-548) and 3 years for oral agreements and open accounts (§12-543). A written acknowledgment or new promise, signed by the debtor, revives a time-barred claim (§12-508). Without an agreed rate, interest runs at 10% per year (A.R.S. §44-1201(A)); Arizona sets no usury ceiling for a rate fixed in a written agreement, so contract rates above 10% are enforceable if in writing. Post-judgment interest on a judgment based on a written agreement carries the contract rate (§44-1201(D)); otherwise it is the lesser of 10% per year or the prime rate plus 1% (§44-1201(B)).
What documents do I need to collect a debt in Arizona?
Assemble the contract or purchase order, the invoice(s), delivery or proof-of-service records, an account statement, your demand letters and reminders, and any written acknowledgment or payment agreement. If you are represented, add a power of attorney.
Which route should my claim take?
Claims up to $5,000 belong in the Small Claims Division of the Justice Court, where a business may appear through an officer, member or employee, but judgments there cannot be appealed. Larger or disputed claims go to the regular Justice Court civil docket or Superior Court. With Debitura, escalation only happens after you approve a legal quote.
Who does what in Arizona debt collection?
Debt collection agencies in Arizona
Arizona licenses collection agencies under the Collection Agency Act (A.R.S. Title 32, Ch. 9): a license from the Department of Insurance and Financial Institutions (DIFI), processed through NMLS, is required before collecting, including for out-of-state agencies pursuing Arizona debtors and for commercial as well as consumer accounts (A.R.S. §32-1021). Licensure requires a surety bond scaled to the agency's gross Arizona collection income, with a statutory minimum of $10,000 rising to $25,000-$35,000 for higher-volume agencies. Licenses can be verified through NMLS Consumer Access and DIFI's collection-agency pages. Debt Recovery Resources is separately registered with the Texas Secretary of State (Reg. #0802087763) and Direct Recovery Associates is licensed by the California Department of Financial Protection and Innovation (Reg. #10186-99).
Arizona courts and enforcement officers
The Small Claims Division of the Justice Court hears claims up to $5,000; the regular Justice Court civil docket and Superior Court hear larger and more complex cases. After judgment, constables and sheriffs execute writs of execution and writs of garnishment, and the county recorder records judgments to create real-property liens.
Debt-collection attorneys in Arizona
Attorneys are only permitted in the Small Claims Division if all parties consent in writing (A.R.S. §22-512); above that limit, in the regular Justice Court docket or Superior Court, attorneys are routinely used.
Regulators
The Department of Insurance and Financial Institutions licenses and regulates collection agencies; the Arizona Attorney General's Consumer Protection division handles consumer complaints. The CFPB and FTC oversee consumer debt collection at the federal level.
Which laws and courts apply to debt collection in Arizona?
Key legislation in Arizona
Arizona has no state consumer debt-collection statute with a private right of action comparable to the FDCPA; consumer conduct is governed by the federal Fair Debt Collection Practices Act, while the state's own Collection Agency Act (A.R.S. §§32-1001 to 32-1057) is a licensing and regulatory regime that reaches the collection of indebtedness generally, including commercial and B2B accounts. Proposition 209, the Predatory Debt Collection Protection Act approved by voters in November 2022, capped medical-debt interest at 3%, cut wage garnishment to 10% of disposable earnings (5% on a hardship showing), raised the homestead exemption to $400,000 and the household-goods exemption to $15,000, and added a $5,000 bank-account garnishment exemption; the measure remains in effect.
Recent change: SB 1022 (2025) raised the Small Claims Division's jurisdictional limit from $3,500 to $5,000, the first increase in over a decade.
Civil court system in Arizona
The Small Claims Division of the Justice Court hears claims up to $5,000 without a right of appeal; the regular Justice Court civil docket and Superior Court hear larger and more complex cases. Suits are generally filed in the precinct or county connected to the debtor or the transaction.
Consumer protection
The Arizona Attorney General's Consumer Protection division handles consumer complaints about collection conduct; DIFI can act against unlicensed or non-compliant collection agencies.
Step 1 - How does amicable (pre-legal) debt collection work in Arizona?
Amicable collection in Arizona is handled by your assigned panel partner, which contacts the debtor with formal demands and pursues payment, a payment agreement, or a written acknowledgment of the debt. Most undisputed commercial claims resolve in this phase without court involvement. A written acknowledgment or new promise signed by the debtor revives a time-barred claim (A.R.S. §12-508).
When to escalate to court in Arizona
Escalation is never automatic. It becomes relevant when the debtor is unresponsive, disputes the claim without merit, or the claim is approaching the 6-year (written) or 3-year (oral/open account) limitation deadline. Your partner assesses the legal route and you approve a legal quote before any court step.
Step 2 - How do you obtain an enforceable title in Arizona?
Fast-track option: the Small Claims Division
Small claims in Arizona are heard in the Small Claims Division of the Justice Court under A.R.S. §22-503.
| Arizona Small Claims Division | |
|---|---|
| Claim limit | $5,000, exclusive of interest and costs |
| Filing fee | About $39 to $74, varies by precinct |
| Business claimants | May appear through an officer, member or employee |
| Attorney rules | Allowed only if all parties consent in writing (A.R.S. §22-512); no appeal from the judgment |
Ordinary proceedings in Arizona
Larger or disputed claims are heard on the regular Justice Court civil docket or in Superior Court for the largest and most complex cases. With Debitura, nothing is filed without your approval of a legal quote.
Determining the appropriate court
The route is determined by the amount in controversy, whether an appeal right matters, and the complexity of the dispute; suits are generally filed in the precinct or county connected to the debtor or the transaction.
Step 3 - How does debt enforcement work in Arizona?
Ways to enforce a claim in Arizona
With a judgment, creditors can pursue a writ of garnishment against wages, capped at 10% of disposable earnings (as low as 5% on a showing of extreme hardship) under Proposition 209 (A.R.S. §12-1598 et seq.), and a writ of garnishment against bank accounts, which carries a $5,000 per-account exemption. A writ of execution against non-exempt property is also available, though Proposition 209 raised the homestead exemption to $400,000 and the household-goods exemption to $15,000.
How to collect a judgment in Arizona
An Arizona judgment is enforceable for 10 years and may be renewed for successive 10-year periods, either by an action on the judgment (A.R.S. §12-1611) or by an affidavit of renewal filed within 90 days before expiration (§12-1612). Recording a certified copy of the judgment with the county recorder creates a lien on the debtor's real property in that county, valid 10 years and renewable (§33-961, §12-1613).
Step 4 - How do insolvency procedures work in Arizona?
Business insolvency is governed by the federal Bankruptcy Code, with Chapter 7 liquidation and Chapter 11 reorganization as the main routes. Once a bankruptcy is filed, the automatic stay halts individual collection actions, and recovery runs through the insolvency estate: your proof of claim is filed in the process and distributions follow the statutory priority order. Your Arizona panel partner files the claim and monitors distributions on your behalf, so nothing is lost for lack of follow-up.
Fees, interest and who pays what in Arizona
Debitura's pre-legal collection in Arizona is success-based - No Cure, No Pay, with no setup fees or subscriptions.
Court and enforcement fees - only if the case escalates to legal
State fees apply only if the case escalates to legal. The Small Claims Division filing fee is about $39 to $74 depending on the precinct, and enforcement costs vary by county. These fees are advanced by the creditor and can generally be recovered as court costs if you prevail.
Interest and late fees the debtor owes - from the amicable phase
Without an agreed rate, Arizona allows 10% per year (A.R.S. §44-1201(A)); there is no usury ceiling for a rate fixed in a written agreement, so higher contract rates are enforceable. Arizona sets no general statutory cap on commercial late-payment fees; the contract governs.
Collecting an Arizona debt from out of state or abroad
Creditors outside Arizona can enforce sister-state judgments in Arizona under the Uniform Enforcement of Foreign Judgments Act (A.R.S. §§12-1701 to 12-1708), and new suits are filed in the precinct or county connected to the debtor or the transaction. Out-of-state and international creditors work through the same Arizona panel: your case is routed to the licensed partner best matched to your claim, with the same No Cure, No Pay terms, and cross-border cases draw on Debitura's network across 180 countries.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.

Need debt recovery beyond Arizona?
Explore our North America debt-collection hub for country-by-country playbooks.
For coast-to-coast coverage in the US, see the U.S. debt-collection overview.
Neighboring states: California · New Mexico