

Kostenlos loslegen
Debt Collection Agency in Argentina - No Win, No Fee
Ihr vertrauenswürdiges Inkassounternehmen in Argentinien. Reichen Sie Ihre Forderung für eine effiziente Beitreibung ein, ohne anfängliche Gebühren. Entdecken Sie die Inkassolandschaft Argentiniens mit unserem umfassenden Leitfaden.

100 % risikofrei: Sie zahlen nur bei Erfolg
Local debt collection by licensed agency / law firm
Founded 2000

Kostenlose Expertenberatung anfordern
Antwort von einem Spezialisten innerhalb von 24 Stunden.
Vielen Dank! Ihre Anfrage wurde empfangen!
Hoppla! Beim Absenden des Formulars ist etwas schiefgelaufen.
Why Choose Debitura for Debt Collection in Argentina
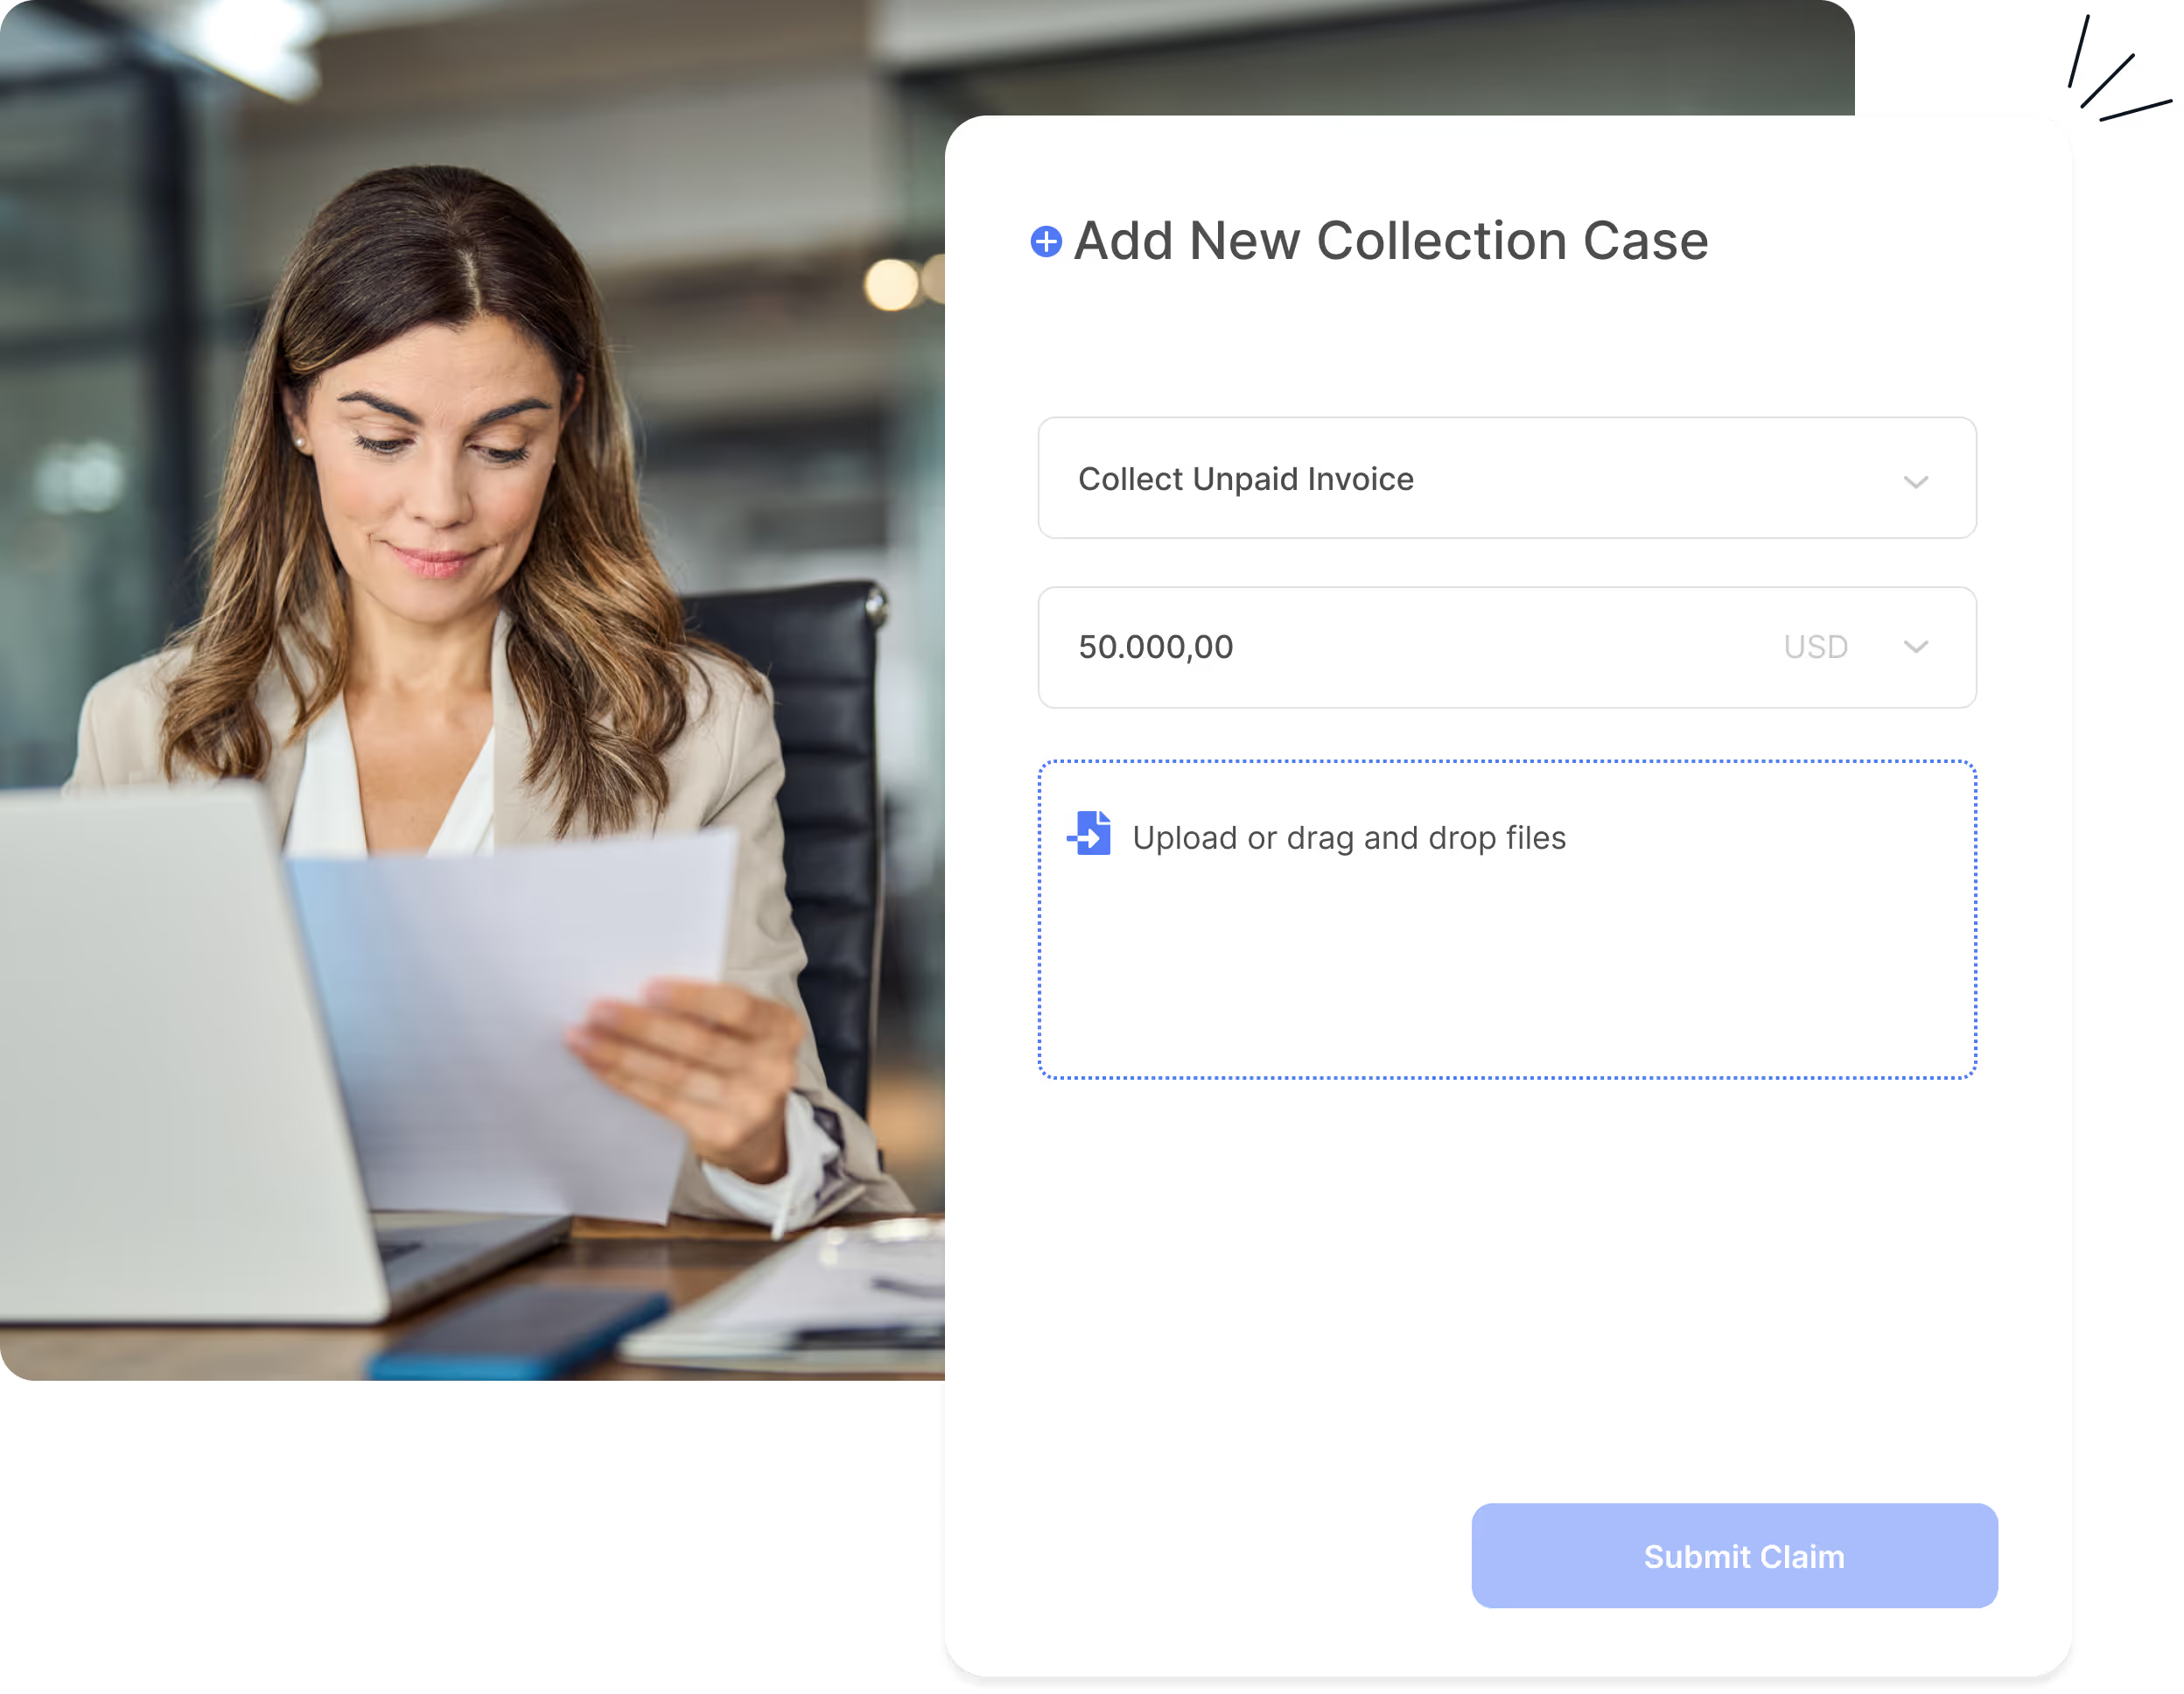
Fast, simple and risk-free debt collection in Argentina
Debitura recovers unpaid invoices from debtors in Argentina through our platform: submit your claim, and we assign it to a licensed partner working on a No Cure, No Pay basis while you track progress in real time. Your case is handled by EMS Debita Internacional, a debt collection agency established in 2000 and supervised by the Superintendencia de Bancos del Ecuador. Nothing escalates beyond the amicable phase without your approval.
- Risk-free: pay only when we recover your money.
- Quick setup: submit the invoice and debtor details in a few clicks.
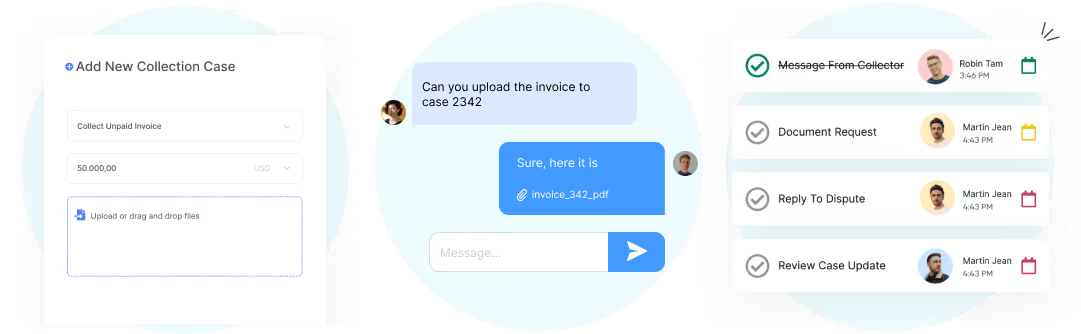
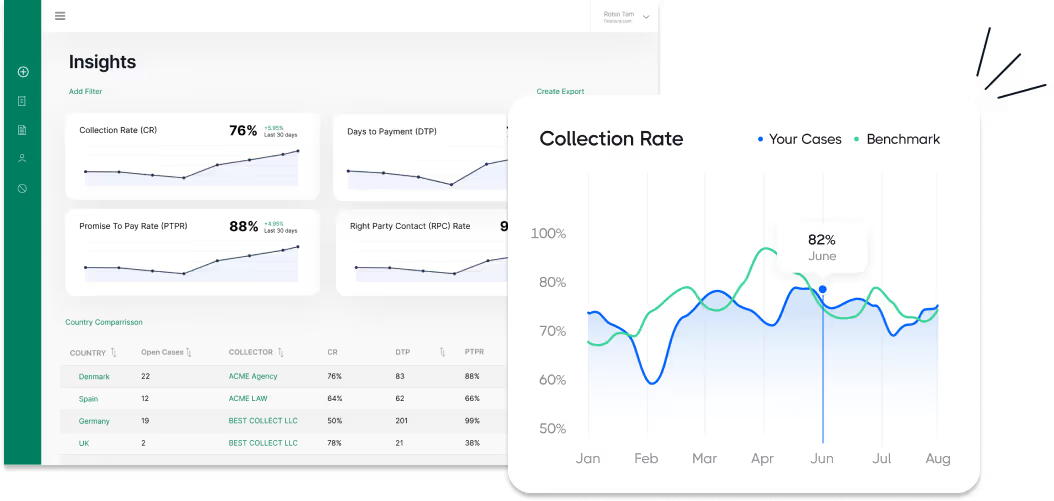
- Real-time tracking: follow every step in one dashboard, in English.
- Local expertise: a Spanish-speaking Latin America desk in Cañar, Ecuador, that works Argentine claims cross-border.
So einfach geht's
- Create your free Debitura account and submit your Argentine claim with the invoice and debtor details.
- EMS Debita Internacional takes the case and opens the amicable phase with a formal payment demand to your debtor.
- Track progress in your dashboard and pay only when funds are recovered.
Already using SAP, Oracle, Microsoft Dynamics or another ERP? Connect through our API or Zapier to submit claims automatically.

Transparente, erfolgsbasierte Preise
Mit Debitura zahlen Sie nur bei Erfolg. Das vorgerichtliche Inkasso erfolgt auf „Kein Erfolg, keine Gebühren“-Basis: eine Erfolgsprovision, die von den eingezogenen Beträgen abgezogen und lokal von Ihrem Partner in Rechnung gestellt wird. Die Gebühren hängen vom Land des Schuldners ab, nicht von Ihrem.
- Schuldner in Europa (EU, Island, Liechtenstein, Norwegen, Großbritannien und der Schweiz): Erfolgsprovisionen ab 6 % je nach Forderungshöhe.
- Schuldner im Rest der Welt: Erfolgsprovisionen ab 7,5 % je nach Forderungshöhe.
- Ältere Forderungen: Für Forderungen, die 12–24 Monate überfällig sind, sowie für Forderungen, die älter als 24 Monate sind, wird ein Aufschlag berechnet.
- Rechtliche Schritte sind optional: Sie genehmigen Festpreisangebote, bevor rechtliche Ausgaben anfallen.
Die vollständige Gebührenübersicht finden Sie auf der Preise-Seite oder erhalten Sie eine sofortige Schätzung, wenn Sie eine Forderung hochladen.
Wie funktioniert das Inkasso in Argentinien?
Debt collection in Argentina starts with an amicable phase handled by a licensed partner: reminders and a formal payment demand, aimed at full payment or a written instalment agreement. Most straightforward claims are resolved at this stage. If the debtor still does not pay, escalation to court is a separate, approved step - never automatic.
Wichtige Erkenntnisse
Die vier Schritte von der unbezahlten Rechnung zum eingezogenen Geld
- Step 1 - Amicable collection: reminders, a formal payment demand and negotiation, handled by a licensed partner. Most undisputed claims are resolved in this phase, without going to court.
- Schritt 2 - Vollstreckbarer Titel: Zahlt der Schuldner weiterhin nicht, prüft Ihr Partner den rechtlichen Weg, um einen vollstreckbaren Titel zu erhalten, und Sie genehmigen ein Festpreisangebot, bevor weitere Schritte eingeleitet werden.
- Schritt 3 - Zwangsvollstreckung: Mit einem vollstreckbaren Titel kann die zuständige Vollstreckungsbehörde Löhne, Bankguthaben und andere Vermögenswerte pfänden, bis die Forderung beglichen ist.
- Schritt 4 - Insolvenz: Sollte sich der Schuldner als insolvent erweisen, wird Ihre Forderungsanmeldung eingereicht und eventuelle Ausschüttungen in Ihrem Namen überwacht.
Jeder Schritt wird in Ihrem Dashboard verfolgt, und nichts eskaliert ohne Ihre Zustimmung. Die vollständigen rechtlichen Details für Argentinien – Zeitpläne, Kosten, Gerichte und Zwangsvollstreckung – finden Sie im folgenden Leitfaden.

Kostenlos starten
Keine Einrichtungsgebühr
Zugelassene Experten vor Ort
Kein Erfolg, keine Kosten
Inkasso in Argentinien - der vollständige Leitfaden 2026
This guide covers Debt Collection Argentina for creditors, in-house counsel and finance teams: the amicable phase, the routes to an enforceable title, enforcement, and insolvency, with the statutes and courts that apply. Argentina is a federation: 23 provinces plus Ciudad Autónoma de Buenos Aires (CABA) each run their own procedural code, so this guide uses the national/CABA framework as its reference point.
Auf dieser Seite:
Warum Sie dieser Anleitung vertrauen können
At Debitura, we uphold the highest standards of impartiality and precision to bring you comprehensive guides on international debt collection. Every guide is written from primary legal sources and reviewed by licensed local experts in the jurisdiction it covers.
Fragen oder Feedback? Senden Sie uns eine E-Mail an contact@debitura.com , wir aktualisieren diesen Leitfaden basierend auf Ihrem Input.
Debitura in Zahlen:
- 767 licensed partners - collection agencies and law firms in our network
- 180 countries covered - with cases handled in 174 of them
- 5,306 businesses registered with Debitura
- 33 days median time to first payment on European cases
Von Experten geleitet, lokal validiert
Verfasst von Lars Holdgaard, Gründer von Debitura (über 10 Jahre Erfahrung im globalen B2B-Forderungseinzug). Jede Seite wird von führenden lokalen Anwälten überprüft, um die rechtliche Genauigkeit und die Anwendbarkeit der praktischen Schritte zu gewährleisten.
Mitwirkende lokale Experten:
Letzte Aktualisierung:
September 16, 2026

Inkasso in Argentinien - schnelle Antworten
Wie lange habe ich in Argentinien Zeit, eine Forderung einzutreiben?
General civil and commercial claims prescribe in 5 years under the Código Civil y Comercial (the Civil and Commercial Code, CCyC), art. 2560. Credit-card debt runs on a separate, shorter clock: the Ley de Tarjetas de Crédito (the Credit Card Law, Ley 25.065), art. 47, gives 1 year to bring an executive action and 3 years to bring an ordinary action. Debt Collection Argentina claims should start well before these deadlines, since a lapsed claim is far harder to enforce, and the applicable period can also depend on the province where the claim is filed. As Argentina’s own Ministerio Público Fiscal (Public Prosecutor’s Office) has put it, courts should apply “el plazo más favorable al consumidor, que es el de 5 años previsto en el artículo 2560 del CCyCN” (the period most favourable to the consumer, the 5 years set out in article 2560 of the CCyC).
| Claim type | Verjährungsfrist | Source |
|---|---|---|
| General civil/commercial debt | 5 Jahre | CCyC art. 2560 |
| Credit-card debt, executive action | 1 year | Ley 25.065 art. 47 |
| Credit-card debt, ordinary action | 3 Jahre | Ley 25.065 art. 47 |
Does contacting the debtor restart the limitation clock?
Yes. A written, signed acknowledgement of the debt, or a part-payment, restarts the limitation clock under the CCyC's rules on prescription (Book Six, Title I). Creditors who secure a signed acknowledgement effectively reset the deadline above, which is often a practical first goal during the amicable phase, before considering court action.
What interest can I charge on an unpaid debt in Argentina?
Absent a contractual rate, statutory interest under CCyC art. 768 defaults to a rate set by the Banco Central de la República Argentina (the Central Bank of Argentina, BCRA). From January 2026, that reference is the BCRA's own Tasa de Intereses Moratorios (TIM), an average of the 30-day time-deposit passive rate and the signature/personal-loan active rate, bounded within CER±3%. Where a contract sets its own interest rate, that rate generally applies instead. The BCRA compiles the underlying rate series back to 3 June 1993, and formally adopted the TIM as this reference rate on 7 January 2026, publishing the resolution in the Boletín Oficial (Official Gazette) on 9 January 2026.
What is the first step in recovering a debt in Argentina?
Recovery starts with an amicable phase: a formal payment demand and negotiation aimed at a voluntary payment or a written instalment agreement, before any court filing. Most straightforward claims settle at this stage; see Step 1 below. Debtors who respond promptly at this stage typically avoid the added court costs and interest described later in this guide.
Do I need a court judgment before I can enforce a debt in Argentina?
Yes. Enforcement (embargo, asset freeze or auction) requires an enforceable title, either a court judgment or another legally recognised enforceable instrument, obtained through the juicio ejecutivo (executive process) or ordinary proceedings described in Step 2 below. No enforcement authority in Argentina can seize assets without one. Which route applies depends on the evidence held: a qualifying enforceable instrument supports the faster juicio ejecutivo, while claims without one proceed as an ordinary civil or commercial action instead.
What does it cost to collect a debt in Argentina?
Argentina's national courts charge a fee set as a percentage of the claim's value, payable only if the case reaches litigation, and statutory interest applies where no contract rate has been agreed. See Fees, interest and who pays what in Argentina, below, for the exact rates. For claims that are not for a fixed sum of money, national courts apply a separate, periodically updated fixed fee instead of the percentage rate.
What documents do I need to collect a debt in Argentina?
Two documents form the baseline for any Debt Collection Argentina claim: the underlying invoice or contract, and evidence of the formal payment demand sent during the amicable phase. Reaching an enforceable title through the juicio ejecutivo (Step 2, below) requires a further, legally recognised enforceable instrument (título ejecutivo); claims without one still proceed, just through ordinary proceedings instead.
Wer macht was beim Inkasso in Argentinien?
Three types of actor handle a debt claim in Argentina: collection agencies for the amicable phase, lawyers for the judicial phase, and court officers for enforcement. Each operates under its own rules.
Debt collection agencies
Collection agencies run the amicable, pre-legal phase: verifying the debt, then sending reminders and a formal payment demand to reach a voluntary payment or instalment plan. They cannot enforce payment themselves; only a court can authorise enforcement. Their conduct is bound by the Ley de Defensa del Consumidor (the Consumer Protection Law, Ley 24.240), art. 8 bis, which requires dignified and equitable treatment and bans humiliating, vexatious or judicial-appearance-simulating tactics, backed by civil fines under art. 52 bis. In Ciudad Autónoma de Buenos Aires (CABA, Buenos Aires City), Ley 6.171 (2019) adds mandatory disclosure on first contact, a fixed list of permitted channels, and specific bans, including contacting the debtor's employer, exposed mail, calls between 20:00 and 8:00 on weekdays, and unauthorised publication of debtor lists, enforced under Ley 24.240's sanctions regime. Ley 6.171 does not apply to family, labour, or state tax and administrative debts, which fall outside its scope.
Anwälte
Lawyers take over once amicable collection fails. They draft and file the claim, represent the creditor before the competent court, and pursue the enforceable title needed to enforce the debt (see Step 2). Legal representation is required once a case moves to ordinary court proceedings (see Which laws and courts apply, below).
Bailiffs (Oficiales de Justicia)
Court-appointed officers, known as Oficiales de Justicia, execute enforcement once a judge issues an order: attaching assets, freezing bank funds, and carrying out judicial auctions. Argentina has no separate national enforcement or bailiff agency; every enforcement step is supervised directly by the court (see Step 3).
Insolvency trustees (síndicos)
A court-appointed síndico (trustee) takes over if a debtor becomes insolvent: verifying each creditor's claim and administering the case under the Ley de Concursos y Quiebras (see Step 4, below). No single national licensing regime governs commercial debt-collection agencies in Argentina; regulation instead comes from consumer-protection law nationally and from Ley 6.171 in CABA.
Welche Gesetze und Gerichte gelten für das Inkasso in Argentinien?
Governing statutes
Private debt claims run on the general civil and commercial limitation period of 5 years (Código Civil y Comercial, CCyC, art. 2560), with a shorter regime for credit-card debt under Ley 25.065, art. 47 (1 year for an executive action, 3 years for an ordinary action). Civil and commercial procedure, including the route to an enforceable title, runs under the Código Procesal Civil y Comercial de la Nación (the National Civil and Commercial Procedure Code, CPCCN, Ley 17.454 as amended); its juicio ejecutivo (executive process), at Título II, arts. 520-594, applies to claims backed by a legally recognised enforceable instrument. Court costs before national courts are set by the Ley de Tasas Judiciales (the Judicial Fees Law, Ley 23.898). Collection conduct is governed by the Ley de Defensa del Consumidor (Ley 24.240) nationally, and by Ley 6.171 for extrajudicial collection agents contacting debtors in CABA. Insolvency, where relevant, falls under a separate statute covered in Step 4, below. The CPCCN has been amended several times since its enactment, most notably by Ley 25.488. Under Ley 23.898, national courts charge a percentage-based fee for pecuniary claims (art. 2) and a separate, periodically updated fixed fee for non-pecuniary proceedings (art. 6); CABA's consumer-protection authority enforces Ley 6.171 breaches under Ley 24.240's own sanctions regime, specifically at art. 13.
Court structure
National and CABA claims run through the Juzgados Nacionales de Primera Instancia (the National Courts of First Instance, Comercial or Civil y Comercial Federal), with appeals to the Cámara Nacional de Apelaciones (the National Court of Appeals) and, on federal-law questions, the Corte Suprema de Justicia de la Nación (the Supreme Court of Justice). Argentina is a federation: each of its 23 provinces plus CABA sets its own procedural code and small-claims thresholds, so the court and threshold that apply depend on where the debtor is based. As one worked example, not a national rule, Mendoza's Oficina de Pequeñas Causas y Consumo (Small Claims and Consumer Office) hears claims up to ARS 3,200,000 (2026 figure); confirm the current threshold for the debtor's own province before filing. Which court has jurisdiction over a specific claim therefore depends on both the claim's value and the debtor's registered address. Access to the Corte Suprema specifically requires a recurso extraordinario federal (federal extraordinary appeal), reserved for questions of federal law or constitutional significance.
Schritt 1 - Wie funktioniert das außergerichtliche (vorgerichtliche) Inkasso in Argentinien?
Amicable collection in Argentina starts with verifying the debt, then sending the debtor a formal payment demand and negotiating a voluntary payment or instalment plan, without going to court. Most straightforward claims resolve at this stage.
Verification and first contact
Before contacting the debtor, the claim is checked against the invoice, contract or other supporting documents. First contact then sets out the amount owed, the basis for the claim, and a deadline to pay or respond. Argentina has no nationally prescribed demand-letter form for B2B claims; a clear written demand setting out the amount owed, its basis and a deadline to respond is the conventional format used in practice.
Conduct rules
Communication must stay within Ley 24.240, art. 8 bis: dignified and equitable treatment, no humiliating or vexatious tactics, and no contact that simulates a judicial appearance. In CABA, Ley 6.171 adds a fixed disclosure on first contact, permitted channels, and specific bans (contacting the employer, exposed mail, calls between 20:00 and 8:00 on weekdays, unauthorised publication of debtor lists). Breaches carry civil fines under Ley 24.240, art. 52 bis. Permitted channels under Ley 6.171 include phone, email, post, voice or text messages, and instant messaging, provided the debtor's dignity is respected throughout; first-contact disclosure must itemise the original debt, accrued interest and collection costs separately.
Restarting the limitation clock
A written, signed acknowledgement of the debt, or a part-payment, restarts the general 5-year limitation period (CCyC art. 2560) or the credit-card-specific periods under Ley 25.065, art. 47. Securing one, where possible, protects the claim while amicable talks continue. The CCyC's own index lists this specific reset under art. 2545, headed "Interrupción por reconocimiento" (interruption by acknowledgement).
Escalation to court
If the debtor still does not pay, moving to court is a separate, approved step (see Step 2), never an automatic consequence of a missed amicable deadline.
Schritt 2 - Wie erlangen Sie einen vollstreckbaren Titel in Argentinien?
An enforceable title in Argentina comes from a court, most commonly through the national juicio ejecutivo (executive process) when the claim rests on a legally recognised enforceable instrument, or through ordinary proceedings for claims that lack one or are contested on the merits.
Juicio ejecutivo (executive process)
Under the CPCCN, Título II, arts. 520-594, the juicio ejecutivo is a summary procedure available when the creditor holds a legally recognised enforceable instrument. It is faster than ordinary proceedings because the debtor's defences are limited by law, and it ends in a judgment that can go straight to enforcement (Step 3).
Ordentliches Verfahren
Claims without an enforceable instrument, or where the debtor disputes the underlying facts, go through ordinary proceedings under the CPCCN. These allow a fuller exchange of evidence and argument, but take longer, and legal representation is required throughout. For example, a creditor whose credit-card claim has passed the 1-year window for an executive action under Ley 25.065, art. 47, still has 3 years from the same starting point to bring an ordinary action instead.
Provincial small-claims routes: Mendoza as an example
Because each of Argentina's 23 provinces plus CABA sets its own procedural code, lower-value claims may qualify for a faster provincial small-claims track. Mendoza's Oficina de Pequeñas Causas y Consumo, for example, hears claims up to ARS 3,200,000 (2026 figure). This is one province's rule, not a national threshold: confirm the current small-claims limit and procedure for the debtor's own province before filing. This ARS 3,200,000 ceiling is calculated as 5 JUS units at the 2026 JUS value of ARS 628,730.43, under a 2025 amendment to provincial Ley 9.660; Mendoza was the first Argentine province to open such an office, operating since 15 June 2015.
Mehr zu Gerichtsverfahren in Argentinien
Choosing the route
The route depends on what evidence the creditor holds and where the debtor is based. A signed contract, promissory note or other legally recognised enforceable instrument usually supports the juicio ejecutivo; disputed or undocumented claims usually need ordinary proceedings; and lower-value, undisputed claims may qualify for a provincial small-claims track.
What the judgment allows
A favourable judgment, whether from the juicio ejecutivo, ordinary proceedings, or a provincial small-claims track, becomes the enforceable title used to attach assets, freeze bank funds, or force a judicial auction (Step 3).
Schritt 3 - Wie funktioniert die Zwangsvollstreckung von Forderungen in Argentinien?
Once a court issues an enforceable title (Step 2), enforcement in Argentina proceeds through embargo (attachment), inhibición general de bienes (a general freeze on the debtor's assets), or remate (judicial auction), all carried out under the supervision of the court. In the juicio ejecutivo route specifically, this judgment takes the form of a sentencia de trance y remate (order for sale to satisfy the debt).
Enforcement measures
Embargo lets the creditor attach specific assets, such as bank funds or property, up to the value of the claim. Inhibición general de bienes freezes the debtor's ability to sell or encumber assets generally, useful when specific assets are not yet identified. Remate is a judicial auction of seized assets, with proceeds applied to the claim. A court can order more than one of these measures in the same case, depending on what assets are located.
Who carries it out
Argentina has no separate national enforcement or bailiff agency. Every measure is judge-supervised and carried out through the court's own oficial de justicia (court enforcement officer), who locates and values assets, organises the auction where needed, and oversees distribution of the proceeds. The creditor's lawyer requests each measure from the court; the oficial de justicia then executes it. For the auction itself, the court typically appoints a martillero (court-appointed auctioneer) to conduct the sale.
Sequencing and stopping enforcement
Enforcement typically starts with locating assets to attach or freeze, then moves to a judicial auction only if the debtor still does not pay. A debtor can pay off the claim, including accrued statutory interest and costs, at any point before or during enforcement to have the measures lifted.
Order of enforcement in practice
An official state debt-recovery instructional document describes courts typically targeting the debtor's bank accounts first, before moving to real estate or other registered property, then wages, or a general inhibición general de bienes when no specific asset has yet been identified. Enforcement of the judgment itself proceeds under the CPCCN's own Título I, "Ejecución de Sentencias" (Judgment Enforcement), arts. 499-519 bis.
Timelines
Argentine law does not set a fixed statutory deadline for completing enforcement once a title issues; how long it takes depends on how quickly the debtor's assets can be located and valued, and on the court's own caseload. Cases with clearly identified assets, such as a known bank account, generally move faster than cases requiring extensive asset tracing.
Costs
Enforcement adds the tasa de justicia (3% of the claim's pecuniary value under Ley 23.898, art. 2) and any further court and legal-representation costs to the case; see Fees, interest and who pays what, above, for how these costs and any recovered interest are allocated.
Schritt 4 - Wie wirken sich Insolvenzverfahren auf die Beitreibung von Forderungen in Argentinien aus?
Insolvency in Argentina is governed by the Ley de Concursos y Quiebras (the Bankruptcy and Insolvency Law, Ley 24.522, "LCQ"). It applies to individuals and private legal entities alike and offers two paths: concurso preventivo (a court-supervised reorganisation) or quiebra (full bankruptcy and liquidation). Insolvency changes how a creditor recovers a debt: instead of individual enforcement against one debtor's assets, all creditors' claims are handled together, in one court-supervised process.
What triggers insolvency proceedings
The trigger is cesación de pagos, a general inability to regularly meet obligations as they fall due (LCQ arts. 1, 78), rather than a single missed payment. Any individual or private legal entity may petition for concurso preventivo, provided no bankruptcy has already been declared (LCQ arts. 2, 5, 10). Once proceedings open, a creditor's individual enforcement action against that debtor is generally superseded by the collective insolvency process. Eligible petitioners include not only individuals and private legal entities but, in some cases, state-owned entities as well (LCQ arts. 2, 5, 10).
Concurso preventivo (reorganisation)
In a concurso preventivo, the debtor proposes a repayment or restructuring plan to creditors under court supervision, aiming to avoid liquidation, while a court-appointed trustee (síndico) reviews and verifies creditor claims. If the court declares the reorganisation agreement fulfilled, the debtor cannot file for a new concurso preventivo for one year (LCQ art. 59).
Quiebra (full bankruptcy)
Where reorganisation is not attempted or does not succeed, the LCQ's bankruptcy path applies instead: the debtor's assets are liquidated under trustee supervision and the proceeds distributed among creditors according to the priority rules below. This path is the more disruptive of the two for an ongoing business, since it generally ends the debtor's control over its own assets.
How claims are prioritised
Process costs and employees' pronto pago wage and indemnity claims (LCQ art. 16) rank alongside secured creditors' real security (LCQ art. 240); unsecured creditors share what remains, pro rata. Creditors must formally file their claim with the trustee, within the deadlines the trustee sets, to be considered in the distribution; a claim filed late risks being excluded from that round of proceeds.
After the proceedings close
A bankruptcy declaration carries an inhabilitación (a disqualification) for the debtor, which ceases automatically one year after the bankruptcy decree unless extended (LCQ art. 236). Recovery through insolvency proceedings can take time; creditors should expect a court-supervised, multi-step process, with recovery depending on what other creditors also claim and what assets the estate holds, rather than a quick payout. As Mendoza's own Poder Judicial has confirmed, quoting LCQ art. 236 directly, "the disqualification of the bankrupt ceases automatically after one year from the bankruptcy decree."
Gebühren, Zinsen und wer was in Argentinien zahlt
- Unsere Gebühr: erfolgsbasiert – Kein Erfolg, keine Gebühren (siehe Preise).
- Gerichts- & Zwangsvollstreckungsgebühren: staatliche Gebühren fallen nur an, wenn der Fall zu rechtlichen Schritten eskaliert.
- Gesetzliche Schuldnerpositionen: Verzugszinsen und erstattungsfähige Inkassokosten werden der Forderung hinzugefügt, wo es das Gesetz erlaubt.
- Wer behält was: der eingetriebene Hauptbetrag gehört Ihnen; gesetzliche Kosten und Zinsen richten sich nach den lokalen Vorschriften.
Argentina's statutory court fee and interest rate
Before national courts, the tasa de justicia (court fee) is 3% of the claim's pecuniary value (Ley de Tasas Judiciales, Ley 23.898, art. 2). Absent a contractual rate, statutory interest defaults under CCyC art. 768 to a rate set by the BCRA; from January 2026 that reference is the BCRA's Tasa de Intereses Moratorios (TIM), averaging the 30-day time-deposit passive rate and the signature/personal-loan active rate, bounded within CER±3%. The statute's own text sets this rate at "TRES POR CIENTO (3%)" for "todas las actuaciones... susceptibles de apreciación pecuniaria" (three percent, for all proceedings susceptible of pecuniary appraisal); claims that are not for a fixed sum instead pay a separate, periodically updated fixed fee (Ley 23.898, art. 6).
Interest keeps accruing during enforcement
Statutory interest under CCyC art. 768 continues to accrue on the outstanding balance through the amicable phase, litigation and enforcement, until the debt is paid in full; settling early avoids further interest and the court fees described above.
Finden Sie einen Rechtsanwalt für Inkasso vor Ort
Benötigen Sie eine gerichtsfeste Vertretung? Teilen Sie uns Ihren Fall einmal mit und erhalten Sie bis zu drei Angebote von geprüften Prozessanwälten. Kostenlos, schnell und unverbindlich.
- Geprüfte Spezialisten
- Angebote in 24 Stunden, keine versteckte Gebühren
- Faire, vorab ausgehandelte Preise

Bouchard 468 4th G, City of Buenos Aires
Garcia Menendez Rechtsanwaltskanzlei
Garcia Menendez ist eine führende Anwaltskanzlei in Buenos Aires, die effektive Inkassodienstleistungen in Argentinien anbietet, anerkannt von Euromoney Expert Guides und Global Competition Review, mit wettbewerbsfähigen Gebühren und Mitgliedschaft in der MSI Global Alliance, die erstklassige juristische Expertise gewährleistet.

Gerichtsverfahren
gerichtliches Inkasso
Zwangsvollstreckung

5

1996

Anwaltskanzlei
SARMIENTO 643, Ciudad Autonoma de Buenos Aires
Riskma Solutions
Riskma Solutions ist ein führendes Inkassounternehmen in Buenos Aires, das effektive Inkassodienstleistungen in Argentinien anbietet. Es ist seit 2014 für seine strategische Expertise bekannt, arbeitet mit einem Erfolgshonorar-Modell mit einer Erfolgsquote von 70 % und bedient Kunden in Argentinien und Uruguay.
Gerichtsverfahren
gerichtliches Inkasso
Zwangsvollstreckung
5
2014
Inkassounternehmen
Av. Pedersen 2.190
Tandil, Argentinien
Valle&Gallo
Valle&Gallo ist eine führende Anwaltskanzlei, die effektive Inkassodienstleistungen in AR anbietet, die seit 2019 für ihre Expertise anerkannt ist und sich durch Branchenauszeichnungen und Mitgliedschaften auszeichnet, was die Kanzlei zum bevorzugten Partner für Inkasso macht.
Gerichtsverfahren
gerichtliches Inkasso
Zwangsvollstreckung
3
2019
Anwaltskanzlei
Häufig gestellte Fragen
Entdecken Sie unsere häufigsten Fragen und Antworten unten, oder kontaktieren Sie uns direkt unter contact@debitura.com, wenn Sie Hilfe bei einem bestimmten Fall benötigen.
Muss ich in Argentinien vor Gericht gehen, um eine Forderung einzutreiben?

Nicht immer. In der gütlichen Inkassophase in Argentinien werden Briefe, Telefonanrufe und E-Mails genutzt, um eine freiwillige Zahlung zu erwirken, wobei die im Verbraucherschutzgesetz festgelegten Grenzen für missbräuchliche oder zwingende Methoden eingehalten werden. Inkassounternehmen übernehmen diese frühe Phase, können die Zahlung jedoch nicht selbst auf rechtlichem Wege durchsetzen. Scheitern die Verhandlungen, Fall der Fall in ein gerichtliches Verfahren Fall , in dem ein Gerichtsvollzieher – lokal als „Oficial de Justicia“ bezeichnet – den Gerichtsbeschluss vollstreckt.
Wie lange habe ich in Argentinien Zeit, eine Forderung einzutreiben?
The time limit depends on the type of claim. General civil and commercial debt prescribes in 5 years (Código Civil y Comercial, art. 2560). Credit-card debt runs on a shorter, two-track clock under Ley 25.065, art. 47: 1 year to bring an executive action, 3 years to bring an ordinary action. A written, signed acknowledgement of the debt, or a part-payment, restarts the applicable period. Debitura's licensed partner can help assess the deadline for a specific claim.
Welche Gerichte sind in Argentinien für Forderungen zuständig?
Debt claims in Argentina go through the Juzgados Nacionales de Primera Instancia (National Courts of First Instance) at the national/CABA level, with appeals to the Cámara Nacional de Apelaciones (National Court of Appeals) and, on federal-law questions, the Corte Suprema de Justicia de la Nación (Supreme Court of Justice). Each of Argentina's 23 provinces plus CABA also runs its own court system and procedural code, so the specific court and process depend on where the debtor is based.
Was passiert, wenn ein Schuldner in Argentinien zahlungsunfähig wird?
Wenn ein Schuldner in Argentinien zahlungsunfähig wird, fallen die Verfahren unter das Insolvenz 24.522, das sowohl für Privatpersonen als auch für Unternehmen gilt. Dieses Gesetz sieht präventive Insolvenzverfahren zur Sanierung der Finanzen des Schuldners oder ein vollständiges Insolvenz vor, bei dem Vermögenswerte verwertet werden, um die Gläubiger zu befriedigen. Welcher Weg eingeschlagen wird, hängt davon ab, ob der Schuldner eine Sanierung anstrebt oder zur Liquidation gedrängt wird.
Benötigen Sie zusätzliche Länder?
“Debitura recovered well over 100,000 euros in overdue invoices for us across several countries, all through one contract and one dashboard. Local experts handle each market and we only pay when they actually collect — so our team can spend that time on what we do best: helping our own customers engage smarter with the Manago AI platform.”
Manago AI (formerly SALESmanago)
767
Licensed collection agencies and law firms in our network
180
Countries covered, with cases handled in 174 of them
5,306
Businesses registered with Debitura