Debt Collection Agency in District of Columbia: No Cure, No Pay
Your District of Columbia claim is handled by a licensed local collection partner, matched to your case. All actions follow District of Columbia law, and you track everything in one dashboard. Prefer to learn first? Read our District of Columbia debt collection guide.


Questions about your case?
Write to us, we reply by email.
Our local debt collection partners
Debitura is a platform, not a single agency: your case is routed to the licensed collection partner best matched to your claim type, debtor profile and industry. After that, we follow their results on our platform: how much they collect, how fast they respond and how clients rate them.
- Verified specialists
- Fee shown before you submit
- Fair, pre-negotiated rates
Direct Recovery Associates, Inc. is a premier debt recovery agency in Agoura Hills offering effective Debt Collection services in the United States, founded in 1992, with a global reach and performance-based billing, ensuring client satisfaction.
See full partner profile


Law Office of Emely Elizabeth, L.L.C. is a premier law firm in the USA offering effective debt collection services, established in 2023, recognized with the LII Gold award, and a member of the Commercial Law League of America; as a Debitura partner, it provides No Cure No Pay debt collection based on Debitura’s No Cure, No Pay standard terms and pricing.
See full partner profileWhy choose Debitura for debt collection in the District of Columbia?
Debt collection in the District of Columbia, matched to a local partner
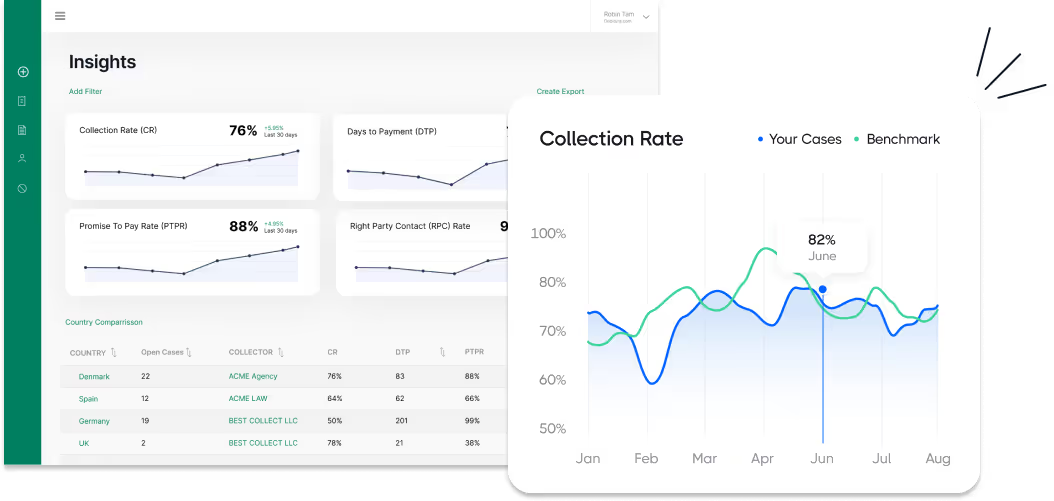
Debitura recovers unpaid invoices from debtors in the District of Columbia through our platform: submit your claim, and we assign it to the best-matching licensed partner working on a No Cure, No Pay basis while you track progress in real time. Your District of Columbia panel is Direct Recovery Associates, licensed by the California Department of Financial Protection and Innovation (Lic. #10186-99) and collecting commercial debt since 1992, alongside the Law Office of Emely Elizabeth, L.L.C., a Rockville, Maryland-based firm whose attorney is admitted before the Supreme Court of Maryland and, per her firm profile, the District of Columbia Bar.
- No Cure, No Pay: Pay only when we recover your money.
- Quick setup: Submit invoices in a few clicks.
- Real-time tracking: Monitor progress live in one portal.
- Local compliance: Consumer-debt collection follows D.C. Code § 28-3814 and the FDCPA; commercial claims follow the contract and general District of Columbia law.
Start recovering your District of Columbia claims in 2 minutes
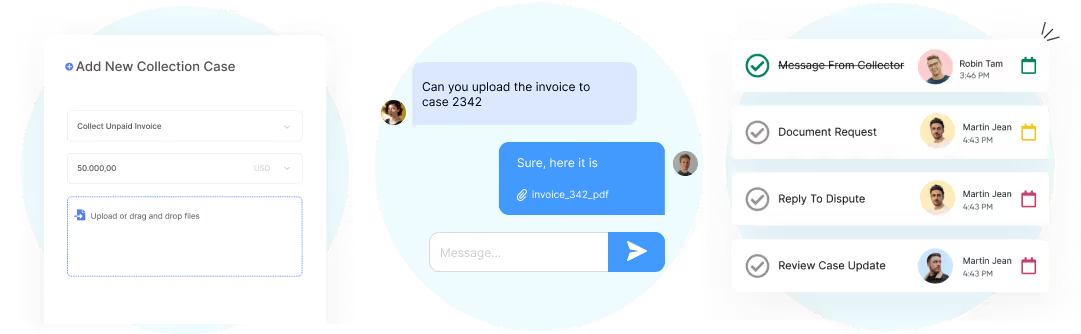
- Submit your claim: Upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- Local collection begins: We assign your case to your District of Columbia panel, Direct Recovery Associates or the Law Office of Emely Elizabeth, who opens the amicable phase with your debtor. If court action is required, typically on the Small Claims and Conciliation Branch's docket for claims up to $10,000, you approve a legal quote, with court costs stated separately, before anything proceeds.
- Get paid: Funds are remitted on recovery. If escalation is needed, only legal steps you have approved in a quote move forward.
Transparent, success-based pricing
With Debitura you only pay when we succeed. Pre-legal collection is No Cure, No Pay: a success fee deducted from recovered amounts, invoiced locally by your partner. Fees depend on the debtor's country, not yours.
- Debtors in Europe (EU, Iceland, Liechtenstein, Norway, the UK and Switzerland): success fees from 6% depending on claim size.
- Debtors in the rest of the world: success fees from 7.5% depending on claim size. On a $10,000 invoice to a US business, under 12 months overdue, the success fee is 15% ($1,500), shown before you submit. Minimum claim: $500. No fee if nothing is recovered.
- Older claims: a surcharge applies for claims 12 to 24 months overdue and for claims older than 24 months.
- Legal action is optional: you approve a legal quote, with court costs stated separately, before any legal spend.
See the pricing page for the full fee schedule, or get an instant estimate when you upload a claim.
How does debt collection work in the District of Columbia?
Debt collection in the District of Columbia starts with an amicable phase: your case is handled by your assigned partner, which issues demands and pursues payment or a written acknowledgment of the debt. Most undisputed commercial claims are resolved at this stage. If the debtor still does not pay, escalation is never automatic; your partner assesses the legal route (typically the Small Claims and Conciliation Branch for claims up to $10,000, or the Civil Division above), and you approve a legal quote before any court step.
- Submit in 2 minutes: upload unpaid invoices in the dashboard. Import by CSV or connect QuickBooks Online, Zoho Books, Stripe or KashFlow, or use Zapier, the REST API or our MCP server.
- No Cure, No Pay: pre-legal collection is success-based, with no setup fees or subscriptions.
- You stay in control: legal escalation only happens after you approve a legal quote.
- Get paid: recovered funds are remitted to you; fees are deducted on success only.
The four steps from unpaid invoice to recovered cash
- Amicable collection: demands and negotiation handled by your District of Columbia panel partner. Most undisputed claims resolve here, without going to court.
- Enforceable title: if the debtor does not pay, your partner assesses the legal route, and you approve a legal quote, with court costs stated separately, before anything proceeds.
- Enforcement: with a judgment, creditors can use writs of attachment and garnishment of wages or property; the District's wage-garnishment formula is more protective than the federal floor.
- Insolvency: if the debtor cannot pay, your proof of claim is filed in the insolvency process and distributions are monitored on your behalf.
Every step is tracked in your dashboard, and nothing escalates without your approval. The full legal detail for the District of Columbia - timelines, costs, courts and enforcement - follows in the guide below.
Debt collection in the District of Columbia - the complete 2026 guide
For in-house counsel, finance teams and out-of-district creditors, this District of Columbia guide covers 2026 debt recovery end-to-end - costs, timelines, limitation and interest, court routes, and post-judgment enforcement - plus step-by-step tools and compact tables to act correctly, fast.
What we will cover:
Why you can trust this guide
Written from primary legal sources and reviewed by licensed local experts in this jurisdiction.
Questions or feedback? Email us at contact@debitura.com , we update this guide based on your input.
Debitura By the Numbers:
- 180 countries covered - each case handled by a local partner
- More than 5,000 businesses registered with Debitura
- 33 days median time to first payment on European cases
About the author
Written by Lars Holdgaard, Founder of Debitura (+10 years in global B2B debt recovery).
Contributing local experts:
Last updated:

Debt collection in the District of Columbia - quick answers
| Question | Answer |
|---|---|
| Main route | Demand letter → amicable collection → Small Claims and Conciliation Branch (claims up to $10,000) or Civil Division → post-judgment enforcement |
| Statute of limitations | 3 years for most contract-based debt (D.C. Code § 12-301(a)(7)); 3 years for consumer debt on any legal theory, with no revival once expired (§ 28-3814(o), (l)); 4 years for UCC sale-of-goods claims (§ 28:2-725) |
| Late-payment interest | 6% per year legal rate absent a contract (§ 28-3302(a)); secondary sources cite a maximum agreed contract rate of 24% per year (§ 28-3301) |
| Small claims | Small Claims and Conciliation Branch hears claims up to $10,000, exclusive of interest, attorney's fees and costs (§ 11-1321); filing fee set by the court's fee schedule |
| Wage garnishment | Limited to 25% of the amount by which weekly disposable wages exceed 40x the DC minimum wage; wages at or below that threshold are fully exempt (§ 16-572) |
| Court & enforcement fees | District fees apply only if the case escalates to legal |
| Our fee | Success fee only - No Cure, No Pay |
How much does debt collection cost in the District of Columbia?
With Debitura you pay a success fee only on amounts actually recovered, with no upfront or monthly costs; the exact rate depends on your claim, see our pricing. Court fees apply only if the case escalates to legal: the Small Claims and Conciliation Branch's filing fee is set by the court's current fee schedule, plus service-of-process costs, and enforcement costs vary. These district fees are advanced by the creditor and can generally be recovered as court costs if you prevail.
How long does debt collection take in the District of Columbia?
Most undisputed commercial claims are resolved in the amicable phase without court involvement. If escalation is needed, the Small Claims and Conciliation Branch is the fastest judicial route for claims up to $10,000, while larger or contested Civil Division cases take substantially longer. Enforcement timing depends on locating non-exempt assets and income.
What are the limitation and interest rules in the District of Columbia?
The statute of limitations on most simple contracts, oral agreements and open accounts is 3 years from accrual (D.C. Code § 12-301(a)(7)); UCC sale-of-goods claims run 4 years (§ 28:2-725), and an instrument under seal (non-consumer) runs 12 years (§ 12-301(a)(6)). Consumer debt carries its own 3-year period on any legal theory, and once it expires, no payment or acknowledgment revives it (§ 28-3814(o), (l)); suing on a knowingly time-barred consumer debt is itself a prohibited practice (§ 28-3814(f)(10)). The legal interest rate absent a contract is 6% per year (§ 28-3302(a)); secondary sources cite a maximum agreed contract rate of 24% per year (§ 28-3301).
What documents do I need to collect a debt in the District of Columbia?
Assemble the contract or purchase order, the invoice(s), delivery or proof-of-service records, an account statement, your demand letters and reminders, and any written acknowledgment or payment agreement. If you are represented, add a power of attorney.
Which route should my claim take?
Claims up to $10,000 belong on the Small Claims and Conciliation Branch, where a corporation may appear through an authorized officer, director or employee. Larger or more complex claims go to the Civil Division. With Debitura, escalation only happens after you approve a legal quote.
Who does what in District of Columbia debt collection?
Debt collection agencies in the District of Columbia
The District of Columbia does not appear to impose a dedicated collection-agency license or bond requirement; a collector operating in DC needs only the general Basic Business License issued by the Department of Licensing and Consumer Protection (DLCP). Your District of Columbia panel operates in compliance with the credentials documented on their Debitura profiles: Direct Recovery Associates is licensed by the California Department of Financial Protection and Innovation (Lic. #10186-99), and the Law Office of Emely Elizabeth, L.L.C. is admitted before the Supreme Court of Maryland and, per her firm profile, the District of Columbia Bar.
District of Columbia courts and enforcement officers
The Small Claims and Conciliation Branch of the Superior Court's Civil Division hears claims up to $10,000; the Civil Division hears larger amounts. After judgment, recording the judgment with the Recorder of Deeds creates a lien on the debtor's real property in the District.
Debt-collection attorneys in the District of Columbia
Attorneys are allowed but not required on the Small Claims and Conciliation Branch, where a corporation may appear through an authorized officer, director or employee.
Regulators
The DC Office of the Attorney General's Office of Consumer Protection enforces the debt-collection law; the Department of Licensing and Consumer Protection (DLCP) handles business licensing, and the Department of Insurance, Securities and Banking (DISB) supervises financial institutions. The CFPB and FTC oversee consumer debt collection federally.
Which laws and courts apply to debt collection in the District of Columbia?
Key legislation in the District of Columbia
Consumer debt collection in the District of Columbia is governed by D.C. Code § 28-3814, substantially rewritten by the Protecting Consumers from Unjust Debt Collection Practices Amendment Act of 2022 (D.C. Law 24-154), which applies as of January 1, 2023, alongside the federal Fair Debt Collection Practices Act. The statute reaches debt incurred for personal, family, medical or household purposes; pure business-to-business debt is governed by the contract and general District of Columbia law. Recent change: technical-clarification amendments (D.C. Law 25-5 and D.C. Law 25-157, 2023-2024) fine-tuned definitions and mechanics without changing the consumer-only scope or the 3-year statute of limitations.
Civil court system in the District of Columbia
The Small Claims and Conciliation Branch of the Superior Court's Civil Division hears claims up to $10,000 (D.C. Code § 11-1321); the Civil Division hears larger civil matters.
Consumer protection
The DC Office of the Attorney General's Office of Consumer Protection enforces the debt-collection law through the DC Consumer Protection Procedures Act (D.C. Code § 28-3905).
Step 1 - How does amicable (pre-legal) debt collection work in the District of Columbia?
Amicable collection in the District of Columbia is handled by your assigned panel partner, which contacts the debtor with formal demands and pursues payment, a payment agreement, or a written acknowledgment of the debt. Most undisputed commercial claims resolve in this phase without court involvement. For consumer debt, once the 3-year limitation period expires, no subsequent payment or acknowledgment revives it (D.C. Code § 28-3814(l)), and suing on a knowingly time-barred consumer debt is itself a prohibited practice (§ 28-3814(f)(10)).
When to escalate to court in the District of Columbia
Escalation is never automatic. It becomes relevant when the debtor is unresponsive, disputes the claim without merit, or the claim is approaching its limitation deadline (3 years for most contract-based debt, 4 years for UCC sale-of-goods claims). Your partner assesses the legal route and you approve a legal quote before any court step.
Step 2 - How do you obtain an enforceable title in the District of Columbia?
Fast-track option: the Small Claims and Conciliation Branch
Small claims in the District of Columbia are heard on the Small Claims and Conciliation Branch of the Superior Court's Civil Division, defined as claims up to $10,000, exclusive of interest, attorney's fees and costs (D.C. Code § 11-1321).
| DC Small Claims and Conciliation Branch | |
|---|---|
| Claim limit | $10,000, exclusive of interest, attorney's fees and costs |
| Filing fee | Set by the Superior Court's current civil fee schedule, plus service-of-process costs |
| Business claimants | Corporations and LLCs may sue; representation by an authorized officer, director or employee is permitted |
| Attorney rules | Allowed, not required |
Ordinary proceedings in the District of Columbia
Claims above $10,000, or complex and contested cases, are heard in the Civil Division. With Debitura, nothing is filed without your approval of a legal quote.
Determining the appropriate court
The route is determined by the amount in controversy, the complexity of the dispute, and venue.
Step 3 - How does debt enforcement work in the District of Columbia?
Ways to enforce a claim in the District of Columbia
With a judgment, creditors can use a writ of attachment/execution against non-exempt personal property and a writ of garnishment against wages or bank accounts held by third parties. Wage garnishment reaches only 25% of the amount by which the debtor's weekly disposable wages exceed 40 times the District's minimum hourly wage; wages at or below that threshold are fully exempt (D.C. Code § 16-572) - more protective than the plain federal 25%/30x rule because of the District's higher local minimum wage and larger multiplier. A debtor may move to exempt wages under § 16-572.01.
How to collect a judgment in the District of Columbia
A District of Columbia judgment is enforceable by execution for 12 years from when execution could first issue, or from the last order of revival (D.C. Code § 15-101), and can be renewed by revival before expiry. Recording the judgment with the Recorder of Deeds creates a lien on the debtor's real property in the District, lasting as long as the judgment remains in force (§ 15-102).
Step 4 - How do insolvency procedures work in the District of Columbia?
Business insolvency is governed by the federal Bankruptcy Code, with Chapter 7 liquidation and Chapter 11 reorganization as the main routes. Once a bankruptcy is filed, the automatic stay halts individual collection actions, and recovery runs through the insolvency estate: your proof of claim is filed in the process and distributions follow the statutory priority order. Your District of Columbia panel partner files the claim and monitors distributions on your behalf, so nothing is lost for lack of follow-up.
Fees, interest and who pays what in the District of Columbia
Debitura's pre-legal collection in the District of Columbia is success-based - No Cure, No Pay, with no setup fees or subscriptions.
Court and enforcement fees - only if the case escalates to legal
District fees apply only if the case escalates to legal. The Small Claims and Conciliation Branch's filing fee is set by the Superior Court's current civil fee schedule, plus service-of-process costs, and enforcement costs vary. These fees are advanced by the creditor and can generally be recovered as court costs if you prevail.
Interest and late fees the debtor owes - from the amicable phase
The District of Columbia's legal interest rate absent a contract is 6% per year (D.C. Code § 28-3302(a)). Private judgments carry interest at 70% of the IRS § 6621 underpayment rate, published quarterly by the DC Courts - 5% for the quarter beginning January 1, 2026 (§ 28-3302(c)); judgments against the District itself are capped at 4% per year (§ 28-3302(b)). Secondary sources cite a maximum agreed contract rate of 24% per year (§ 28-3301). The District sets no general statutory cap on private B2B late-payment fees beyond that usury ceiling; the contract governs. Separate prompt-payment interest rules exist for District government contracts and private construction subcontracts, but do not apply to general B2B trade credit.
Collecting a District of Columbia debt from out of state or abroad
Creditors outside the District of Columbia can enforce sister-jurisdiction judgments under the Uniform Enforcement of Foreign Judgments Act (D.C. Code § 15-351 et seq.), filed with the Clerk of the Superior Court, and new suits are filed in the District when connected to the debtor or the obligation. Out-of-district and international creditors work through the same District of Columbia panel: your case is routed to the licensed partner best matched to your claim, with the same No Cure, No Pay terms, and cross-border cases draw on Debitura's network across 180 countries.
Frequently Asked Questions
Explore our most common FAQs below, or reach out directly at contact@debitura.com if you need help with a specific case.

Need debt recovery beyond the District of Columbia?
Explore our North America debt-collection hub for country-by-country playbooks.
For coast-to-coast coverage in the US, see the U.S. debt-collection overview.